


Warner Bros. Discovery (WBD) is back in focus after PowerA agreed to a multi-year licensing deal to produce Harry Potter themed gaming accessories for Nintendo Switch 2 and Xbox platforms, extending the Wizarding World into everyday play.
For investors tracking momentum, Warner Bros. Discovery shares have climbed to US$30.90, with a 30 day share price return of 7.40% and a 90 day share price return of 15.90%. The 1 year total shareholder return of 63.80% and 3 year total shareholder return of roughly 3x signal that interest in the story has been rebuilding even before the latest Harry Potter licensing deal and the pending Paramount Skydance acquisition headlines.
Scan beyond Warner Bros. Discovery and see how other media and entertainment players are positioned with our curated list of 16 high quality undiscovered gems.
Warner Bros. Discovery now trades just above the average analyst target while some intrinsic value models still show a meaningful gap. Is the recent run closing that distance or leaving upside on the table?
Most Popular Narrative: 70.1% Overvalued
Against a last close of $30.90 for Warner Bros. Discovery, the most followed narrative pegs fair value at $18.17. This points to a wide valuation gap that colors how investors interpret every new licensing deal and merger headline.
The additional financing and debt security further removes any existing barriers to full attention paid to acquisition and merger strategies that will streamline the combined companies and lead to quick profitability, resulting in maximum margin enhancement and cash flow. Investors can be confident that with financing concerns addressed, integrating the most complimentary aspects of both companies will move to the forefront.
See why 13 investors see Warner Bros. Discovery as 70% overvalued.
Result: Fair Value of $18.17 (OVERVALUED)
Still, the Paramount merger process and Warner Bros. Discovery’s recent net loss introduce execution and financing risks that could reshape how investors view that overvaluation call.
Find out about the key risks to this Warner Bros. Discovery narrative.
Another View: Warner Bros. Discovery Through Market Ratios
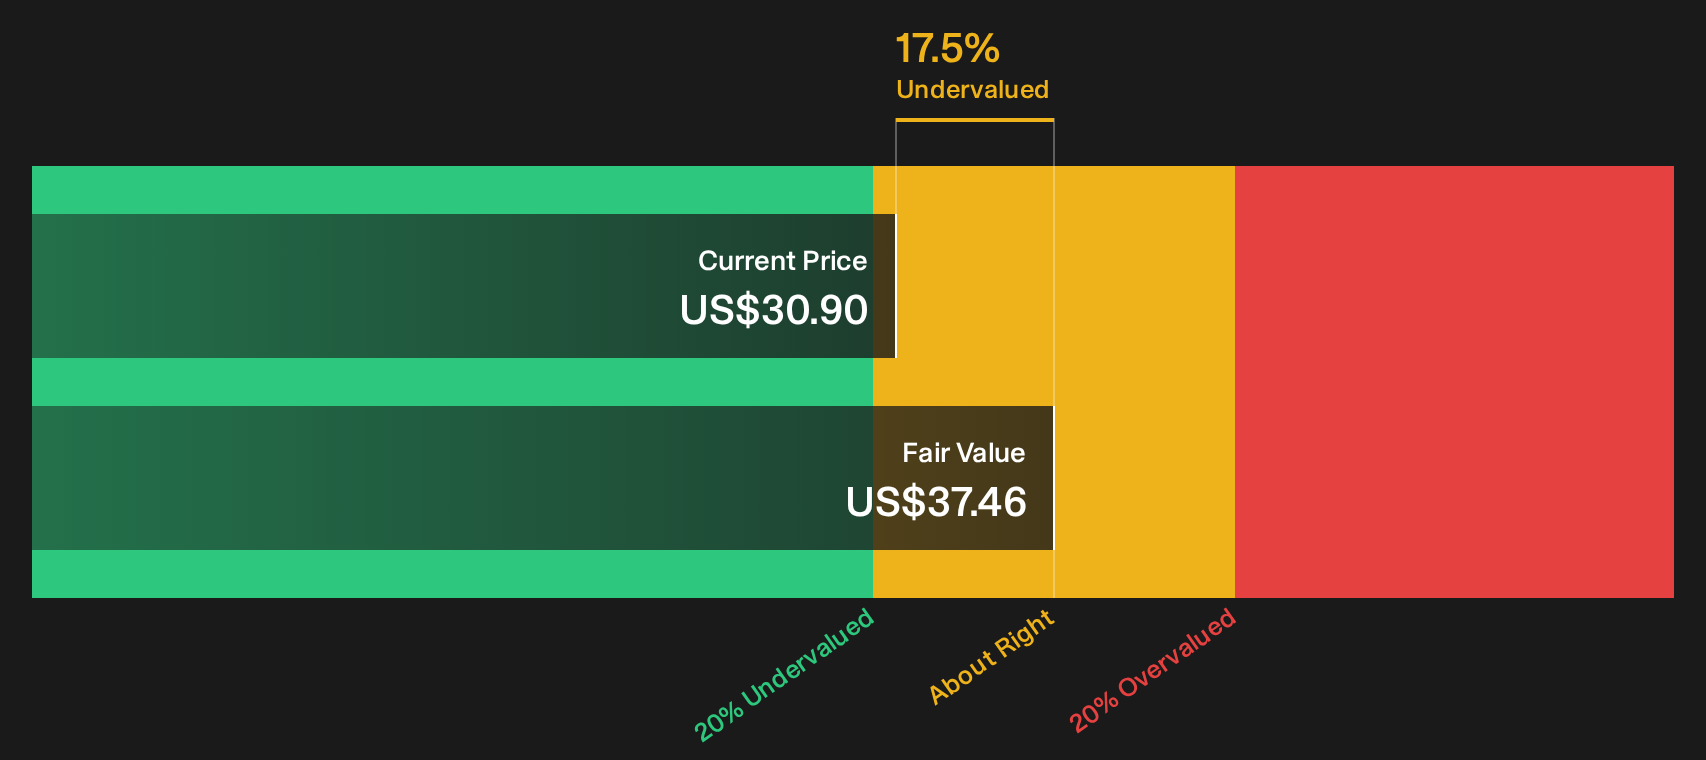
The SWS DCF model flags Warner Bros. Discovery as cheap, with the $30.90 share price sitting about 17.5% below an estimated fair value of $37.46. That directly clashes with the $18.17 narrative fair value that frames WBD as heavily overvalued. Which lens do you trust when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Warner Bros. Discovery is split, with sharp views on both risk and upside potential, so move quickly and test the numbers for yourself. To weigh the trade off between potential rewards and the concerns flagged by other investors, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Warner Bros. Discovery?
Consider expanding your research beyond Warner Bros. Discovery so a broader watchlist can surface opportunities that match your goals and risk comfort more closely.
- Target potential mispricings by scanning companies that screen as quality but out of favor through the 32 high quality undervalued stocks.
- Build a steadier income base by reviewing businesses that qualify as 6 dividend fortresses.
- Prioritize resilience by focusing on companies highlighted in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com