


- Jabil was added to the FTSE All-World Index in September 2026 and is preparing to release Q4 results while working under a sizeable AI infrastructure purchase agreement with Akamai Technologies.
- The Akamai-backed AI infrastructure order highlights how Jabil is tying its manufacturing capabilities to concrete, large scale demand from data infrastructure customers rather than abstract AI themes.
- We will now look at how Jabil's investment narrative could be influenced by the Akamai backed AI infrastructure purchase commitment.
Scan beyond Jabil and Akamai by weighing it up against a curated 87 AI infrastructure stocks that is shaping the build out of data centers and next generation compute capacity.
Jabil Investment Narrative Recap
To own Jabil, you need to believe its manufacturing engine can keep shifting toward higher value areas like AI infrastructure, healthcare and cloud hardware while working through softer pockets such as EV, renewable energy and consumer devices. The Akamai AI order and FTSE All World inclusion both speak to demand visibility, but they do not remove execution risk.
In the near term, the key swing factor is how Q4 results and guidance reflect AI related orders versus pressure in Regulated Industries and Connected Living and Digital Commerce. The main risk is that weakness in EV, renewable energy and consumer gear, combined with elevated inventory days and high debt, compresses cash flow just as Jabil leans into these growth projects.
The Akamai backed AI infrastructure commitment is the headline link to the current story around Jabil. It puts real volume against the AI narrative and ties directly into the Intelligent Infrastructure segment, where management has pointed to strong AI related demand and targeted revenue growth in that area.
For catalysts, that order matters most if it helps offset softness in other divisions and supports the aim to expand higher margin technology work. The flip side is concentration and execution risk. If AI customers delay or resize projects, while EV and renewable energy end markets remain cautious and tariffs bite, Jabil could feel pressure on both revenue mix and free cash flow.
Jabil's current consensus narrative points to revenues of $54.9b and earnings of $2.2b by 2029, based on analysts assuming 17.8% yearly top line growth and an earnings increase of about $1.3b from $862.0m today.
Discover why Jabil's fair value suggests a 35% potential upside to its current price, and how the gap between expectations and valuation could begin to narrow.
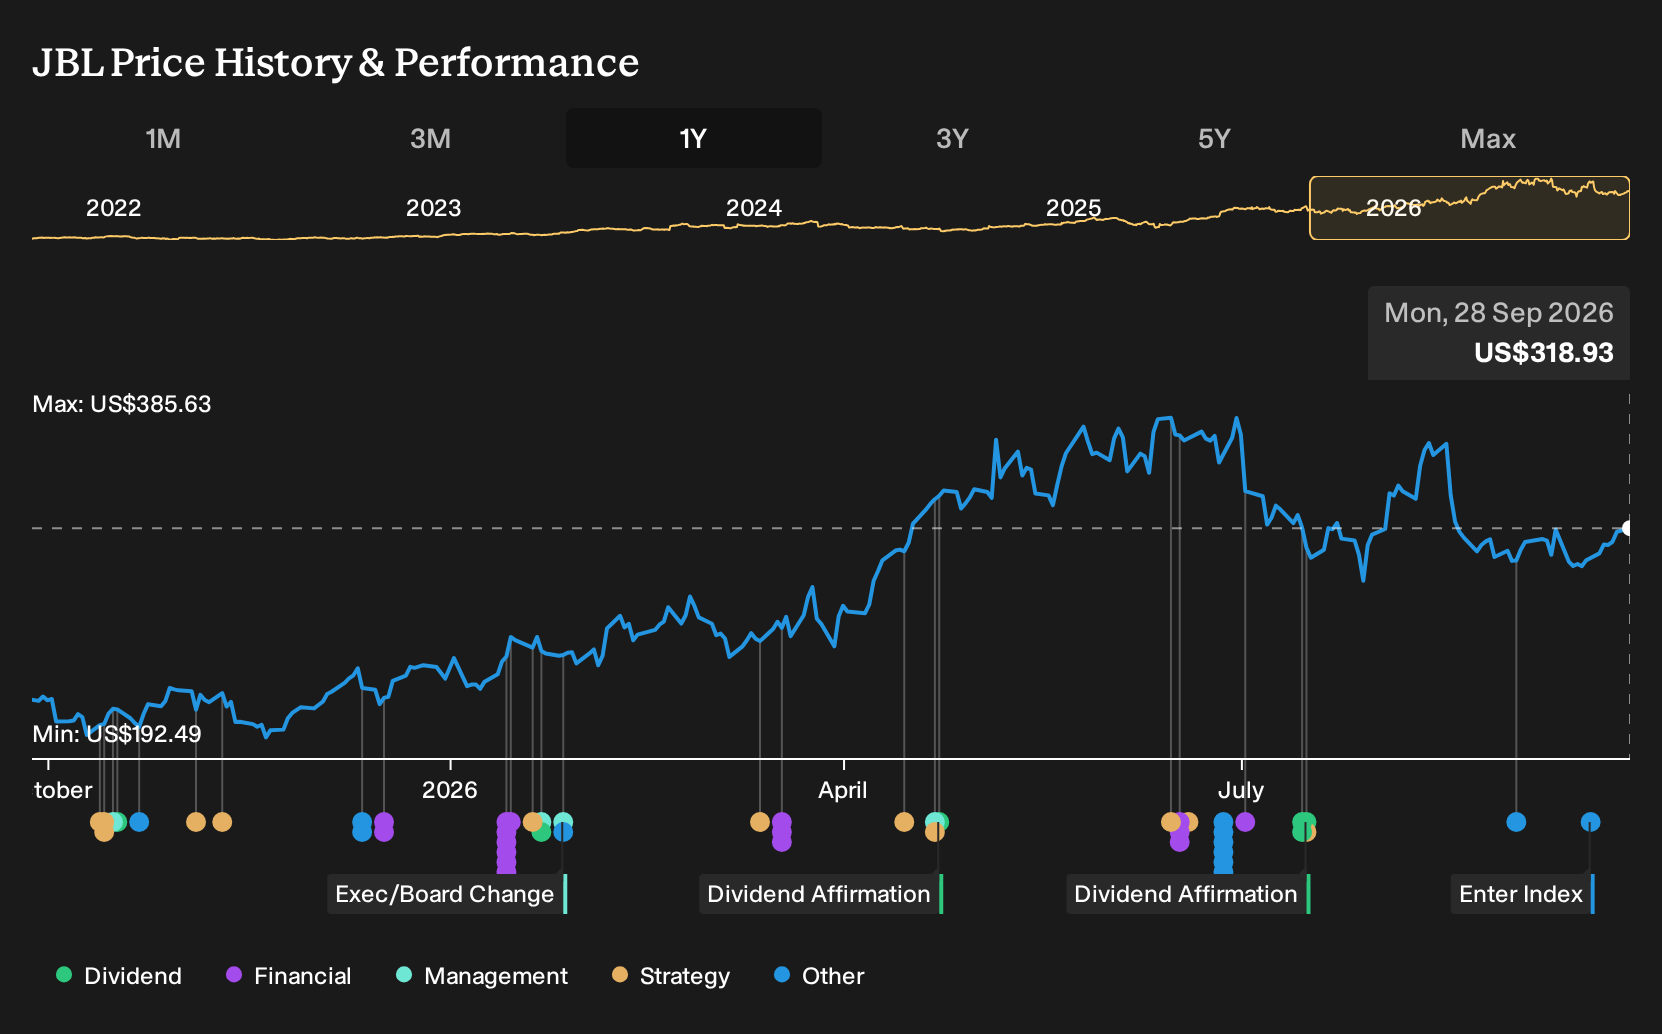
Exploring Other Perspectives
One alternate view says the real swing factor for Jabil is how concentrated its AI customer base has become. The most bearish analysts were pencilling in about US$53.9b of revenue and US$2.1b of earnings by 2029, before this FTSE All World addition and Akamai agreement, which could nudge those expectations in either direction.
Explore 2 other Jabil fair value estimates, including one that suggests it could be worth just $427.33!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Jabil research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Jabil. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Jabil's overall financial health at a glance.
Looking For More Ideas Beyond Jabil?
After weighing Jabil's AI story and FTSE All World inclusion, it can help to place those insights alongside other companies that fit different risk and return profiles. The Simply Wall St Screener is built for exactly that kind of comparison, so you can test your thesis on Jabil against a wider field of candidates.
- If capital preservation is a priority, start with companies that score well on resilience and balance sheet strength by scanning a 30 resilient stocks with low risk scores that might suit a more cautious approach.
- For investors hunting for mispriced quality, compare Jabil with a curated 32 high quality undervalued stocks that blends solid fundamentals with discounted valuations.
- If you are comfortable with smaller companies and want potential upside in less crowded areas of the market, scan through a 16 high quality undiscovered gems that rarely appears on mainstream radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com