


Colgate-Palmolive (CL) is back on income investors’ radar after its board affirmed a quarterly cash dividend of US$0.53 per share, extending a payout stream that dates back to 1895.
Colgate-Palmolive’s share price has eased in recent months, with a 30-day share price return that declined 4.7% and a 90-day move that fell 5.6%. However, the year-to-date share price return is up 11.4% and the 3-year total shareholder return sits above 30%, suggesting longer term holders have still seen steady gains while near term momentum has cooled.
Compare Colgate-Palmolive’s income profile with a curated group of resilient payers in our 6 dividend fortresses to see how its long-running distributions stack up against other high-yield candidates.
Colgate-Palmolive’s brands, cash generation and century long dividend record point to a durable franchise, yet the share price has cooled in recent months. So are you paying up for quality here, or getting it at a reasonable tag?
Most Popular Narrative: Fairly Valued
Colgate-Palmolive’s most followed valuation narrative pegs fair value at $86.48, almost identical to the recent close at $86.52. This frames today’s price as tightly aligned with its underlying cash generation and modest growth assumptions.
The distortion runs through every derived metric. The dividend payout looks stretched at roughly 82% of GAAP EPS and is about 57% of Base Business EPS. The stock looks expensive at 35 times GAAP earnings and trades near 24 times normalised. The trailing twelve month margin carries the same contamination, because the fourth quarter of 2025 still sits inside the window.
See why 9 investors see Colgate-Palmolive as 0% overvalued.
Result: Fair Value of $86.48 (ABOUT RIGHT)
Still, the story can slip if North America remains weak for longer or if another impairment in skin health signals deeper problems in that unit.
Find out about the key risks to this Colgate-Palmolive narrative.
Another View: Colgate-Palmolive Through The SWS DCF Lens
The fair value narrative of $86.48 frames Colgate-Palmolive as roughly correctly priced, yet the SWS DCF model points in a different direction. On that cash flow based approach, CL at $86.52 is trading about 32.5% below an estimated value of $128.18, which flags a potential valuation gap.
This kind of split between an earnings based fair value and a discounted cash flow result raises a practical question for investors. Which signal should carry more weight in your process: the cleaner multiple based view or the SWS DCF model that leans more heavily on long term cash generation assumptions?
Look into how the SWS DCF model arrives at its fair value.
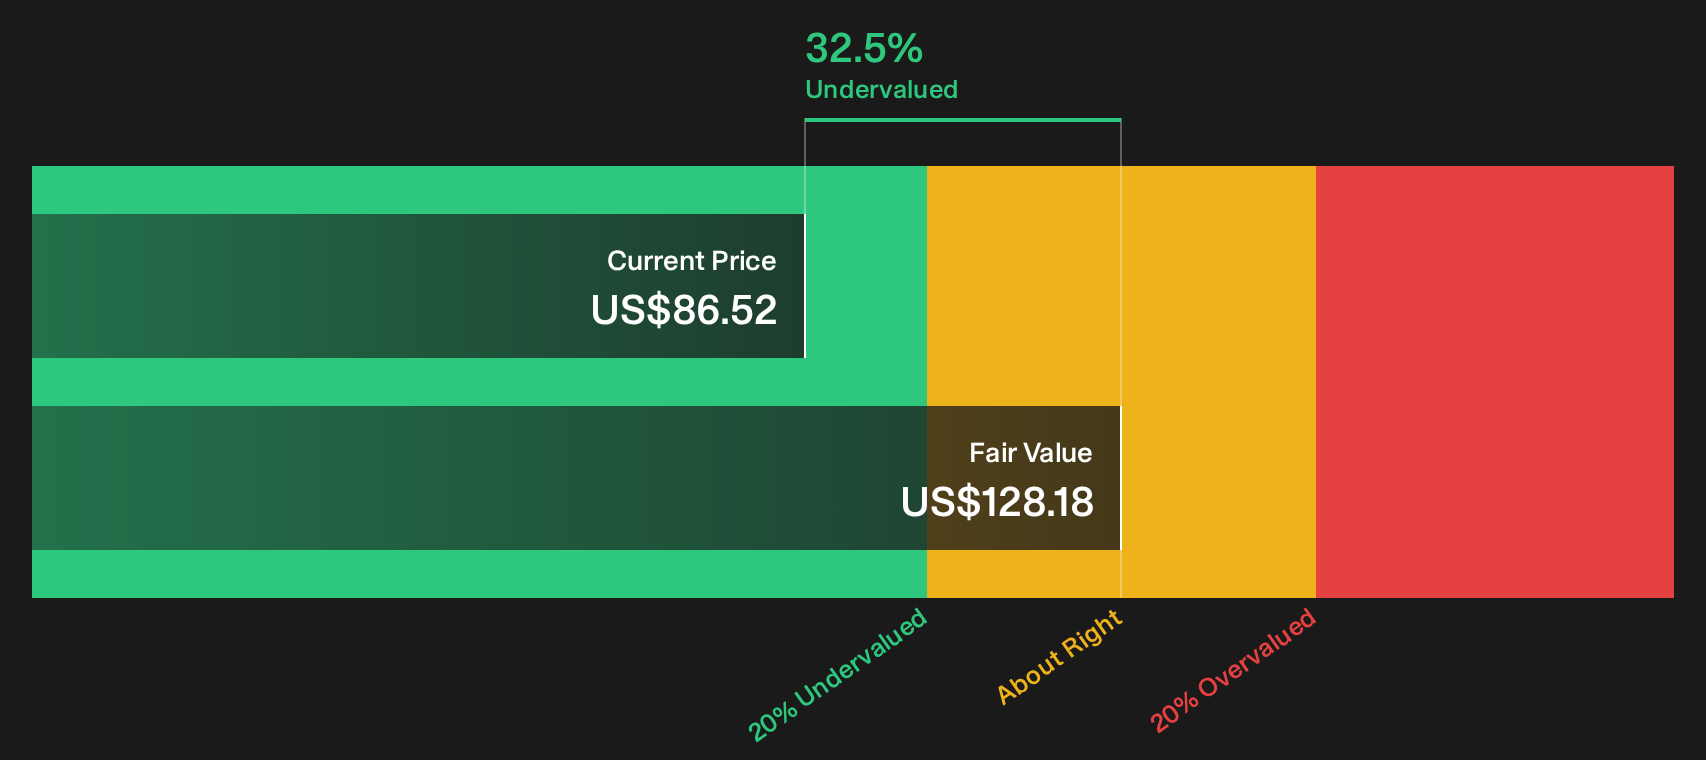
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Colgate-Palmolive’s value and its income appeal make this a moment to move quickly, review the full data set, and decide where you stand based on 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Colgate-Palmolive?
Do not stop with one stock. Put today’s research to work by scanning new opportunities that match your risk profile, income needs, and return expectations.
- Target resilient income by reviewing a curated universe of strong payers in the 6 dividend fortresses that could complement Colgate-Palmolive’s dividend profile.
- Hunt for pricing gaps by checking the 32 high quality undervalued stocks that may trade at a discount to their fundamentals before other investors pay attention.
- Prioritise capital preservation by focusing on the 30 resilient stocks with low risk scores that aim to keep downside contained while you stay invested.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com