


- ADMA Biologics has become a focus for investors after swings in recent performance, as attention turns to its plasma-derived therapies business, its FDA-approved yield enhancement process, and ongoing class action lawsuits tied to product channel practices.
- The key operational talking point is the planned commercial-scale rollout of a yield enhancement process that could materially lift immunoglobulin output and reshape the cost profile of ADMA Biologics' plasma portfolio starting in early 2026.
- This review considers how ADMA Biologics' investment narrative is influenced by the planned yield enhancement rollout and shifting investor attention.
Compare the ADMA Biologics story with a curated set of plasma and healthcare peers by scanning 37 healthcare AI stocks that could be setting up for the next round of rerating.
ADMA Biologics Investment Narrative Recap
To be comfortable owning ADMA Biologics, you need to believe the plasma-derived portfolio around ASCENIV and BIVIGAM can keep pulling in demand, while the FDA-approved yield enhancement process scales smoothly. The key near term operational swing factor is whether management can keep plasma collection volumes and plant throughput on track into the planned 2026 rollout.
The biggest current risk sits in execution and legal overhang. Any disruption at the Boca Raton facility or a setback with the yield process could pinch margins just as expectations build. Ongoing class action lawsuits around product channel practices may also weigh on sentiment, even if the core manufacturing story stays intact.
With no fresh headline announcements in the last batch, the item that still feels most relevant is the planned commercial-scale implementation of the FDA-cleared yield enhancement process. For ADMA Biologics, this is the operational fulcrum. Management is targeting more than 20% higher bulk immunoglobulin output. If achieved, this could materially reshape unit economics.
Your decision really comes down to conviction on that rollout. Successful execution could support higher gross margins on a business that already reports US$512.3m of revenue and US$169.0m of net income. Any delay, regulatory friction or process inefficiency in that implementation, particularly at Boca Raton, would cut directly against the core catalyst investors are watching.
ADMA Biologics' current analyst script points to US$814.2m in revenue and US$330.4m in earnings by 2029. That profile assumes 16.9% yearly revenue growth and an earnings increase of about US$165.0m from US$165.4m today.
Uncover why ADMA Biologics' fair value indicates a 74% potential upside to its current price, which could narrow quickly.
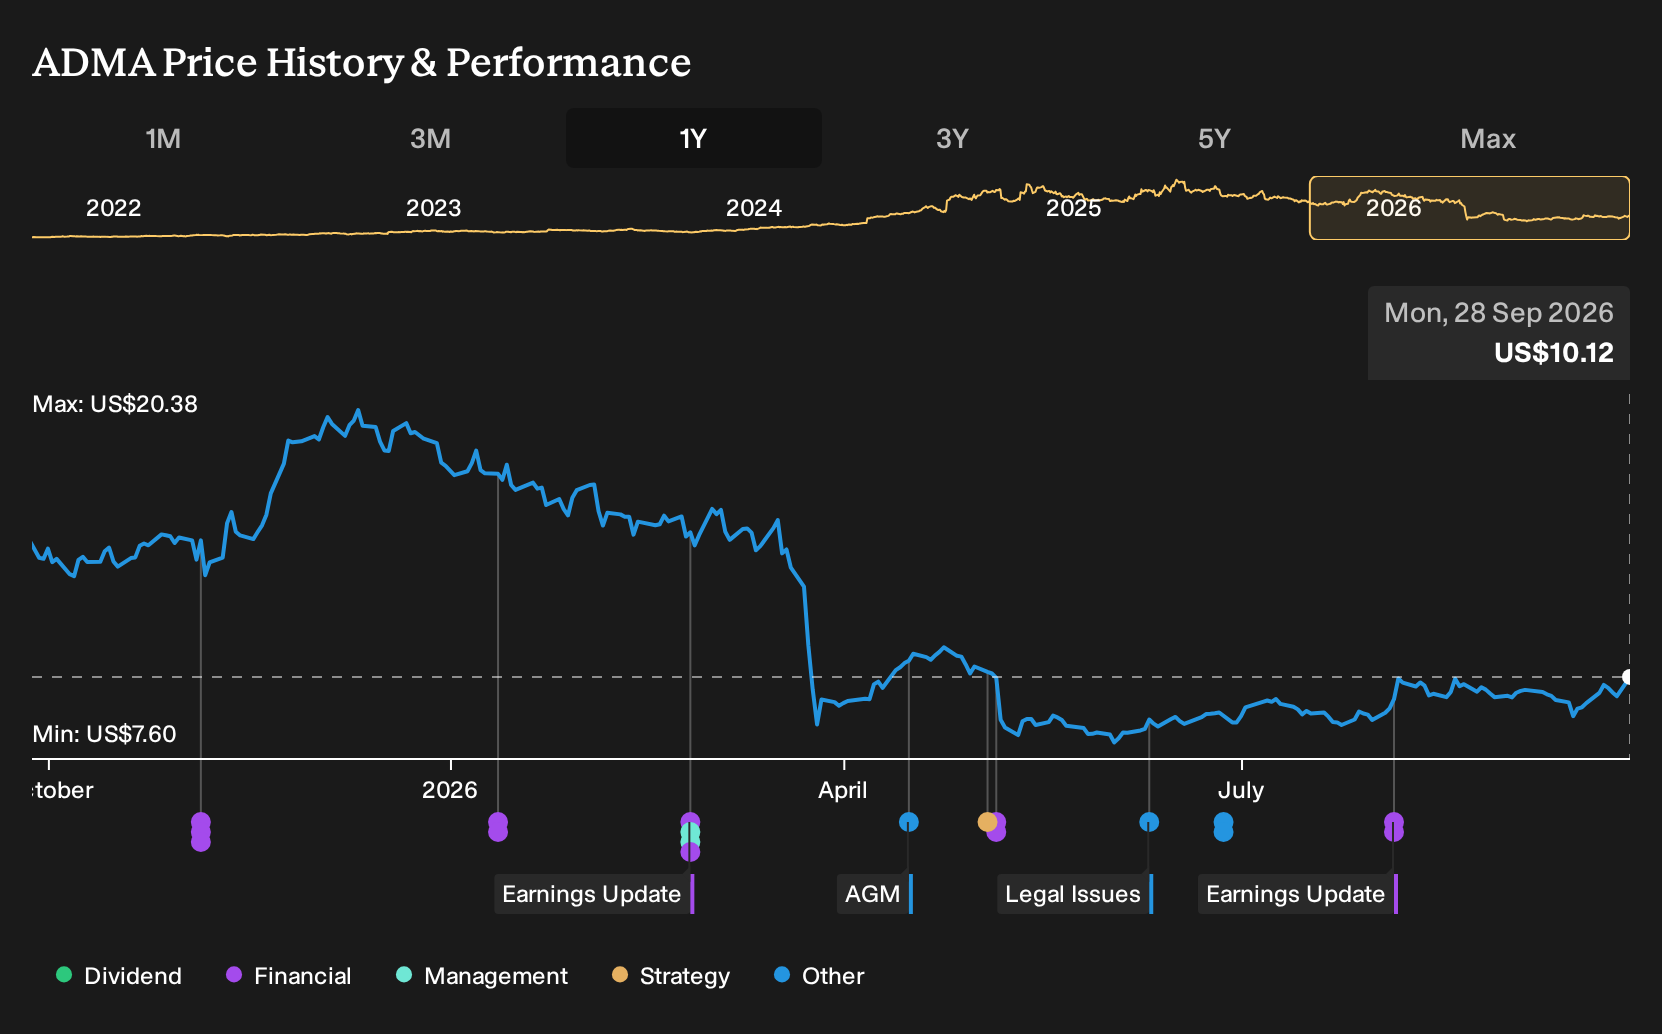
Exploring Other Perspectives
For a contrasting angle on ADMA Biologics, focus on the legal overhang. The most cautious analysts emphasize the class action risk and investigations, which is why their 2029 earnings view sits closer to US$281.4 million on about US$727.0 million of revenue. These estimates were set before the recent news, so treat them as starting points and consider how your own view might change from here.
Explore 7 other ADMA Biologics fair value estimates, including one that suggests it could be worth just $12.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ADMA Biologics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ADMA Biologics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ADMA Biologics' overall financial health at a glance.
Looking For More Ideas Beyond ADMA Biologics?
If the ADMA Biologics story has sharpened your thinking about risk, balance sheets, and upside potential, it can be useful to contrast that with a wider set of companies that share some of those qualities. The Simply Wall St Screener can help you scan for stocks that fit different styles so you can build a watchlist that matches your own approach.
- If capital preservation is top of mind, use the screener to review 30 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering room for upside.
- If quality at a reasonable entry point appeals to you, scan the 16 high quality undiscovered gems that the market may not be fully focused on yet.
- If balance sheet resilience matters most, filter for a list of solid balance sheet and fundamentals (25 results) and compare how their financial footing stacks up against ADMA Biologics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com