


BCI Minerals (ASX:BCI) has drawn fresh attention after announcing significant board changes. These include the appointment of veteran executive Ian Hansen and the pending departure of long-serving director Chris Salisbury.
Recent trading suggests investors are paying close attention to these board moves. BCI Minerals has an A$0.615 share price, a 30-day share price return of 28.12% and a 90-day share price return of 57.69%. The 3-year total shareholder return of 142.12% indicates momentum that has been building over a longer horizon.
Scan beyond BCI Minerals and compare this board-driven momentum story with a curated list of resource companies in our 36 best rare earth metal stocks.
After a sharp A$0.615 move on board news and only a modest 3.3% discount to analyst targets, the live question for BCI Minerals is whether that small gap still reflects justified caution or mispriced progress.
Most Popular Narrative: 2% Undervalued
On the latest Simply Wall St narrative, BCI Minerals screens as slightly undervalued, with a fair value of A$0.63 against the A$0.615 close. This puts board changes alongside a valuation story that already reflects significant project expectations.
Advancing construction at Mardie with 93 percent pond inundation, crystallizer sealing underway and key marine works at 93 percent completion positions BCI for first salt on ship in late 2026. This is expected to support a step change in revenue as production ramps toward nameplate volumes.
See why 5 investors see BCI Minerals as 2% undervalued.
Result: Fair Value of A$0.63 (UNDERVALUED)
Still, the BCI Minerals narrative leans heavily on Mardie execution, where any construction overruns or weaker industrial salt and SOP demand could quickly challenge today’s upbeat assumptions.
Find out about the key risks to this BCI Minerals narrative.
Another View on BCI Minerals' Valuation
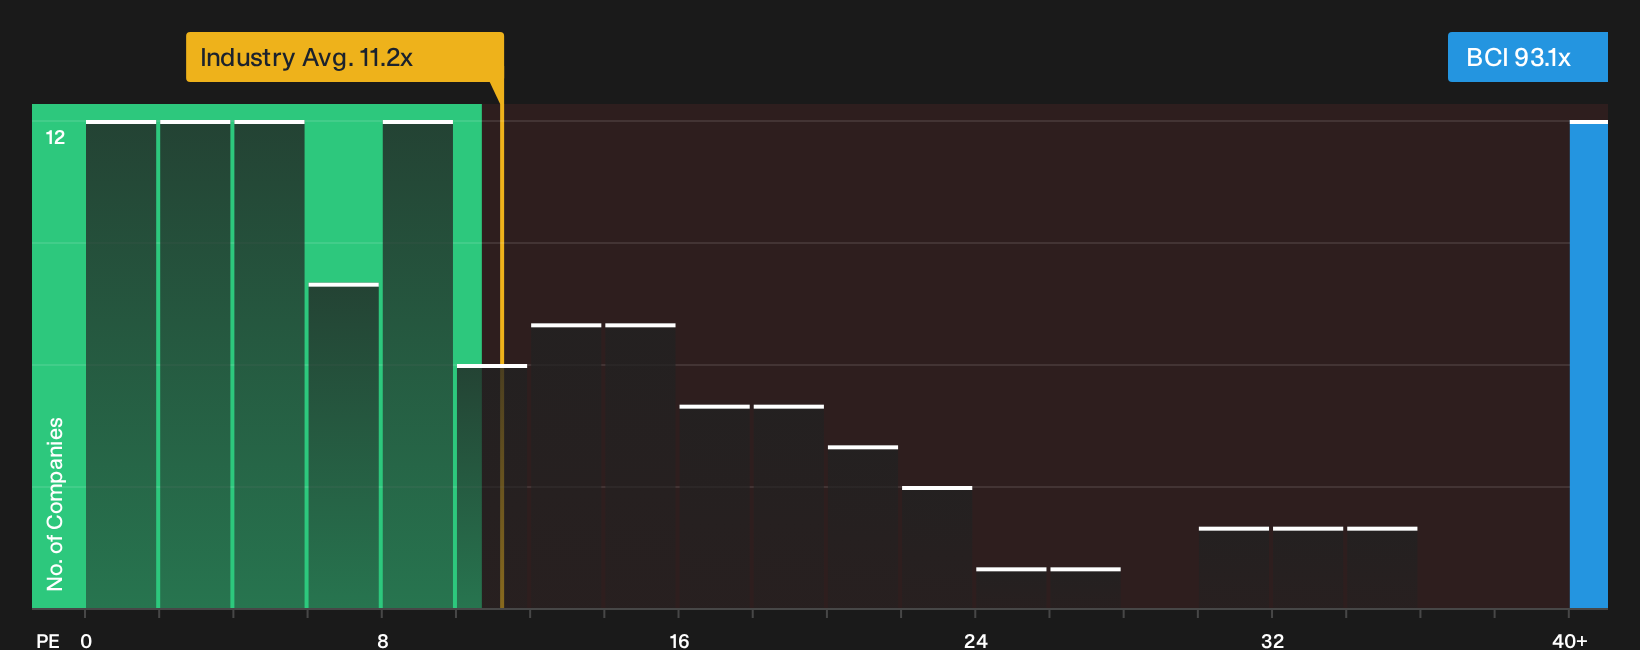
The narrative tags BCI Minerals as undervalued on fair value, yet the market is paying a rich P/E of 93.1x compared with 11.2x for the Australian metals and mining group. That also sits well above a 28.9x fair ratio and a 19x peer average. Is that a margin of safety or a crowd paying up early for Mardie?
These gaps mean even small disappointments in project timing or earnings could hit the share price harder than for lower rated miners, since there is less room for error in the current multiple. For a closer look at how this pricing stacks up against fundamentals across the sector, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BCI Minerals valuation and risk will not resolve themselves, so move quickly, review the data in full and weigh both sides through 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond BCI Minerals?
If BCI Minerals has your attention, do not stop there. A broader watchlist gives you more options when sentiment or pricing shifts quickly.
- Target resilient higher yield by scanning high payout opportunities in the 3 dividend fortresses.
- Hunt for pricing gaps where quality and valuation still look aligned through the 5 high quality undervalued stocks.
- Strengthen your downside protection by concentrating on balance-sheet strength with the list of solid balance sheet and fundamentals (11 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com