


- Cirrus Logic reported a non GAAP gross margin of 52.7% for fiscal Q1 2027, with management guiding GAAP gross margin of 52% to 54% for Q2 as pricing reductions were partially offset by cost cuts and a temporary benefit from lower cost wafers.
- The update highlighted that Cirrus Logic aims to protect its long term gross margin profile by combining cost reductions with selective price increases. Management also acknowledged that supply chain input cost uncertainty still influences how reliably it can hold margins at current levels.
- We will now see how Cirrus Logic's investment narrative is affected by margin guidance that depends in part on temporary wafer cost benefits.
Scan other handset and semiconductor stocks facing similar margin pressure and wafer cost swings with our curated list of list of solid balance sheet and fundamentals (25 results)
Cirrus Logic Investment Narrative Recap
To own Cirrus Logic, you need to be comfortable with a handset centric story that is slowly broadening into PCs and industrial mixed signal, while still tied to a few large customers. The latest gross margin guidance, with a 52% to 54% GAAP range helped by cheaper wafers, points to an operating setup where pricing pressure is real but currently manageable.
In the near term, the key swing factor remains how well Cirrus Logic balances handset pricing resets with higher content and cost cuts. The biggest risk is still customer concentration and timing issues in PCs. A margin outlook that leans on temporary wafer benefits does not fundamentally change that risk profile, but it does keep execution scrutiny high.
The recent commentary on gross margin and wafer costs sits alongside earlier communication around the GlobalFoundries wafer supply agreement. That long dated capacity and pricing framework for 2027 and 2028 already matters for investors watching input cost volatility and the credibility of any margin roadmap.
Seen together, the current quarter benefit from low cost wafers and the multi year GlobalFoundries arrangement frame the same operational question: can Cirrus Logic use secured capacity, a tighter handle on fabrication expenses and mix shift into higher value HPMS products to steady profitability while handset demand, PC adoption timing and pricing remain moving targets for the business?
Based on current analyst work, Cirrus Logic is modeled to reach US$2.2b in revenue and US$298.8m in earnings by 2029. This assumes 3.0% yearly top line growth and an earnings decline of US$131.8m from US$430.6m today.
Uncover why Cirrus Logic's fair value indicates a 38% potential upside to its current price, which could materialize more quickly than many investors expect.
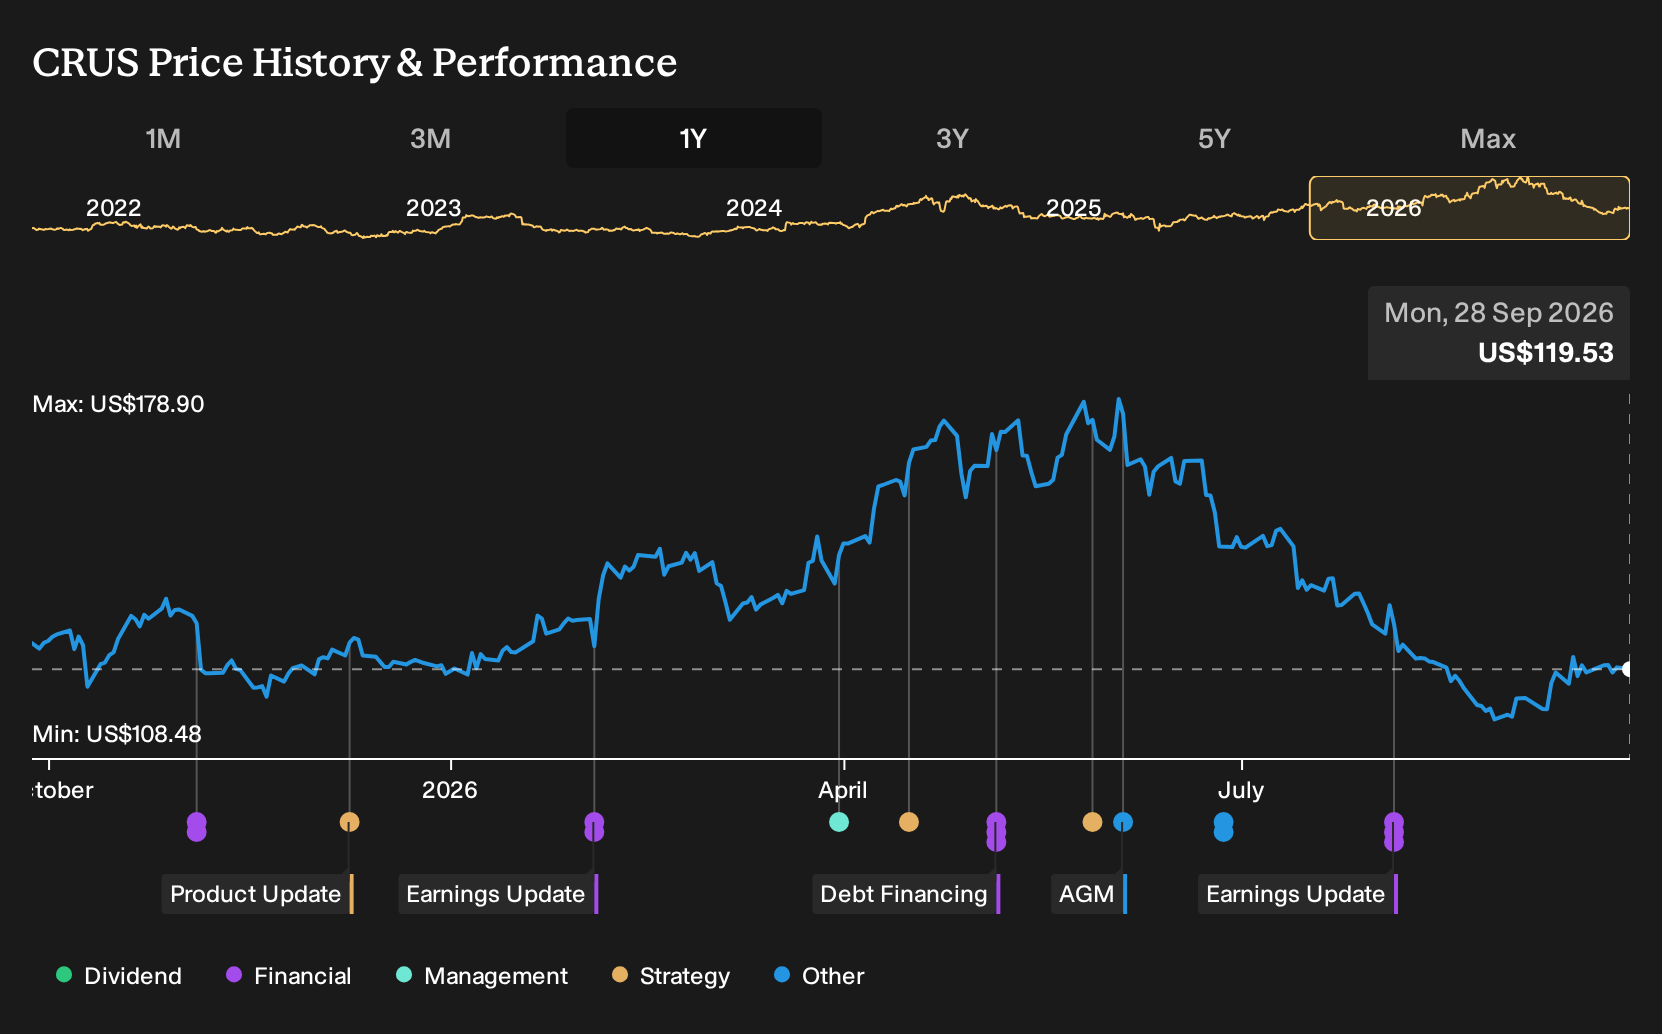
Exploring Other Perspectives
One optimistic twist on Cirrus Logic focuses on AI driven content gains rather than margin risk from cheap wafers. The most bullish analysts were previously modeling about US$2.4b of revenue and US$423.0m of earnings by 2029, well above consensus, so this fresh gross margin update could prompt that upbeat storyline to be revisited.
Explore 7 other Cirrus Logic fair value estimates, including one that suggests as much as 111% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cirrus Logic research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cirrus Logic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cirrus Logic's overall financial health at a glance.
Looking For More Ideas Beyond Cirrus Logic?
If this gross margin story has you reassessing Cirrus Logic, it can help to line it up against other businesses with different balance sheet strength, income profiles and risk levels. The Simply Wall St Screener lets you quickly filter for companies that better match your own tolerance for volatility, cash generation and capital return priorities.
- If resilience and downside protection matter most to you, start with a basket of 30 resilient stocks with low risk scores that have been filtered with a focus on financial robustness and lower risk scores.
- For readers who want quality at a reasonable entry point, scan a curated set of 32 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect those traits.
- Income focused investors can anchor their watchlists with 6 dividend fortresses that pair 5%+ yields with an emphasis on stability and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com