


- Garmin recently rolled out free software and feature updates across key smartwatch lines and Edge cycling computers, and introduced a MYLAPS powered real time in car flagging solution bundled with the Catalyst 2 and accessories for US$1,699.99.
- The push to deepen smartwatch functionality while integrating MYLAPS timing technology into motorsports hardware signals Garmin’s effort to widen its high value performance and safety ecosystem across multiple use cases.
- We will look at how Garmin’s investment narrative is affected by deeper ecosystem features such as fall detection and MYLAPS integration.
Scan how Garmin’s latest training and motorsports upgrades compare with other performance focused hardware stocks using our hand picked 16 high quality undiscovered gems for fresh ideas in this niche.
Garmin Investment Narrative Recap
To own Garmin, you need to believe the business can keep building a broad performance and safety ecosystem around its devices while managing pressure in Outdoor, Auto OEM and component costs. The recent software upgrades in Fitness and motorsports fit that story, but they do not change the fact that Outdoor revenue has been soft and Auto OEM is expected to move back into an operating loss.
The key short term swing factor still sits in Fitness and higher margin services like Garmin Connect+. Execution here matters if Outdoor remains weak and memory costs tied to AI demand start to bite in late 2026 and into 2027. If those cost headwinds prove tougher than expected, net income and valuation support could come under pressure.
The most relevant update for the near term thesis is the free feature rollout across recent Garmin wearables and Edge devices, including fall detection on Venu 4 and expanded training tools on fenix, Forerunner and vívoactive. These upgrades add utility to existing hardware already in users’ hands and can support the push toward higher value health, safety and coaching use cases tied into Garmin’s broader ecosystem.
For investors tracking catalysts, the interest is in how richer device features interact with services like Garmin Connect+ and the TrainingPeaks and TrainHeroic acquisitions. If more capable watches and cycling computers keep users engaged with coaching plans, adaptive workouts and safety functions, that can help reinforce subscription uptake and offset some risks in Outdoor and Auto OEM, while still leaving execution and cost control as central questions.
Garmin's narrative projects US$10.0b revenue and US$2.3b earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of about US$0.4b from US$1.9b today.
Discover why Garmin's fair value appears to be largely consistent with its current price.
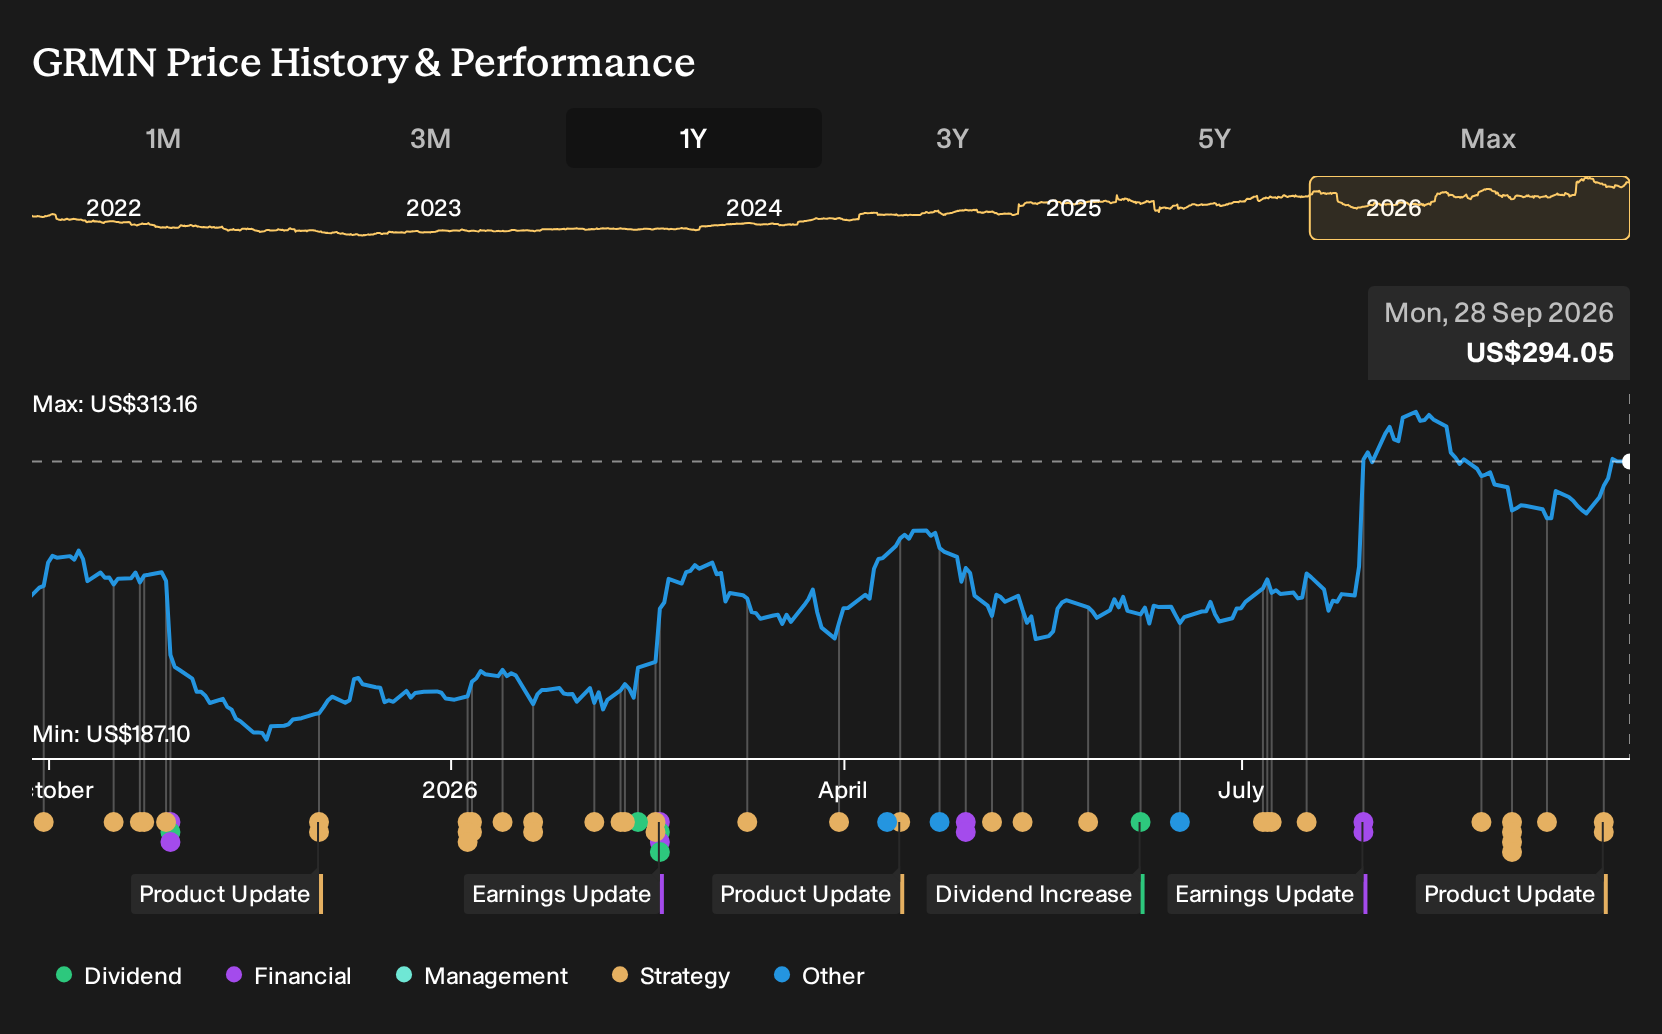
Exploring Other Perspectives
Some of the most optimistic Garmin analysts lean into one catalyst that contrasts sharply with the baseline. They focus on faster ecosystem monetisation from services, with forecasts reaching US$11.1b revenue and US$3.0b earnings by 2029. Those projections were set before these MYLAPS and safety updates, so opinions could shift. Explore the full range of views before deciding what you believe.
Explore 4 other Garmin fair value estimates, including one that suggests as much as 26% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Garmin research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Garmin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Garmin's overall financial health at a glance.
Looking For More Investment Ideas Beyond Garmin?
If the Garmin story has sharpened your thinking about hardware, services and ecosystems, it can help to widen the lens and compare it with other listed companies that share similar financial traits or risk profiles.
- For investors who want potential mispricing with quality financials, start with a curated set of companies using the 32 high quality undervalued stocks to see which ones might deserve a closer look.
- If capital preservation and steadier profiles matter more to you than chasing maximum upside, narrow the field with a focused group of 30 resilient stocks with low risk scores that screen well on resilience metrics.
- When balance sheet strength is non negotiable in your process, filter for healthier financing and fundamentals through the list of solid balance sheet and fundamentals (25 results) and build a shortlist from there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com