


Main Street Capital (MAIN) has drawn attention after recent share price weakness, with the stock down about 6% over the past month and roughly 11% year to date despite positive 3 year and 5 year total returns.
Recent trading has been softer, with the share price down about 2% over the past week and about 6% over the past month. However, Main Street Capital still carries strong longer term total shareholder returns over three and five years, which points to fading short term momentum rather than a broken longer term story at the latest share price of $55.07.
Scan how Main Street Capital compares with other income focused financials by reviewing the hand picked 6 dividend fortresses that combine higher yields with robust fundamentals.
The recent pullback in Main Street Capital has opened a gap between long term returns and current sentiment. Is this a reasonable entry point now, or does patience for a lower price make more sense once valuation is unpacked next?
Most Popular Narrative: 7% Undervalued
On the most followed view, Main Street Capital screens as modestly undervalued, with a fair value of $59.50 against the latest close at $55.07, which puts the current pullback against a backdrop of only a small modeled discount.
The analysts have a consensus price target of $59.5 for Main Street Capital based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $70.0, and the most bearish reporting a price target of just $52.0.
See why 88 investors see Main Street Capital as 7% undervalued.
Result: Fair Value of $59.50 (UNDERVALUED)
Still, a cut to supplemental dividends or rising nonaccruals in consumer facing holdings could quickly challenge the current Main Street Capital valuation narrative.
Find out about the key risks to this Main Street Capital narrative.
Another View On Main Street Capital’s Valuation
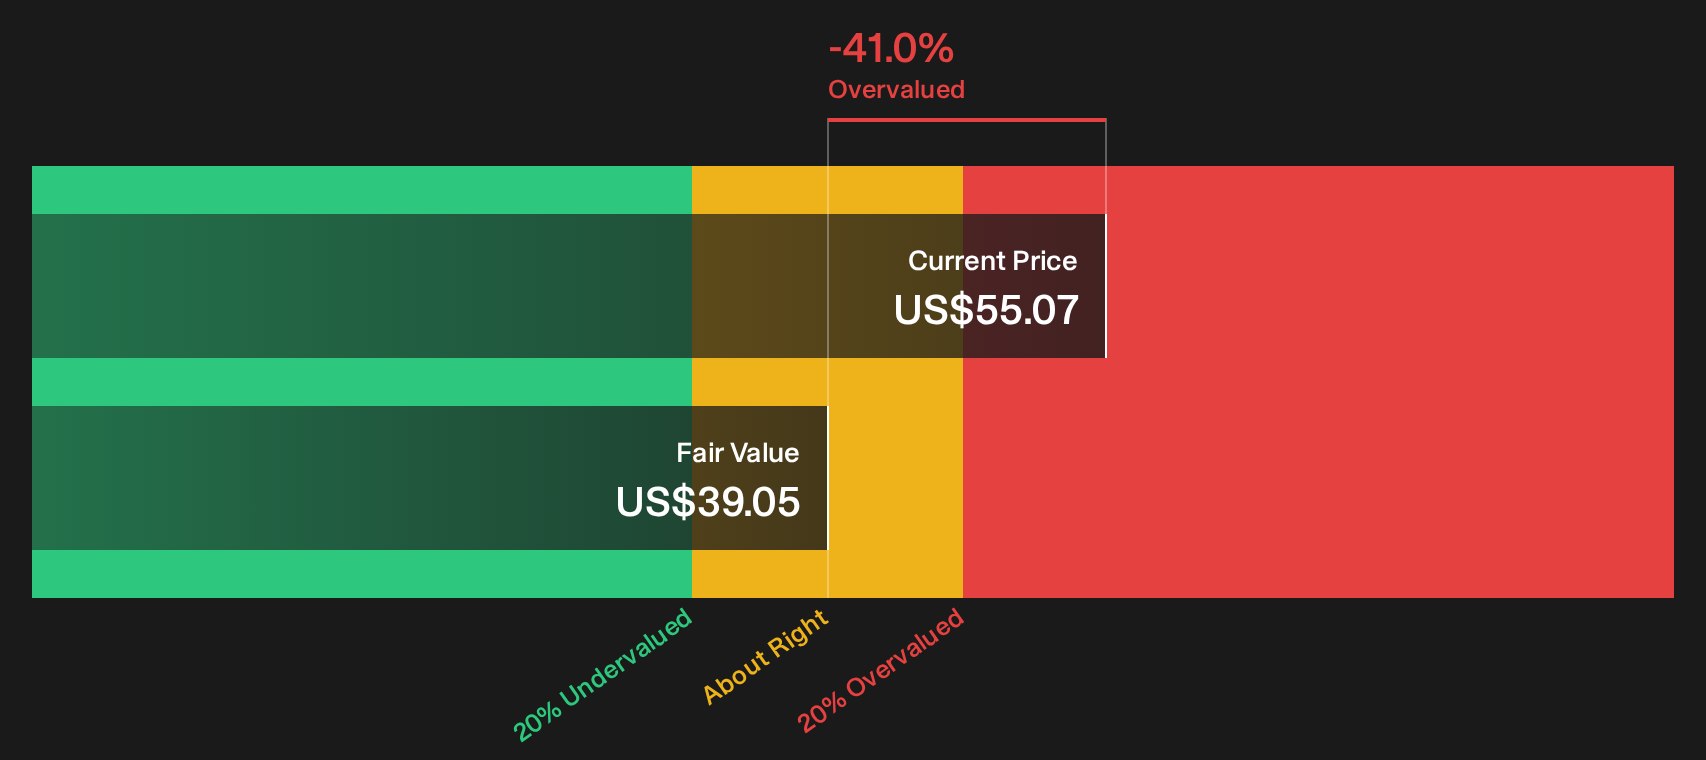
While analyst targets frame Main Street Capital as modestly undervalued around $59.50, the SWS DCF model tells a very different story. On that cash flow view, MAIN at $55.07 trades well above an estimated value of $39.05. This screens as overvalued rather than cheap.
Both approaches use the same business, the same cash flows, and the same dividends. The gap comes from how much weight you give to long term cash generation versus near term earnings and yield. The key question is which lens you consider more useful for MAIN right now.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Main Street Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Main Street Capital’s value and risk profile create real tension, so treat this as a prompt to dig into the numbers yourself and move before sentiment shifts again by weighing the 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond Main Street Capital?
Do not stop your research with Main Street Capital when a wider watchlist could surface opportunities you would otherwise miss across income, quality, and value focused stocks.
- Target dependable cash generators by scanning a curated 6 dividend fortresses that aim to pair higher yields with businesses supported by sturdier financial profiles.
- Hunt for potential value opportunities through the 32 high quality undervalued stocks, where stronger balance sheets and solid cash generation meet prices that screen below intrinsic estimates.
- Spot future leaders early using the 16 high quality undiscovered gems and focus on companies with healthier fundamentals that have not yet attracted broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com