


- Impinj has been refining its M800 and Gen2X platforms, aiming for a richer mix of higher-margin products and broader RFID use cases.
- The push into new categories such as food, high-value apparel, and hard-to-read items signals a bid to widen Impinj's recurring revenue base.
- We will now see how Impinj's M800 and Gen2X expansion may influence the investment narrative around its RFID applications.
Compare Impinj's premium P/S setup with other potential breakouts by scanning our hand picked list of 16 high quality undiscovered gems, which also pair strong fundamentals with underappreciated stories.
Impinj Investment Narrative Recap
To be comfortable holding Impinj, you need to believe in a long runway for RFID adoption across retail, logistics, and newer categories like food and high-value apparel. The recent updates around the M800 and Gen2X platforms point to a business still leaning into richer, higher margin products and wider use cases, which keeps the operating story focused on mix and market breadth.
In the near term, execution on these platforms is the clearest catalyst, because they underpin both gross margin quality and unit demand. The biggest risk remains concentration in a handful of large customers and verticals, which could magnify any slowdown or pricing pressure in higher margin parts of the portfolio.
The most relevant piece of recent news for Impinj is the push to expand M800 and Gen2X into harder categories like food and hard-to-read items while the stock trades close to a widely followed fair value estimate. That combination puts a bright spotlight on how quickly these pilots and early deployments turn into consistent volume.
If these platforms keep gaining share inside existing customers and win new ones, the mix shift toward higher margin endpoint ICs and systems could help offset industry pricing pressure. If adoption in newer markets lags or large buyers pull back, the same product focus could amplify revenue volatility and make the current premium P/S multiple harder for investors to stay comfortable with.
Impinj's narrative projects US$659.4 million revenue and US$85.9 million earnings by 2029. That profile lines up with analysts assuming 21.1% yearly revenue growth and an earnings swing of about US$113 million from a loss of US$27.0 million today.
Uncover why Impinj's fair value is essentially aligned with its current price.
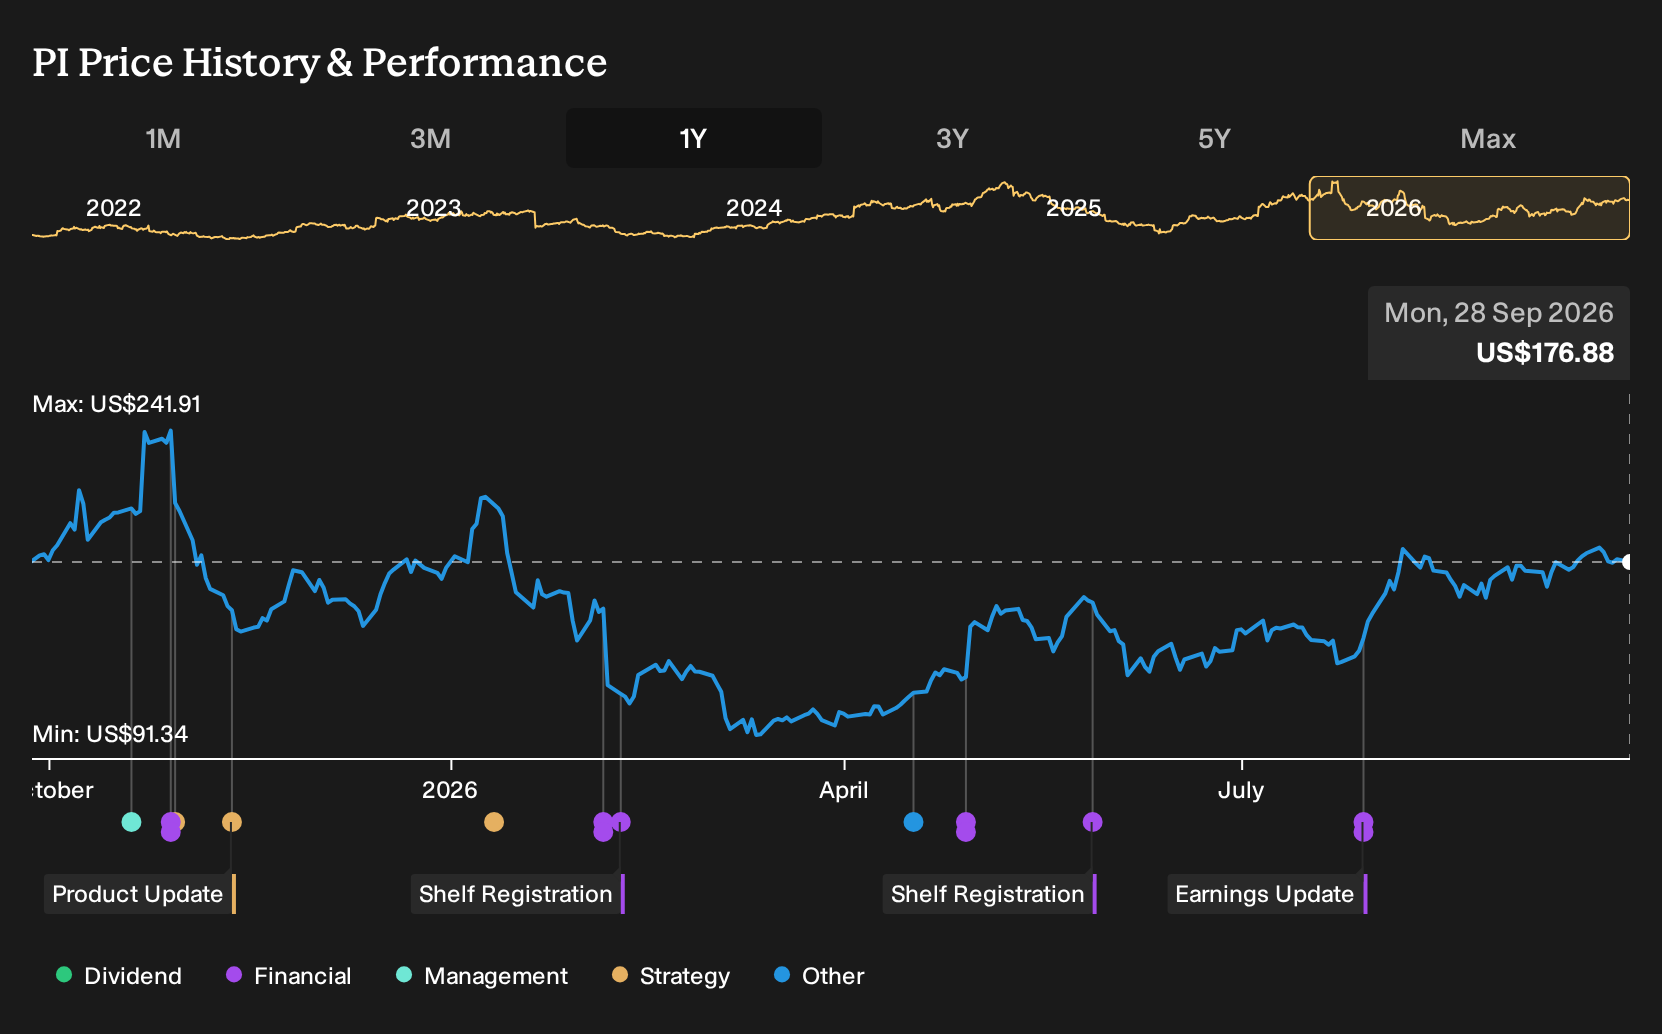
Exploring Other Perspectives
For Impinj, the biggest swing factor in the more optimistic story is margin expansion. The most bullish analysts, before this M800 and Gen2X news, were already penciling in revenue of about US$698.5 million and earnings of roughly US$121.8 million by 2029. That is a far brighter path than the consensus view, so treat it as one of several viewpoints to explore.
Explore 2 other Impinj fair value estimates, including one estimate that values it at up to $180.89.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Impinj research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Impinj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Impinj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Impinj?
Once you have a view on Impinj, it can help to put that thesis in context by scanning other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If you want potential income to play a bigger role in your portfolio, check out a set of higher yielding payers in the 6 dividend fortresses.
- For investors who care most about resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results).
- If capital preservation sits at the top of your priority list, focus on companies screened for stability and lower risk using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com