


- Galp Energia SGPS recently completed a hearing at the Maputo City Tax Court on its appeal against a €151.5 million capital gains tax related to the past sale of a gas stake in Mozambique, while a parallel international arbitration case remains open.
- The dispute highlights how tax treatment on past portfolio reshaping can influence Galp Energia SGPS's cash outflows, its capital allocation flexibility, and its capacity to fund projects across upstream, refining, gas, and renewables.
- We will now explore how Galp's contested €151.5 million Mozambique tax claim could reshape the investment narrative that investors use to judge it.
Compare how Galp Energia SGPS stacks up on project funding flexibility by scanning a hand-picked list of solid balance sheet and fundamentals (204 results) that may better withstand unexpected tax or regulatory shocks.
Galp Energia SGPS Investment Narrative Recap
To own Galp Energia SGPS, you need to believe that its integrated model can keep turning large upstream investments, refining operations, and renewables into steady cash flow even as energy markets and regulation stay unpredictable. The Mozambique tax dispute mainly affects the timing of cash and perceived fiscal risk, not the core projects that currently shape the near term story.
Right now, the key short term swing factors remain execution on major upstream projects such as Bacalhau, the big refinery turnaround, and returns from renewables where power prices matter a lot. The tax case adds another potential cash outflow and some noise around portfolio reshaping, but on its own it does not rewrite the main operational risk and catalyst list.
Among recent developments tied most closely to this news is Galp Energia SGPS's continued portfolio reshaping in upstream, including changes to interests such as Tupi and assets in Mozambique and Brazil. The Mozambique tax hearing sits directly on top of that broader clean up of legacy positions and contract terms that already carry fiscal and regulatory risk.
The arbitration and court process in Mozambique connects to a wider question you need to weigh: how much headroom does Galp have to fund Bacalhau, Mopane, refinery work and renewables if extra tax or contract adjustments crystallise? That is where this case interacts with existing catalysts and risks around future earnings, free cash flow resilience, and balance sheet flexibility.
Galp Energia SGPS' narrative points to forecast revenues of €22.8b and earnings of €1.1b by 2029. This aligns with analysts assuming 2.0% yearly revenue growth and flat earnings compared with current earnings of €1.1b.
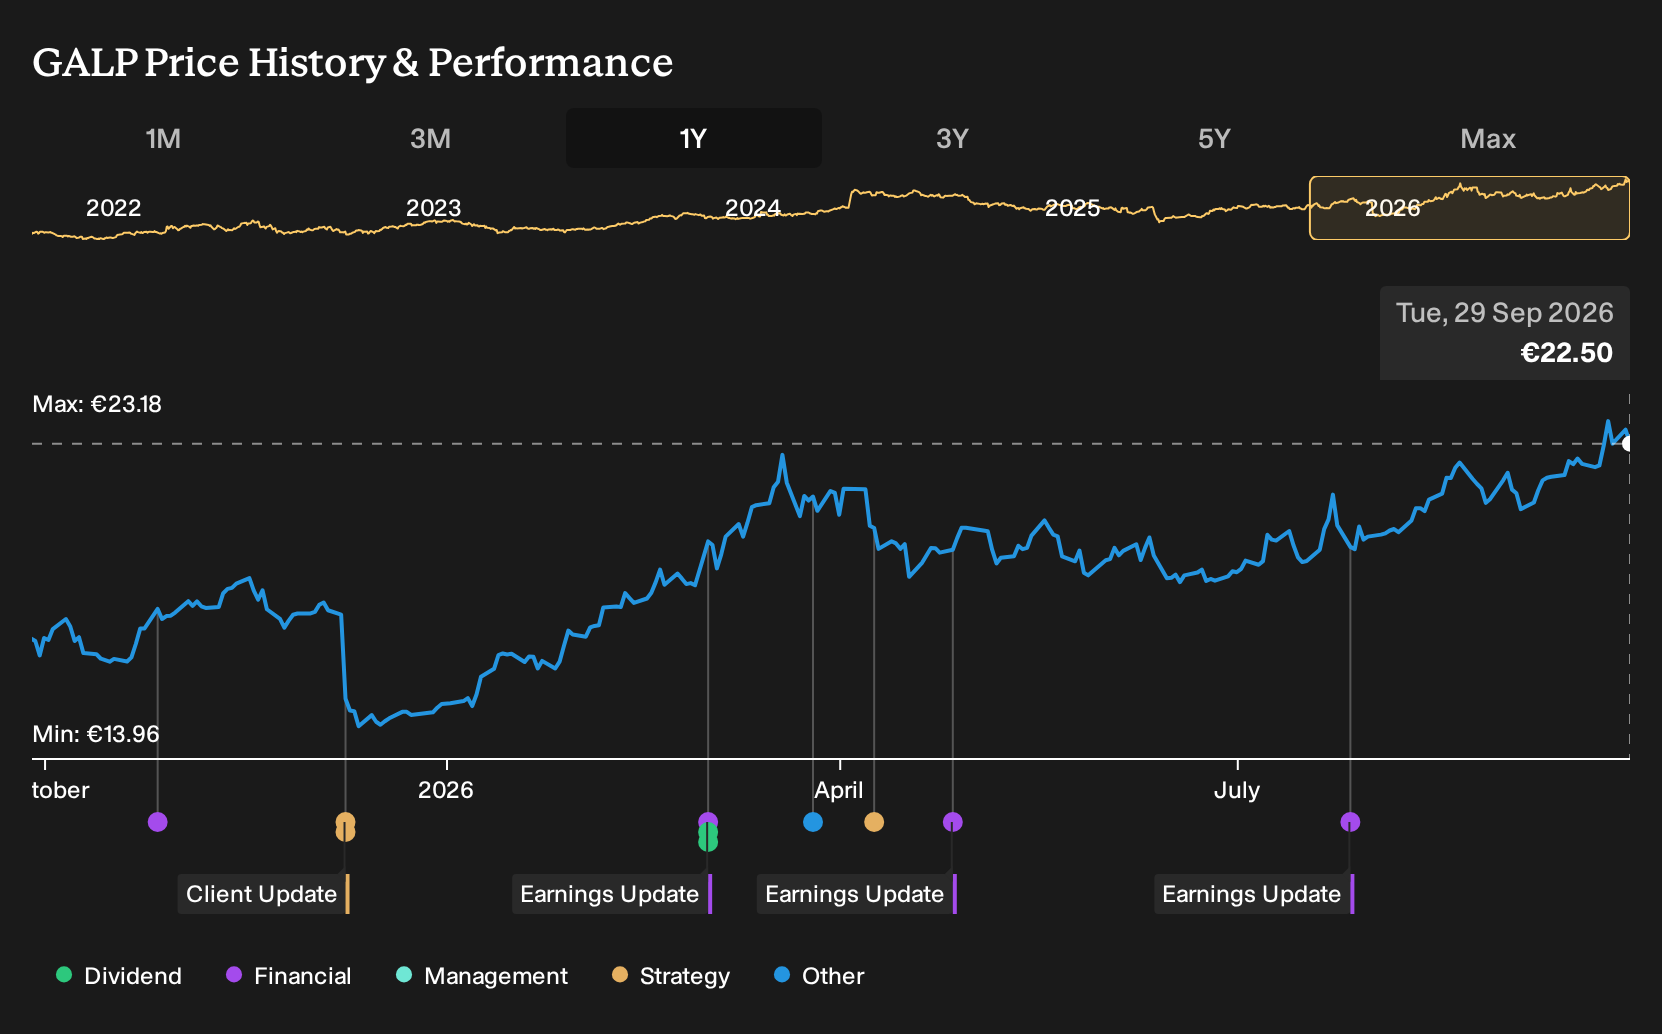
Uncover how Galp Energia SGPS' fair value indicates a 3% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
You might see this Mozambique tax dispute very differently if you focus on one alternate risk. The most pessimistic analysts already expected Galp Energia SGPS revenues to fall toward about €15.7b by 2029, with earnings stuck near €1.1b. Those views came before this case, so you should expect some of those narratives to shift and explore several viewpoints yourself.
Explore 4 other Galp Energia SGPS fair value estimates, including one that suggests as much as 26% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Galp Energia SGPS research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Galp Energia SGPS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Galp Energia SGPS' overall financial health at a glance.
Looking for more Galp Energia SGPS style investment ideas?
If the Galp Energia SGPS story raised fresh questions about risk, balance sheets, and cash flow resilience, it can help to line it up against other businesses facing very different pressures. Use the Simply Wall St Screener to spot companies that fit the kind of profile you want to back before the next tax ruling, project delay, or funding squeeze hits the headlines.
- If capital preservation sits high on your list, start with a set of companies screened for resilience and lower risk profiles through the 225 resilient stocks with low risk scores.
- For investors hunting for mispriced quality rather than headlines, scan a focused group of potential bargains using the 202 high quality undervalued stocks.
- If you prefer businesses that quietly compound away from the spotlight, broaden your watchlist with a curated 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com