


Why VEON’s New Bangladesh Banking License Matters For Investors
VEON (NasdaqGS:VEON) has just secured regulatory approval for a digital bank in Bangladesh through a joint venture with Square Group, tying that license directly to its Invest in Bangladesh NOW public private initiative.
VEON’s Bangladesh banking approval lands on top of an active year, with the share price up 14.09% over the past month and 32.94% over 90 days. At the same time, three recent developments in Bangladesh and Kazakhstan hint at investors reassessing both growth potential and execution risk. Despite a 1-day share price decline of 5.59% to US$69.41, the broader picture is one of building momentum, with a year to date share price return of 31.71% and a three year total shareholder return of more than 3x that period’s starting value.
Scan other telecom and fintech plays showing similar digital banking momentum by reviewing the hand picked 16 high quality undiscovered gems that share some of VEON’s expanding financial services profile.
VEON has moved quickly from telecom operator to licensed digital bank partner in Bangladesh, and the share price has already responded. Is that momentum worth paying up for now, or does patience offer a better entry?
Most Popular Narrative: 17% Undervalued
On the most followed view of VEON, a fair value of $83.44 sits well above the last close at $69.41. This puts this new Bangladesh banking license into a bigger story about digital expansion, balance sheet risk, and what investors are paying for future cash flows.
VEON is aggressively expanding digital service offerings (including fintech, super apps, ride-hailing, entertainment, and AI-driven products) in emerging markets that are rapidly digitalizing and seeing surging demand for mobile internet and data. This positions the company to pursue ongoing subscriber growth and ARPU uplift, which in turn supports future revenue and EBITDA.
See why 9 investors see VEON as 17% undervalued.
Result: Fair Value of $83.44 (UNDERVALUED)
Still, VEON’s story can change quickly if currency swings in Pakistan or Ukraine hit reported earnings, or if high gross debt near US$4.63b reduces its financial flexibility.
Find out about the key risks to this VEON narrative.
Another View: VEON Looks Expensive On Simple Earnings Math
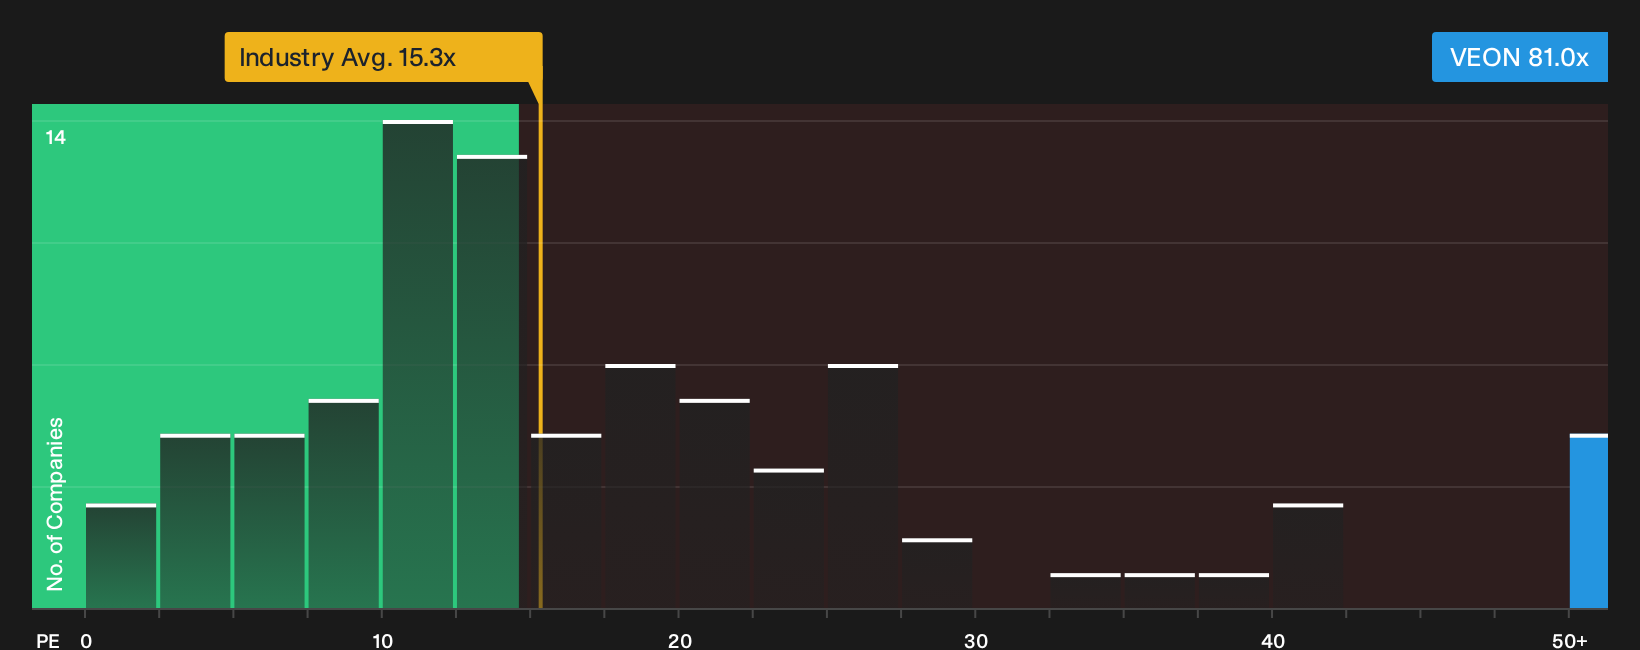
VEON may screen as undervalued on fair value estimates near $83, but the basic P/E story is very different. At about 81x earnings versus 13.5x for peers, and a fair ratio of 27.1x, the gap points to real valuation risk if sentiment cools.
That kind of premium pricing raises a practical question. Is the digital banking pivot and wider AI1440 plan strong enough for you to stay comfortable paying far more than both the sector and the fair ratio suggest the market could move towards next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on VEON after weighing both the digital push and the valuation risk questions. Act quickly, pull up the full picture, and pressure test the upside and downside using our breakdown of 3 key rewards and 3 important warning signs.
Looking For More Ideas Beyond VEON?
If VEON has you thinking differently about risk, returns, and timing, do not stop here. Use the screener to surface other opportunities before the crowd moves.
- Target resilient payers by scanning for income opportunities among 6 dividend fortresses that aim to combine higher yields with staying power.
- Spot quality at a discount by reviewing 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- Prioritize resilience first by focusing on 30 resilient stocks with low risk scores that keep balance sheet and risk scores front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com