


Arm Holdings has delivered very strong long term returns, and with AI demand pulling the wider chip sector into focus, the question for investors now is whether a share price around US$283 is still grounded in the company’s book value.
- Arm’s stock has returned roughly 4.4x over the past 3 years, which puts a lot of pressure on today’s valuation to be supported by the balance sheet rather than just recent momentum.
- Management’s push into AI focused CPUs and the goal of higher revenue from data center chips can support expectations for stronger profitability, which may change how much weight investors put on book value in their analysis.
- Your read on Arm Holdings is one view; the desks covering it have another. See what analysts think Arm Holdings's shares could be worth.
The issue now is whether the current market price for Arm Holdings is adequately backed by its book value when set against the industry average.
For a sense check on how Arm’s AI fueled valuation compares with other chip related opportunities, it can help to line it up against 88 AI infrastructure stocks.
Has Arm Holdings Run Too Far on Book Value?
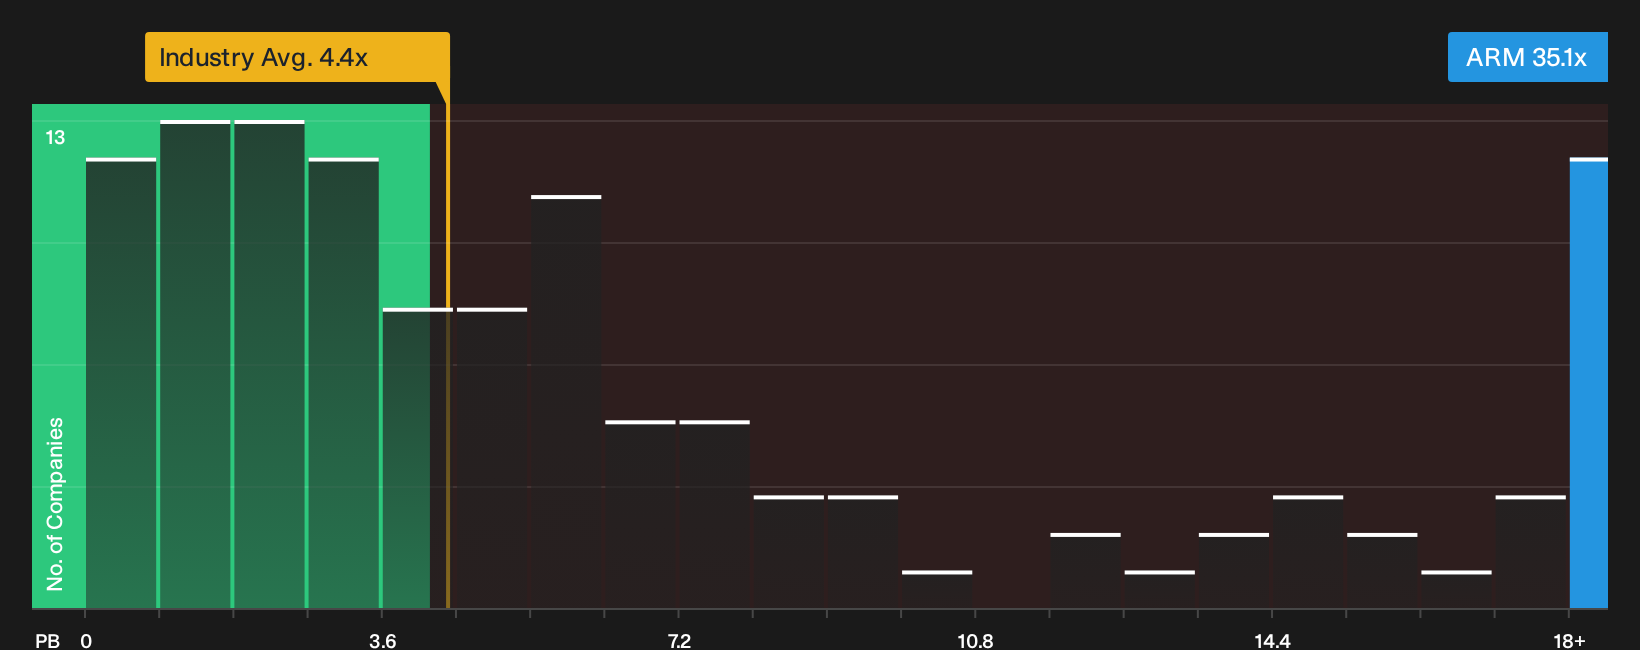
P/B is a useful lens for Arm Holdings because the group’s value is still closely tied to the strength of its intellectual property and balance sheet. On this metric, the stock trades at about 35.1x book value, which is far above the semiconductor industry average of roughly 4.4x and a peer group closer to 9.7x. That gap means investors are paying a large premium over the equity capital already in the business.
Recent excitement around AI chips, including the CEO’s confidence in Arm’s AGI CPU revenue ambitions, helps explain why traders are willing to stretch the multiple this far. Even with that backdrop, a P/B near 35x implies the market is already assigning substantial value to future licensing, data center and AI opportunities relative to the current balance sheet. For anyone considering the stock, the key question is whether Arm’s competitive position and earnings power can justify such a rich premium to sector norms. Explore the numbers behind Arm Holdings's P/B valuation.
The Arm Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Arm Holdings pick up where the P/B debate leaves off. They spell out the specific growth, margin and earnings paths that would need to hold for Arm Holdings' share price to sit well above or well below where it trades today. Each narrative treats fair value as a thesis about the business that can be revisited over time rather than a one-off snapshot, all hosted on the Community page.
Community narratives on Arm Holdings split sharply, with one group seeing a premium-quality AI platform and another arguing the current enthusiasm looks like a bubble phase.
Bull case: 34% undervalued
"Arm may be one of the most strategically important companies in computing, but the stock already assumes a very large part of that future…"
Discover why this Narrative puts Arm Holdings at 34% undervalued.
Bear case: 305% overvalued
"With ARM now trading in the $120 to $140 range, its implied earnings yield has fallen below that of the 10-year Treasury…"
Explore why this Narrative puts Arm Holdings at 305% overvalued.
Arm Holdings: why the share price is only one piece of the puzzle
Arm Holdings does not just raise questions about what investors are willing to pay today. Internal checks have also flagged specific risks that deserve attention before any decision is made. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com