


- Canfor has acquired PinkWood, expanding beyond core lumber, pulp, and paper into engineered wood products that sit higher up the value chain.
- The move gives Canfor more exposure to value added wood building systems, which can change how its revenue mix responds to commodity price swings.
- This article examines how Canfor's investment narrative is shaped by the PinkWood acquisition and the push toward higher value products.
Scan for other wood and building products stocks tilting toward higher value products and potentially steadier cash flows with the hand picked list of solid balance sheet and fundamentals (7 results)
Canfor Investment Narrative Recap
To own Canfor, you need to be comfortable with a cyclical lumber and pulp operator that is trying to lean more on higher value products while still being loss making today. The near term story hinges on whether mill upgrades and asset closures translate into a lower cost base and more resilient earnings through future cycles.
The big short term swing factor is how well the business manages fiber availability, transportation constraints, and lumber trade duties while ramping its more efficient mills. The key risk is that structural pressure in pulp markets and regional wood supply challenges keep costs elevated, which would limit the benefit of any mix shift toward premium products.
The PinkWood acquisition is the clearest recent example of where Canfor is trying to go. It extends the group into engineered wood building systems that generally rely less on pure commodity pricing and more on product specifications, customer relationships, and technical performance in the field.
From a catalyst perspective, progress in engineered wood can gradually rebalance exposure away from the more volatile lumber and market pulp segments. Execution risk remains in the background. Integration of PinkWood, delivery of the Bruza and Iron Mountain upgrades, and smooth closure of higher cost sites all need to align for any mix benefits to show through in revenue quality and cash generation.
Canfor's narrative projects CA$6.5b revenue and CA$742.4 million earnings by 2029. This assumes 6.2% yearly revenue growth and an earnings increase of about CA$1.4b, from a loss of CA$653.5 million today.
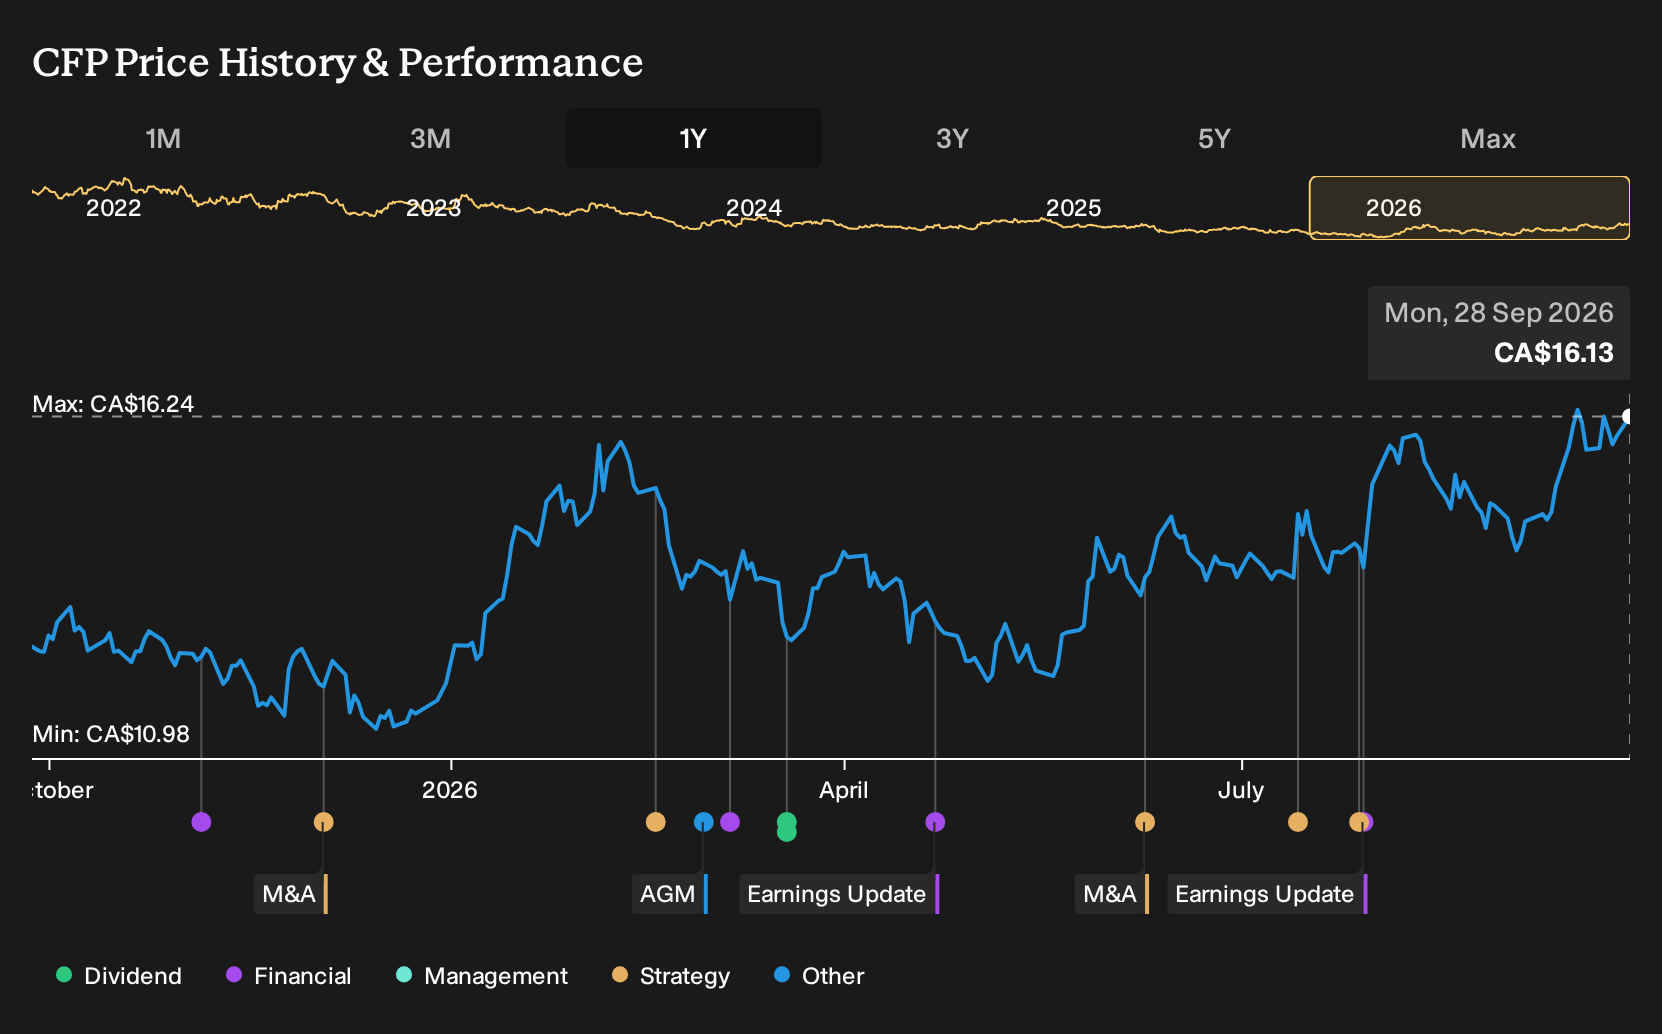
Uncover why Canfor's fair value indicates a 10% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly CA$18 to CA$148 per share, which shows how far opinions on Canfor can spread. Those views do not yet factor in the PinkWood deal, mill closures or upgrades. Use that gap, and the execution and pulp price risks, to test your own stance.
Explore 2 other Canfor fair value estimates, including one that suggests it could be worth just CA$17.71.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Canfor research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Canfor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canfor's overall financial health at a glance.
Looking For More Ideas Beyond Canfor?
If the Canfor story has sharpened your thinking about cycles, cash flows, and business quality, use that same lens to broaden your watchlist with other opportunities that fit your own risk and return preferences.
- For investors hunting for overlooked opportunities with room to prove themselves, scan through 9 high quality undiscovered gems that pair strong fundamentals with lower market attention.
- If capital preservation matters just as much as upside, filter for 8 resilient stocks with low risk scores that carry more resilient profiles according to their risk scores.
- Income focused readers can narrow in on 1 dividend fortresses that combine higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com