


Fresh research comparing Enbridge (TSX:ENB) with Ultrapar Participacoes S.A. has put valuation back in focus for investors watching the Canadian pipeline and utilities group.
The study highlights Ultrapar’s stronger earnings estimate revisions and more favourable value metrics, including forward P/E and PEG ratios, relative to Enbridge, which carries a Zacks Rank of #3 (Hold).
For context, Enbridge shares trade at CA$66.58, with the 90 day share price return down 13.43%. However, the 3 year total shareholder return of 83.43% and 5 year total shareholder return of 79.65% indicate investors have been rewarded over longer holding periods.
Compare Enbridge with a curated group of income-focused infrastructure peers by scanning the 1 dividend fortresses that have kept payouts front and center.
The recent pullback in Enbridge has handed income investors a potential entry point, while others prefer to wait for a deeper reset. How does the current valuation compare with the earnings and cash flows available today?
Most Popular Narrative: 17% Undervalued
Compared with Enbridge’s last close at CA$66.58, the most followed narrative pegs fair value at CA$80.14 using a 6.47% discount rate. This points to a sizeable valuation gap that rests on the durability of its infrastructure cash flows and project pipeline.
Enbridge is well-positioned to capture increasing North American energy demand, driven by sustained utilization of its pipeline and midstream assets for crude oil, LNG, and natural gas, with long-term contracts and regulatory mechanisms ensuring recurring, inflation-protected revenue and resilient net margins.
See why 280 investors see Enbridge as 17% undervalued.
Result: Fair Value of CA$80.14 (UNDERVALUED)
Still, Enbridge’s narrative can be knocked off course if regulatory delays on key projects drag on, or if decarbonization policies reduce long term pipeline utilization.
Find out about the key risks to this Enbridge narrative.
Another View On Enbridge’s Valuation
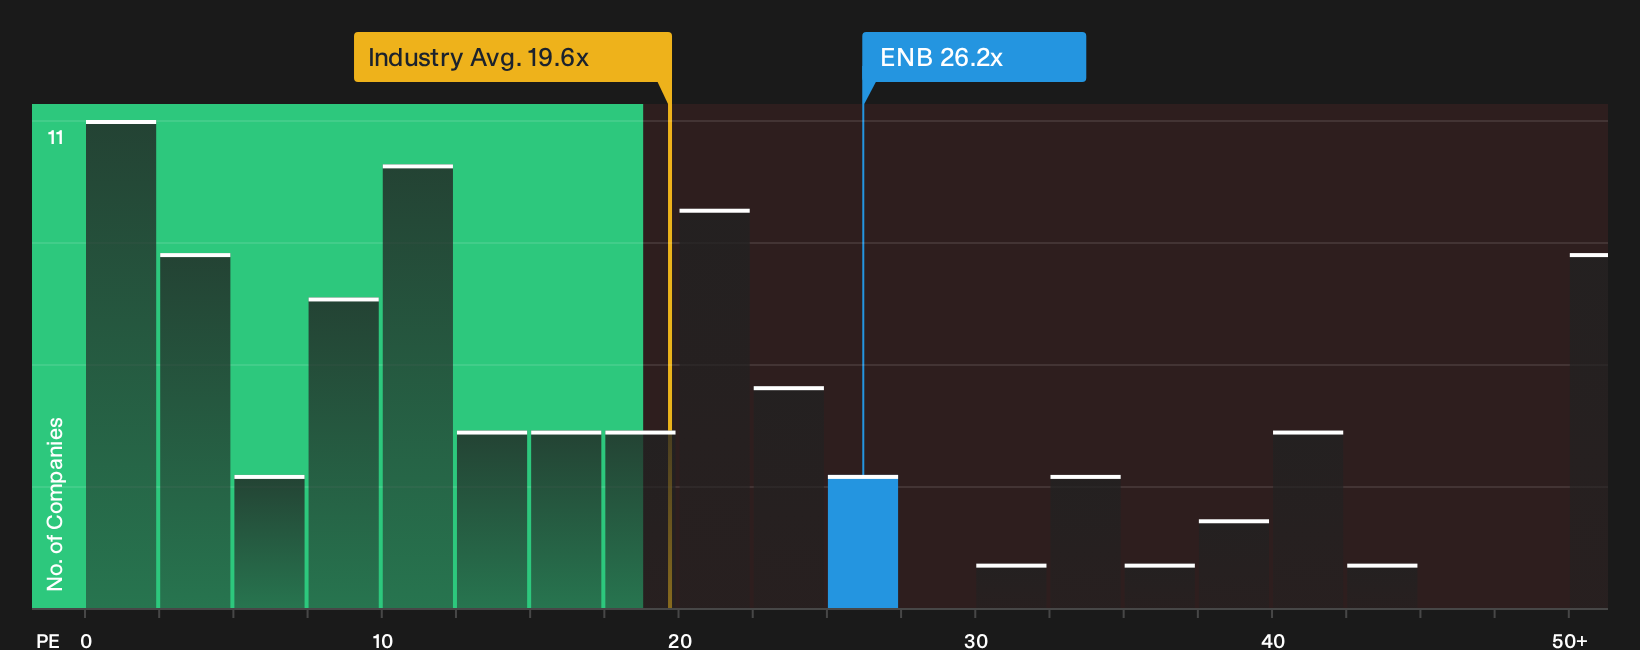
Those analyst fair value models paint Enbridge as 17% undervalued, yet the current P/E of 26.2x sits above both the Canadian Oil and Gas industry at 19.6x and the peer average at 25.9x, and even above its own 25.6x fair ratio. Could the share price be leaning into valuation risk rather than opportunity?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Enbridge’s valuation can pull you in different directions, so weigh the data yourself and move quickly to shape your own view using the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Enbridge?
If Enbridge has you thinking harder about price and quality, do not stop here. The strongest portfolios are built by comparing multiple opportunities side by side.
- Target resilient income by scanning the 1 dividend fortresses that aim to keep cash coming in even when sentiment cools.
- Hunt for quality at a discount with the 7 high quality undervalued stocks that match solid fundamentals with prices that have not caught up.
- Spot tomorrow’s potential leaders early through the 9 high quality undiscovered gems before the crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com