


Lincoln National has delivered a powerful share price run over the past few years, which puts fresh focus on what investors are really paying for its earnings today. With the stock now trading around its recent level of US$40.88, the key issue is whether that price still lines up with what the business is generating in profit.
- Over the past 3 years, Lincoln National has returned about 99.4%, which puts a lot of weight on whether its current earnings can support that kind of move.
- The insurer’s valuation now leans heavily on the durability of its underwriting results, fee income and investment returns, because those cash flows shape how much profit can reasonably be attached to each share.
- The analysts covering Lincoln National have run their own numbers. See what analysts think Lincoln National's shares could be worth.
For investors, the debate is whether Lincoln National’s current share price is properly aligned with what its earnings justify on today’s numbers.
If you want to test the same "are earnings justifying the price" question beyond Lincoln National, you can scan a wider field using 32 high quality undervalued stocks.
Is Lincoln National Still Cheap on Earnings?
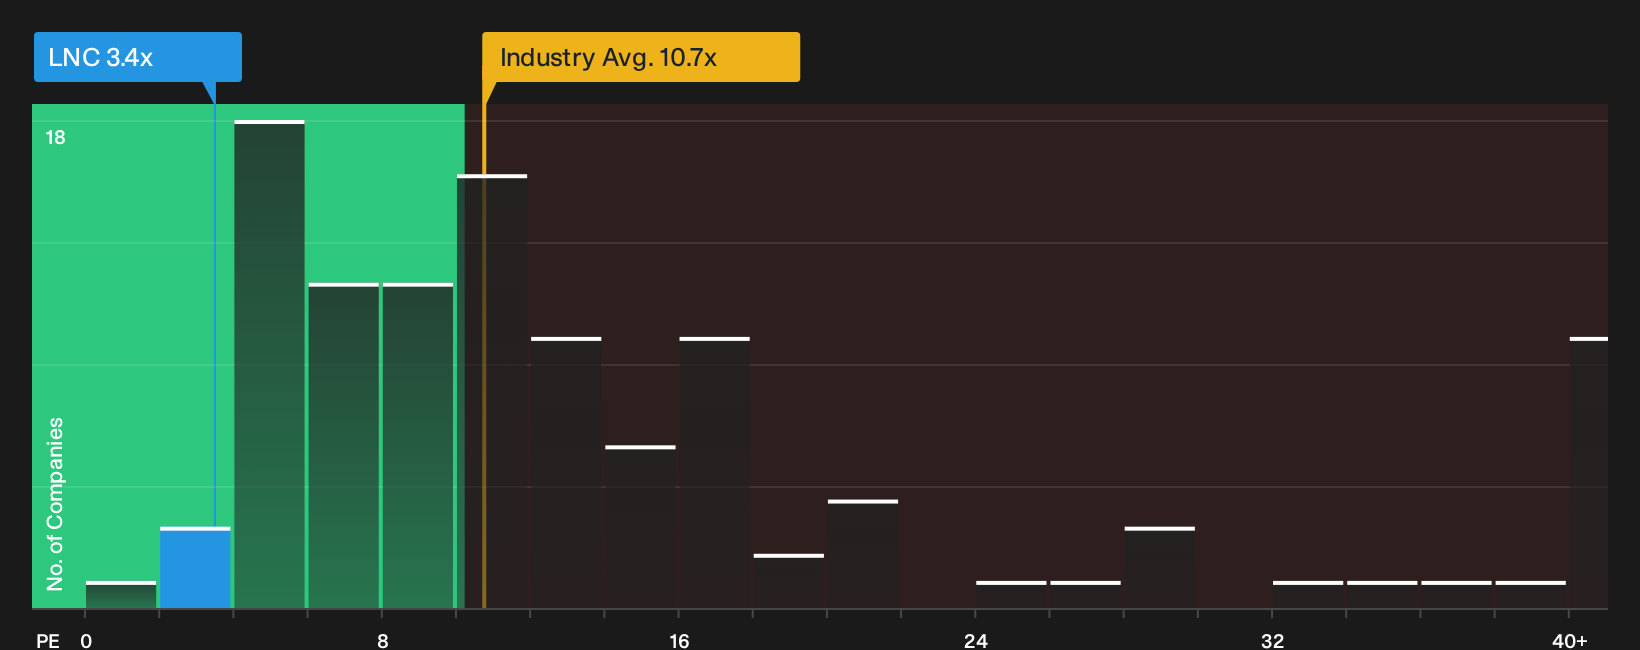
The P/E ratio suits Lincoln National because earnings remain the main anchor for how investors value an insurer with sizeable investment income and underwriting results. On that yardstick, the stock trades on roughly 3.4x earnings, while the broader Insurance industry average is about 10.7x and the peer group screens near 13.9x.
The valuation model suggests that, given Lincoln National’s forecast return on equity, book value profile and risk characteristics, a higher P/E would typically be associated with a business with these traits. That leaves the current multiple well below what the tailored fair value framework implies for this ticker. Explore the numbers behind Lincoln National's P/E valuation.
The Lincoln National Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle for Lincoln National leaves off by spelling out what mix of future earnings, growth and profitability would need to play out for the shares to be worth meaningfully more or less than the current price, and they sit on the stock’s Community page.
Rather than relying on a single multiple or one model result, each scenario lays out the assumptions behind its estimate of value so you can compare those expectations with Lincoln National's actual results as they are reported.
Lincoln National inspires two very different stories, depending on whether you focus on balance sheet cleanup or the cost of getting there.
Bull case: 32% undervalued
"The plan to resume common share repurchases under a US$1.5b authorization and to tender for up to US$500 million of preferred shares..."
Discover why this Narrative puts Lincoln National at 32% undervalued.
Bear case: 14% overvalued
"Operational investments in technology and talent, while necessary, could lead to higher near-term expenses, thereby compressing net margins before they generate expected increases in free cash flow..."
Explore why this Narrative puts Lincoln National at 14% overvalued.
One more Lincoln National check that belongs beside the earnings multiple
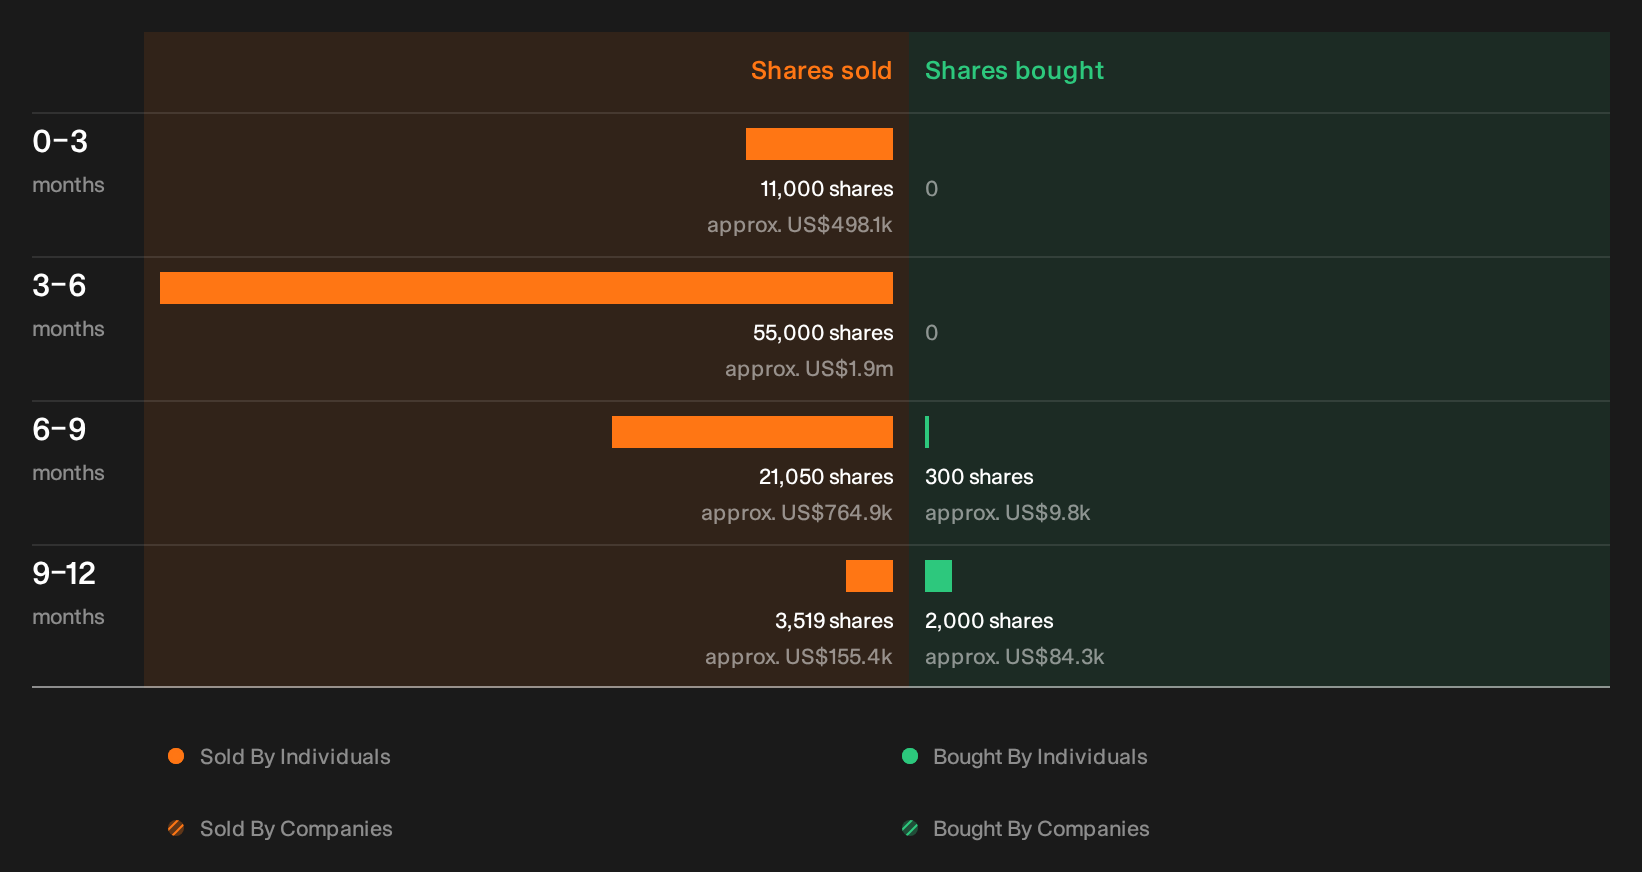
Valuation only tells part of the story for Lincoln National, because recent activity in the boardroom and executive suite may offer extra context that price ratios cannot show on their own. See the recent insider selling flagged for Lincoln National.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com