


Radian Group has delivered a solid 67.4% share price gain over the past 5 years, yet the stock has slipped in recent months, which naturally puts the focus on whether its current valuation is still supported by its earnings power. With the price now around US$33, the key issue for investors is how that track record lines up with what the business is actually earning today.
- Radian Group shares are up 67.4% over 5 years, so a lot now depends on whether the recent price reflects a sustainable earnings profile rather than past momentum.
- The mortgage insurance model leans heavily on underwriting discipline, credit quality and capital efficiency. These factors can all shape how consistently the company converts its book of business into earnings that justify today's P/E multiple.
- The analysts covering Radian Group have run their own numbers. See what analysts think Radian Group's shares could be worth.
The stock's next move may depend on whether the current price is adequately supported by Radian Group's earnings when set against the Fair Ratio benchmark.
If you want to examine the same earnings question you are asking of Radian Group across a broader set of companies, compare it with 32 high quality undervalued stocks.
Is Radian Group a Bargain on Earnings?
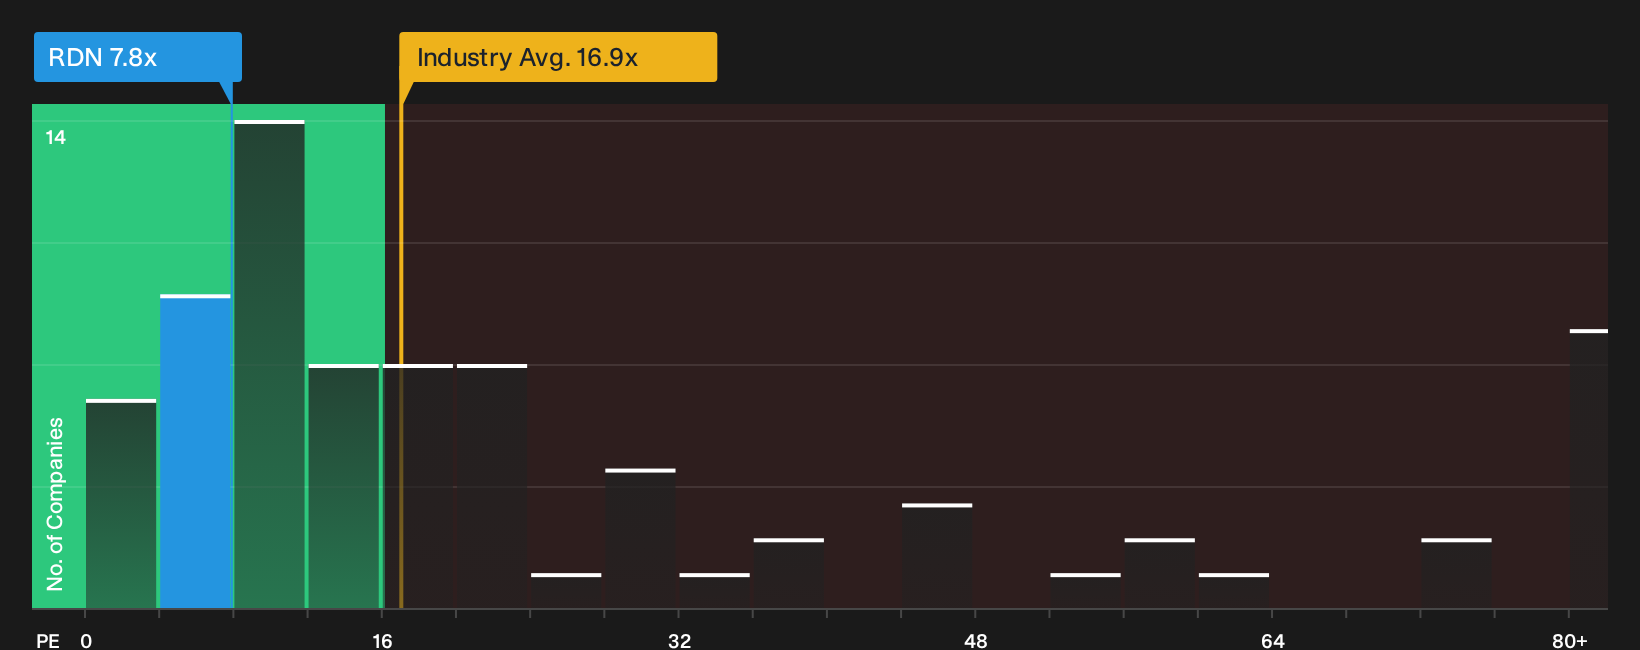
The P/E ratio suits Radian Group because earnings remain the main way equity investors get paid here. On that yardstick, the stock trades on roughly 7.8x earnings, which is below the diversified financials sector average of about 16.9x and also under the peer group at around 8.5x. For a reader, that signals the market is paying less per dollar of Radian Group earnings than it is for many similar businesses.
The Fair Ratio model, which adjusts the benchmark multiple for factors like profitability, balance sheet strength and risk, points to a higher figure than where the shares trade today. That puts the current P/E at a discount to what this framework would expect for Radian Group, so the market is not pricing the stock as fully as those inputs alone might suggest. The key question is whether you believe the company can keep converting its mortgage insurance book into earnings that support that kind of valuation gap. Explore the numbers behind Radian Group's P/E valuation.
The Radian Group Narrative: What Would Justify Today's Price?
Narratives pick up where that P/E puzzle leaves off for Radian Group by spelling out which paths for revenue growth, profitability and earnings would need to hold for the stock to be worth materially above or below today's share price, and by framing each possible outcome as a thesis about Radian Group's business that you can revisit over time as new information comes through. They live on Simply Wall St's Community page and aim to keep the valuation debate linked to concrete business assumptions rather than one-off numbers.
A written, number driven view on Radian Group gives you a concrete yardstick for where its growth, margins and execution would need to land for today's P/E discount to look justified or stretched. It also creates a clear set of assumptions you can revisit as future results, credit trends and underwriting outcomes either support or challenge that initial read on the business.
Share your own Narrative for Radian Group and set out the assumptions behind your valuation.
Before acting on Radian Group's valuation, there is one more factor to weigh
Price and earnings only tell part of the story for Radian Group, because the people making capital decisions and how they are rewarded can strongly influence how those numbers evolve over time. See who runs Radian Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com