


Why Cintas stock is back in focus after fresh earnings
Cintas (CTAS) moved into the spotlight after reporting first quarter results that showed higher sales, revenue, and net income compared with a year earlier, while also tightening and lifting its full year 2027 revenue outlook.
Investor interest in Cintas has been building for a while, with the stock delivering a 90 day share price return of 17.93% and an 8.49% share price gain year to date. This comes even as the 1 year total shareholder return is slightly down 0.64%, while multi year total returns of 69.88% over three years and 117.73% over five years point to a much stronger longer term story.
The latest move comes as the market reacts to first quarter numbers, a tighter full year 2027 revenue range of about US$12.15b to US$12.27b, and ongoing share repurchases. Cintas last closed at US$200.58, which suggests investors are weighing fresh growth signals against how much of that progress is already reflected in the price.
Scan how Cintas stacks up against other high quality operators by reviewing our hand picked 16 high quality undiscovered gems that have strong fundamentals but remain under the radar with many investors.
Cintas now trades near fresh highs on stronger guidance, which leaves investors weighing a little more upside against the risk that most of the good news is already in the price.
Most Popular Narrative: 9.5% Overvalued
Cintas closed at $200.58, while the most followed narrative on the stock, according to LunaRodas, pegs fair value at $183.22, which implies the recent rally has run ahead of that assessment and puts management’s own guidance under a brighter spotlight.
“By the transcript’s own figures, the arithmetic does close, and it closes higher than the old range implied. Fiscal 2026 ended at about $11.26 billion of revenue and a 23.3% adjusted operating margin. Incrementals of 32% to 34% on the middle and top of the new revenue range produce a margin near 24.0% to 24.2%, roughly 70 to 90 basis points of expansion, our arithmetic, not management’s. The previous guide implied expansion of 10 basis points at the low end and 60 at the high end.”
See why 2 investors see Cintas as 9% overvalued.
Result: Fair Value of $183.22 (OVERVALUED)
Still, the Cintas story could shift quickly if energy costs bite harder than management expects or if the UniFirst deal timeline and terms change materially.
Find out about the key risks to this Cintas narrative.
Another View on Cintas: Cash Flows vs Earnings Multiple
The LunaRodas narrative leans on an earnings based fair value of $183.22 and tags Cintas as 9.5% overvalued. The SWS DCF model lands in a different place. On projected cash flows it points to a value of $210.85, which leaves the current $200.58 price about 5% below that estimate.
The gap between an earnings driven fair value and a cash flow based one leaves investors with a simple question: Which set of assumptions feels closer to how Cintas will actually convert its revenue and margins into long term cash generation?
Look into how the SWS DCF model arrives at its fair value.
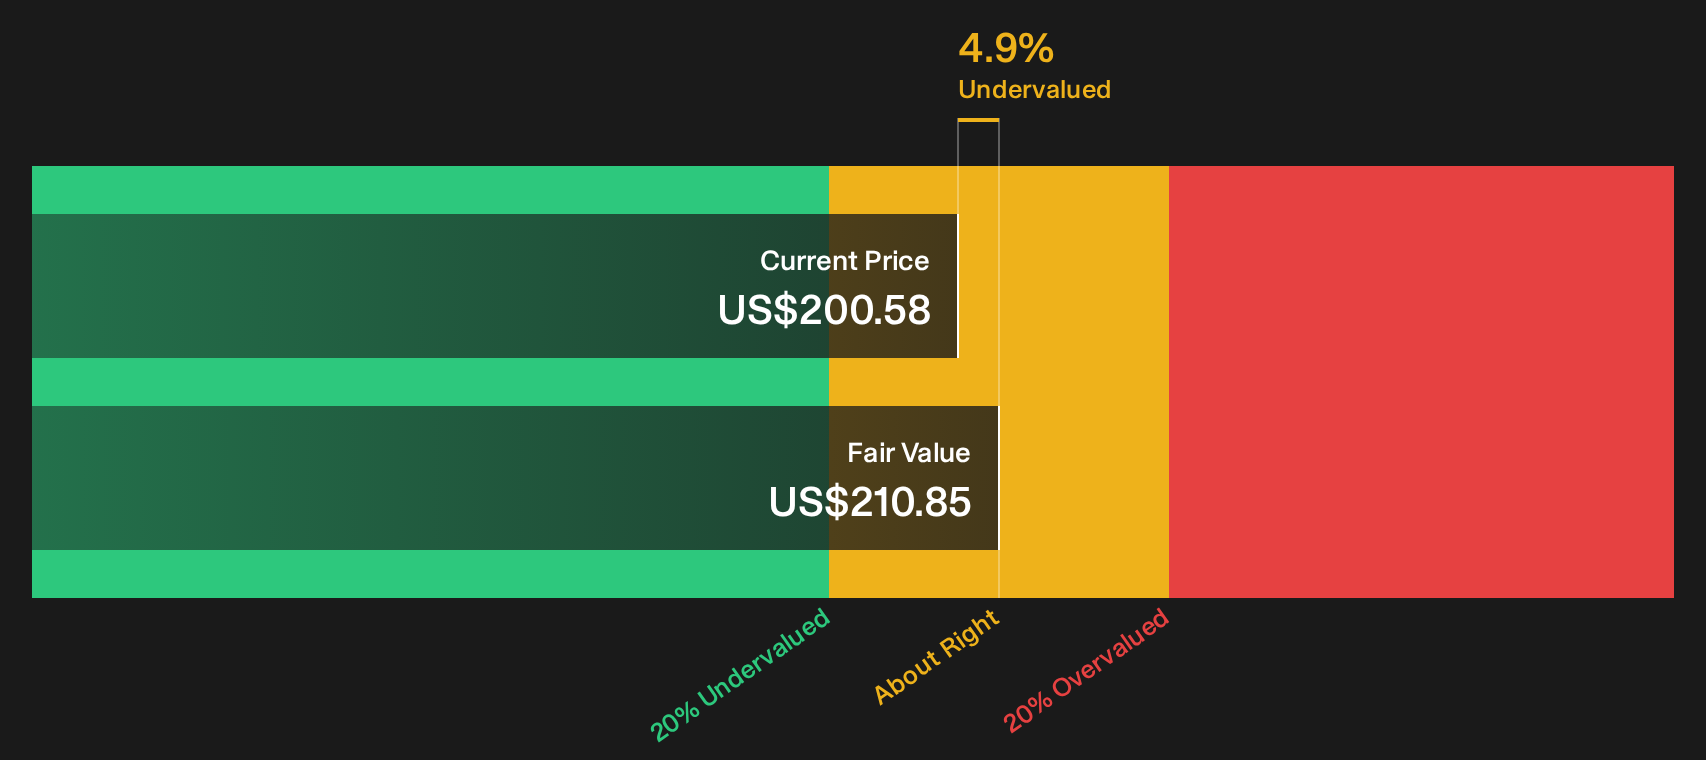
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cintas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Cintas valuation can feel messy, so move quickly, skim the numbers and narratives yourself, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more Cintas investment ideas?
If Cintas has your attention, do not stop here. Fresh ideas often come from scanning wider, and the right screener can surface opportunities you would otherwise miss.
- Target potential mispricings by reviewing the 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect underlying business quality.
- Strengthen your income game by scanning the 6 dividend fortresses that combine higher yields with businesses built for ongoing payout support.
- Sleep easier at night by filtering for the 30 resilient stocks with low risk scores that score well on balance sheet strength and overall risk checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com