


Danaher (DHR) has two new developments for investors. The board has approved a regular quarterly dividend of US$0.40 per share, and Leica Biosystems has completed its acquisition of pathology supplier StatLab Medical Products.
For context, Danaher’s share price has climbed 19.35% over the past 90 days, and the 1-year total shareholder return is 22.87%. Even though the year-to-date share price return is slightly down 1.33%, this suggests recent momentum has picked up again around these dividend and acquisition updates.
Scan for other healthcare and diagnostics stocks showing similar momentum by reviewing the hand picked 37 healthcare AI stocks that could benefit from the same demand for precision medicine and lab efficiency.
After a 19.35% move in 90 days and a fresh dividend decision on the table, the real puzzle around Danaher now is simple: Is most of the upside already in the rearview mirror, or is the valuation still leaving room ahead?
Most Popular Narrative: 1% Undervalued
On the most followed narrative, Danaher’s fair value of $229.09 sits just above the last close at $227.33. This frames the stock as only modestly below that estimate and puts the focus squarely on whether its core growth engines can deliver against that tight gap.
Accelerating demand for biologics and single use bioprocessing equipment, reflected in more than 30% year over year growth in bioprocessing equipment orders in early 2026 and mid teens order growth for consumables and equipment in Q2 2026, supports expectations for a multiyear capacity investment and onshoring cycle that can lift Biotechnology segment revenue and operating leverage.
See why 77 investors see Danaher as 1% undervalued.
Result: Fair Value of $229.09 (ABOUT RIGHT)
Still, the Danaher story can break if respiratory testing remains weaker than expected, or if China pricing pressure intensifies and squeezes Diagnostics profitability.
Find out about the key risks to this Danaher narrative.
Another View: Danaher Through The P/E Lens
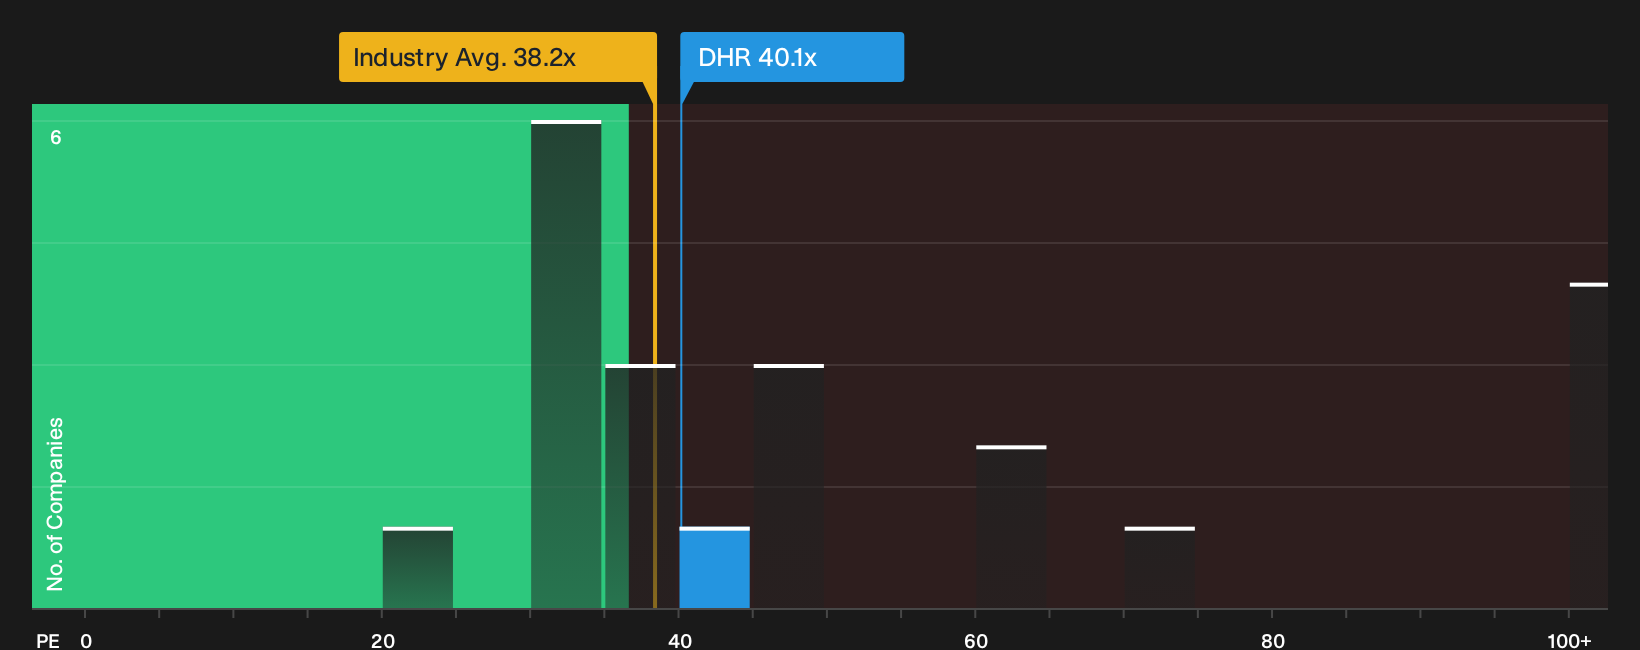
Danaher looks close to fair value on the narrative and analyst target, yet the P/E math paints a tougher picture. At 40.1x earnings versus peer averages around 38x and a fair ratio of 32.2x, investors are paying a premium. Is that cushion for quality or extra valuation risk?
To see how that premium compares with similar businesses, and where the market fair ratio could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Danaher leaves you unsure, use that tension as a prompt to move fast, pull up the data, and build your own framework. To weigh what could go right against what might go wrong in a single, balanced view, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Danaher?
Danaher might be your starting point, but your next edge often comes from scanning outside your usual watchlist and seeing which businesses are quietly lining up strong fundamentals.
- Target stability with companies that combine resilient finances and strong balance sheets by reviewing a hand picked list of solid balance sheet and fundamentals (25 results) before others notice the strength.
- Spot potential value gaps early by scanning the 16 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritize sleep at night over drama by focusing on 30 resilient stocks with low risk scores that aim to keep downside pressures more contained.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com