


Hamamatsu Photonics K.K (TSE:6965) drew investor attention after its 25 September 2026 board meeting, where directors prepared proposals for the December shareholder meeting and confirmed director Kazuhiko Mori’s retirement along with new Executive Officer appointments.
Hamamatsu Photonics K.K’s recent governance news lands after a mixed price pattern, with the share price rising 34.82% year to date but declining 16.28% over the past 90 days, while the 1-year total shareholder return of 46.05% points to stronger momentum over dividends and time.
Compare how Hamamatsu Photonics K.K’s recent governance reshuffle stacks up against other potential opportunities by scanning our curated list of 92 robotics and automation stocks in related high-tech hardware and automation.
After a sharp run this year, followed by a double digit pullback in the last quarter, Hamamatsu Photonics K.K now forces a timing question. Is the recent slide enough of a reset, or is patience worth more?
Preferred P/E of 38.5x: Is it justified?
Valuation now leans against Hamamatsu Photonics K.K, with the share price at ¥2,302 and a P/E of 38.5x that sits above several key comparison points.
The P/E ratio links the current share price to earnings per share and gives a shorthand view of how much investors are willing to pay for each unit of profit. For an electronics manufacturer that already reports revenue of ¥229,631 and net income of ¥17,214, this kind of multiple often reflects expectations for steady earnings and cash generation rather than an early-stage story.
Here, the market is assigning Hamamatsu Photonics K.K a P/E of 38.5x, compared with a peer average of 26.9x and a JP Electronic industry average of 16.6x. That is a strong premium. The estimated fair P/E of 21.5x is much lower again, which suggests a level the valuation could move toward if sentiment or growth expectations cool from current forecasts.
Explore the SWS fair ratio for Hamamatsu Photonics K.K.
Result: Price-to-earnings of 38.5x (OVERVALUED)
Still, the sharp 16.28% 90 day decline and a P/E well above both peers and the estimated fair level leaves Hamamatsu Photonics K.K exposed if sentiment weakens.
Find out about the key risks to this Hamamatsu Photonics K.K narrative.
Another View on Hamamatsu Photonics K.K
A second lens comes from the SWS DCF model, which estimates Hamamatsu Photonics K.K’s future cash flow value at ¥1,596.06 per share versus the current ¥2,302. On this view, the stock screens as overvalued. This raises the question of how much weight to place on long range cash flow forecasts compared with a relatively high current P/E ratio.
Look into how the SWS DCF model arrives at its fair value.
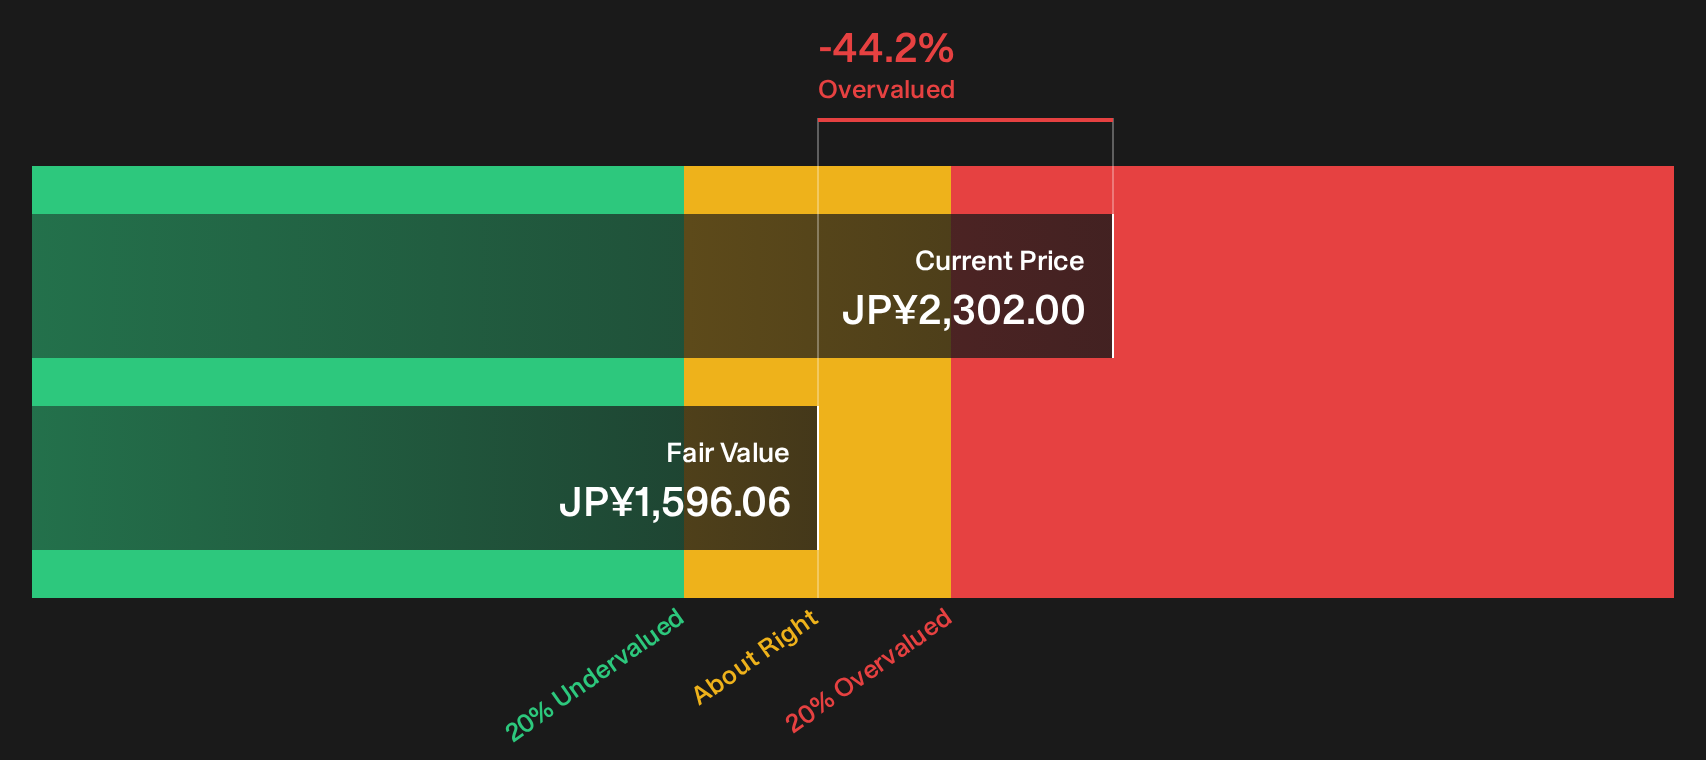
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hamamatsu Photonics K.K for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message? If Hamamatsu Photonics K.K has you undecided, move quickly, review the data yourself, and then weigh both the upside and downside using our breakdown of 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Hamamatsu Photonics K.K?
Do not stop your research at Hamamatsu Photonics K.K. Broaden your watchlist now so you are not chasing opportunities only after the crowd has moved.
- Target value upside early and scan a focused set of 19 high quality undervalued stocks that pair quality fundamentals with appealing price tags.
- Protect your downside and review 21 resilient stocks with low risk scores that score well on financial resilience before market stress exposes weak balance sheets.
- Get ahead of the market and hunt through 75 high quality undiscovered gems where strong metrics have not yet attracted heavy attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com