


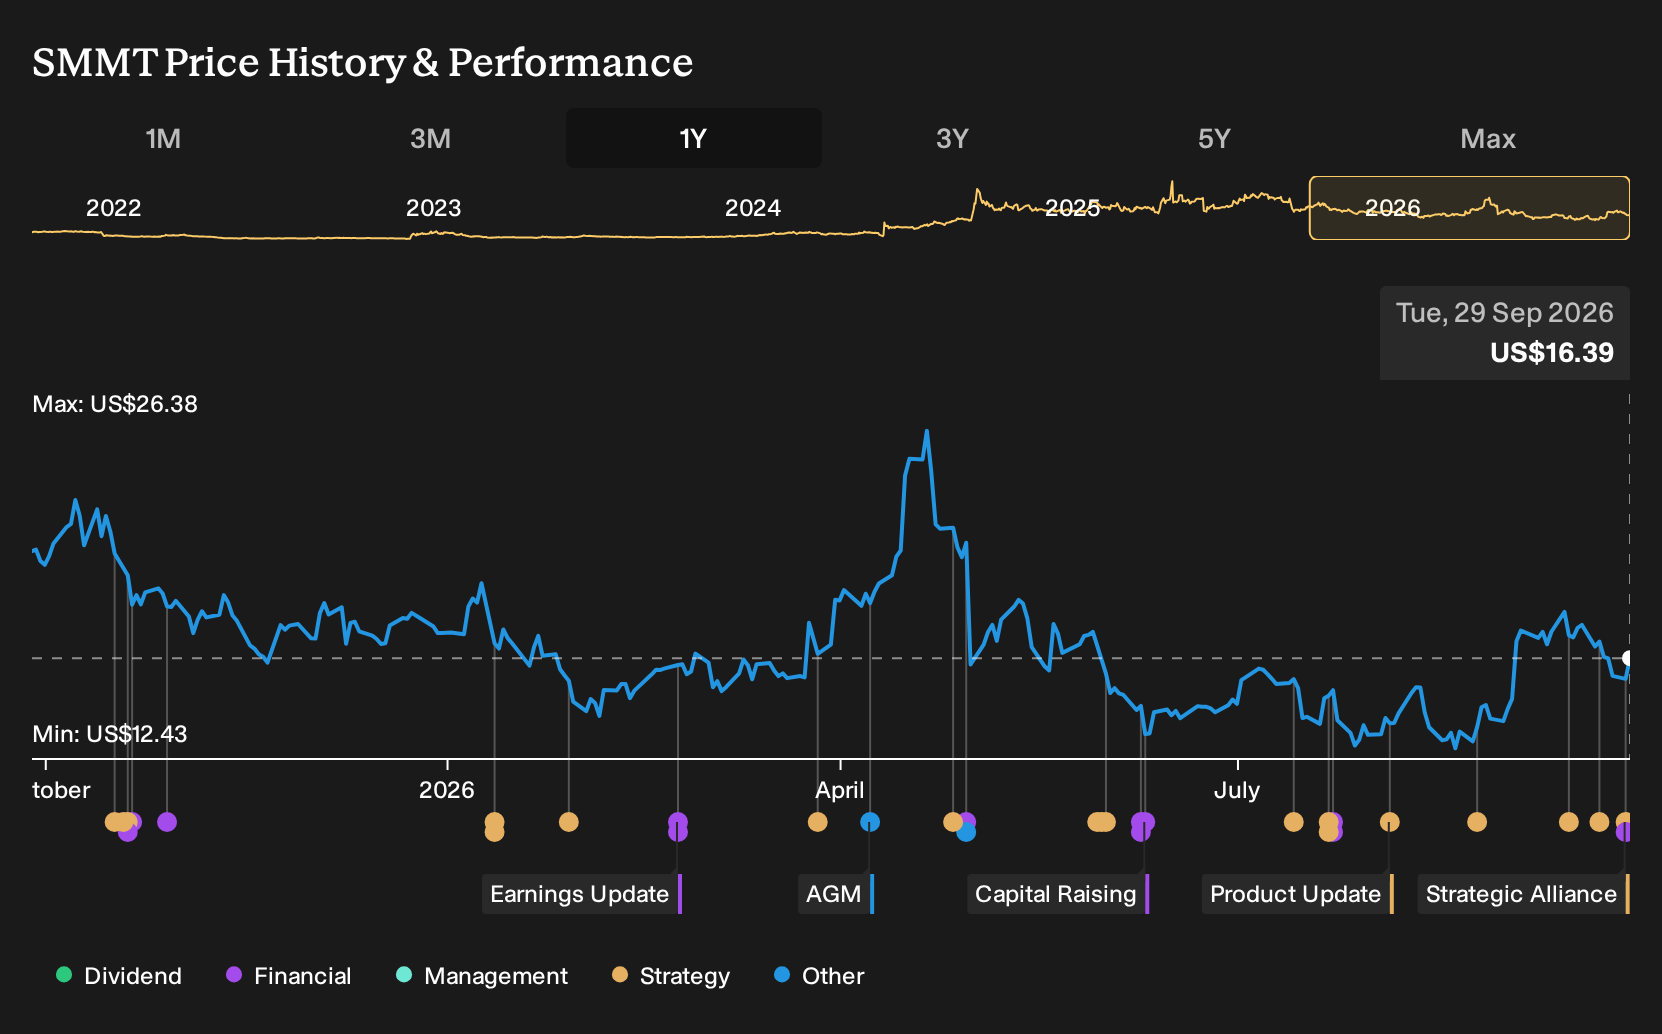
- On 28 September 2026, Summit Therapeutics announced a clinical collaboration with AstraZeneca to test sonesitatug vedotin plus ivonescimab in gastrointestinal cancers, alongside a non binding plan to explore ivonescimab with additional AstraZeneca cancer drugs.
- AstraZeneca also agreed to invest about US$2b in Summit via class A convertible preferred stock, indicating meaningful third party support for Summit’s ivonescimab focused development plan without changing ownership control.
- We examine how Summit Therapeutics’ investment narrative is affected by AstraZeneca’s US$2b preferred equity investment and trial partnership.
Scan the oncology space alongside Summit Therapeutics by sizing up hand picked 35 healthcare AI stocks working on cutting edge cancer treatments and data driven drug development.
Summit Therapeutics Investment Narrative Recap
To own Summit Therapeutics, you need to believe ivonescimab can transition from a single late stage asset into a multi indication cancer franchise, and that Summit can fund that effort despite having no current product revenue. The AstraZeneca collaboration and roughly US$2b preferred equity plan speak to outside interest, but they do not change that core bet.
In the near term, the key catalyst remains the FDA decision on the HARMONi BLA for ivonescimab, with the agency already focused on overall survival. The biggest operational risk remains concentrated exposure to one lead drug, heavy R&D and commercial spend, and the possibility that regulatory or trial outcomes slow the path to meaningful revenue.
The clearest companion announcement to monitor with this AstraZeneca news is the updated overall survival data from the global Phase III HARMONi trial. Ivonescimab plus chemotherapy showed a positive overall survival trend at the primary analysis and continued to show consistent, favorable hazard ratios with longer follow up, alongside an acceptable safety profile.
If the FDA accepts these data as sufficient for the November 14, 2026 PDUFA decision, that could open Summit Therapeutics’ first real commercial window and give the new GI and ADC combinations more strategic weight. If the agency views the overall survival package as falling short of expectations, the AstraZeneca collaboration and funding would help, but the primary regulatory and single asset risk would remain central.
Summit Therapeutics' narrative projects US$1.3b revenue and US$223.0m earnings by 2029. This implies roughly 50% yearly revenue growth from a zero base and an earnings increase of about US$1.08b from a current loss of US$856.1m.
Discover how Summit Therapeutics' fair value indicates a 89% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Summit Therapeutics leans heavily on execution risk. Before this AstraZeneca news, the most cautious analysts were only projecting about US$16.4 million of revenue and roughly US$2.8 million of earnings in 2029, paired with a very high implied P/E. That creates a sharply more pessimistic story than the consensus, and it might shift as you compare multiple viewpoints on this new partnership.
Explore 4 other Summit Therapeutics fair value estimates, including one that suggests as much as 31% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Summit Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Summit Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Summit Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Summit Therapeutics?
Once you have formed a view on Summit Therapeutics, it can help to compare that thesis with opportunities across other sectors and risk profiles. The Simply Wall St Screener gives you a structured way to line up different businesses side by side, so you can see how each one stacks up against the benchmarks that matter most to you.
- If you want potential growth with tight budgets in mind, scan a targeted group of 9 elite penny stocks with strong financials that already show stronger balance sheets and fundamentals than the typical micro cap.
- For investors who care most about quality at a reasonable entry point, review a hand picked set of 31 high quality undervalued stocks that pair healthier cash flows with more robust financial positions.
- If capital preservation ranks high on your list, compare a curated pool of 32 resilient stocks with low risk scores that score better on Simply Wall St's risk metrics and business stability checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com