


ReposiTrak stock slipped about 0.7% to roughly US$8.15 after earnings, which is a muted move for a software vendor that many investors view as a slow and steady compliance play. The headline is not the top line; the headline is margin power. Q4 revenue sat near US$5.6m, yet income from operations reached about US$1.9m and net profit margin over the last year ran near 32%, showing a business squeezing more profit out of each compliance and traceability dollar.
Is ReposiTrak trading at a genuine discount to its earnings power, or is that lower P/E multiple simply what the slower growth outlook deserves? Compare the current share price, DCF gap and peer multiples in the full valuation analysis for ReposiTrak
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): US$5.58m vs. US$5.76m (top line declined about 3% year over year)
- Net Income (Q4 2026 vs. Q4 2025): US$2.05m vs. US$1.73m (profit increased about 19% year over year)
- Basic EPS (Q4 2026 vs. Q4 2025): US$0.11 vs. US$0.09 (earnings per share rose about 20% year over year)
- Net Profit Margin (TTM vs. Prior Year): 31.8% vs. 29.3% (trailing twelve month profitability improved by about 2.5 percentage points)
Prefer clear, visual charts instead of another wall of earnings tables and raw numbers? See ReposiTrak’s full financial picture, including how its profitability trend fits into the broader business story, in our company report for ReposiTrak.
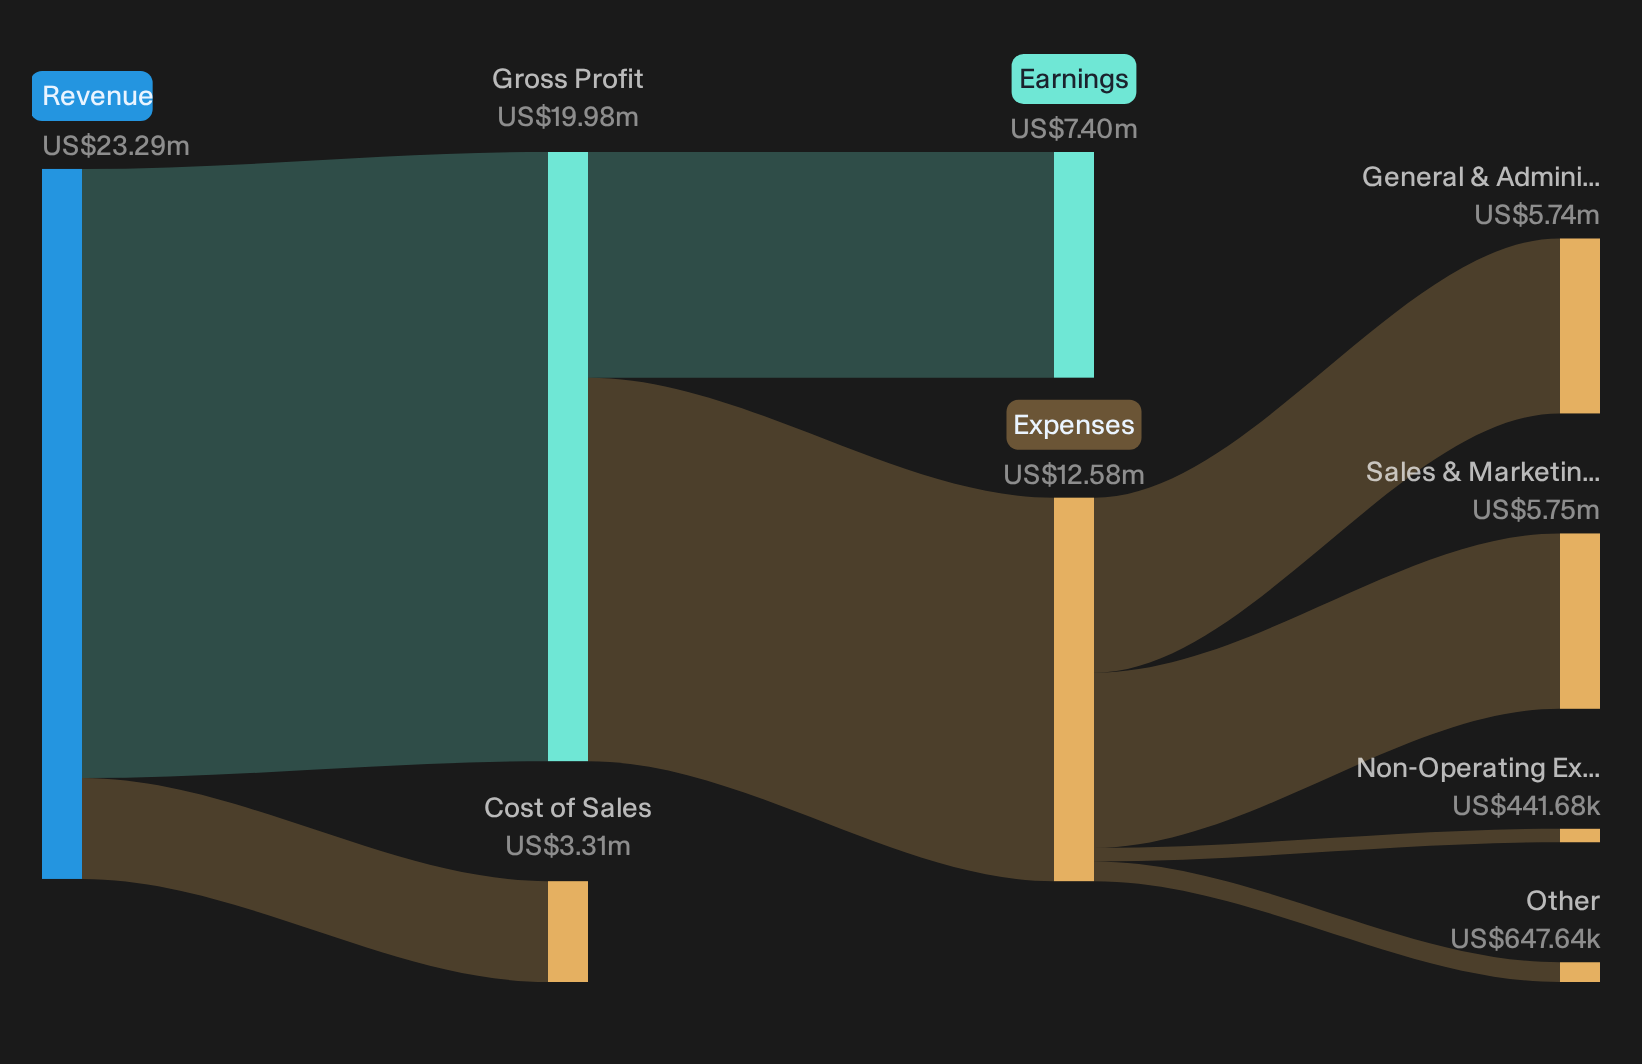
ReposiTrak bull story leans on margin and new engines
Optimists argue ReposiTrak is a compounding SaaS platform where rising traceability and merchandising demand feeds into recurring revenue and expanding profitability. The latest year gives that view some support. Total revenue only moved 3% to US$23.3m, yet operating income climbed 26% to US$7.8m as operating expenses fell 6%. That shift pushed operating margin to about 33.7%, which is a material step up and consistent with the idea that automation and higher margin software are doing more of the work. Recurring revenue grew about 4%, which backs the claim that the base subscription engine is at least moving in the right direction. Early contracts and revenue from the touchless merchandising launch with SPAR inside 45 days show execution against a new growth vector, even if the scale is still small.
Bear case focuses on sluggish top line and timing risk
Skeptics worry that ReposiTrak is a slow grower relying on regulatory deadlines and cost cuts rather than real demand acceleration. The numbers give that concern some traction. Full year revenue increased only 3% and Q4 revenue actually declined about 3% to US$5.6m after an elevated prior quarter, which challenges the idea of building momentum ahead of the FDA Rule 204 deadline in 2028. Cash from operations held at US$8.3m instead of moving clearly higher, even with stronger operating margin, which raises questions about how much working capital or customer timing is helping reported profit. Management talk around traceability revenue inflecting in 2027 and touchless merchandising becoming “very significant” is still aspirational for now. Recent share price performance, with the stock down about 14.6% over 90 days, suggests investors are treating these timing and growth risks seriously.
With earnings expanding and revenue growth running below broader market expectations, you cannot assume ReposiTrak has unlimited room for missteps. To evaluate this further, review whether cash flow, liquidity and obligations truly support this story in our financial health analysis of ReposiTrak stock.Own Your Next Investment Move
ReposiTrak’s mix of high margins and slower revenue progress creates a setup where timing matters. Register for free with Simply Wall St and add it to a Watchlist to track price against fair value and wait for conditions that match your plan. Once you have taken a position, use the Portfolio Command Center to cut through noise and get focused alerts on earnings, valuation shifts and key fundamental changes. For longer term conviction, lean on the Community to see how other investors are interpreting the same data and where their theses differ from yours. Spot potential catalysts or red flags early, stay ahead of market reactions and give yourself more time to make clear, informed decisions.
Seeking Alternatives Before Momentum Builds
Fresh ideas tend to move first. By the time every investor piles in, the cleanest entry points may be gone. Scan these under-the-radar opportunities while they are still relatively overlooked and consider how they might fit your approach.
- Track resilient performers that aim to hold up when sentiment turns by using a curated batch of 32 resilient stocks with low risk scores before the broader market pays closer attention.
- Look for potential future dividend workhorses with staying power by scanning a hand picked pool of 6 dividend fortresses while yields and prices still align with your criteria.
- Evaluate structural shifts in electricity demand by reviewing carefully filtered 39 power grid technology and infrastructure stocks before more capital focuses on the same grid upgrade theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com