


- Perella Weinberg Partners is reported to be benefiting from a surge in UK focused and cross border M&A deal activity projected at about $133b in 2026, which supports its advisory fee pipeline tied to transaction flow and pricing.
- The firm’s heavy reliance on deal volumes and fee margins means rising UK related mandates could materially influence how stable or volatile its advisory earnings profile appears to investors.
- We will now look at how this increased UK deal activity could shape Perella Weinberg Partners' broader investment narrative and risk profile.
What Is Perella Weinberg Partners' Investment Narrative?
For a shareholder in Perella Weinberg Partners, the core belief is simple. You are backing a people heavy advisory platform that relies on deal flow rather than heavy capex. Advisory revenue of about US$689.2m is tied almost entirely to transaction execution, pricing and retention of senior rainmakers. The recent surge in projected UK and cross border M&A activity directly feeds that engine, since the firm already sources a meaningful portion of its fees from the United Kingdom and other overseas markets.
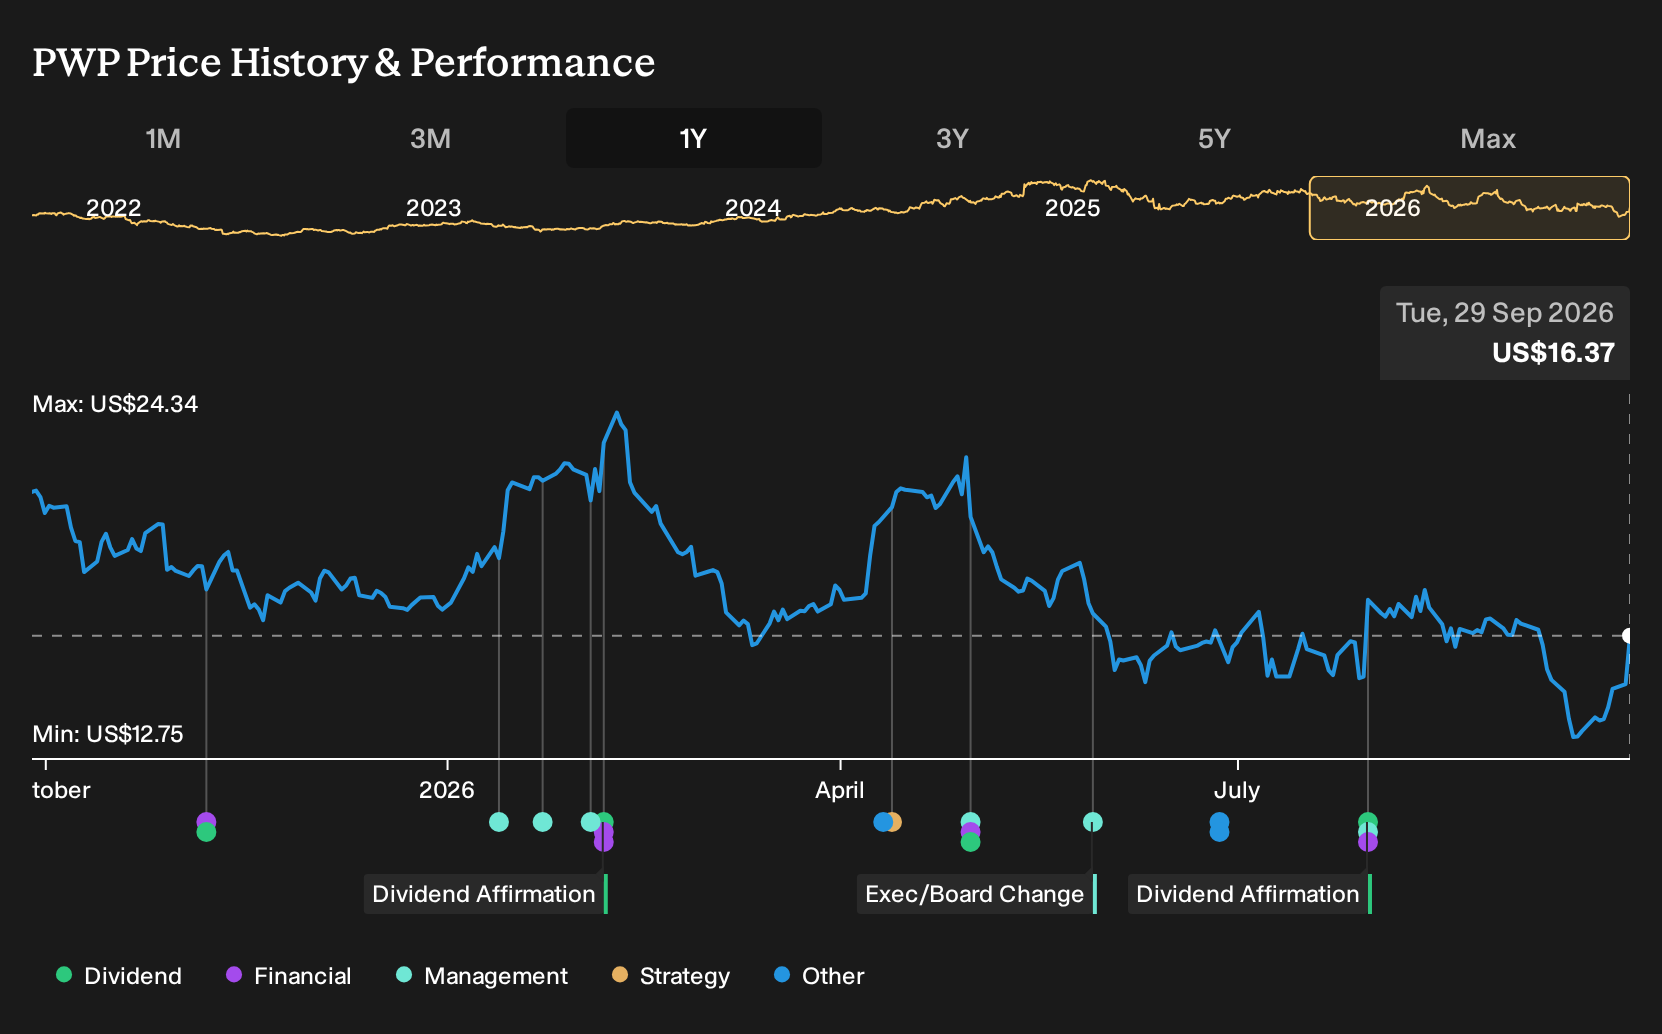
In the short term, that backdrop can matter because PWP’s earnings profile has looked patchy. Profit margins sit at 3.2%, down from 6.6% last year, and results include a one off loss of US$19.1m. The share price has risen 11.8% over 1 day and 22.7% over 7 days, although it is still down 22% over 1 year, with a 54.6x P/E multiple and forecasts indicating 22% annual revenue growth. Stronger UK deal activity could contribute to that growth profile, yet it also raises the stakes if volumes or pricing soften again.
That said, there is a less comfortable piece to the PWP story that sits behind the recent focus on UK deal flow and valuation multiples...
There's only one way to know the right time to buy, sell or hold Perella Weinberg Partners. Head to Simply Wall St's company report for the latest analysis of Perella Weinberg Partners's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so you may wish to rely on your own judgment.
- A great starting point for your Perella Weinberg Partners research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Perella Weinberg Partners. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Perella Weinberg Partners' overall financial health at a glance.
Looking For More Ideas Beyond Perella Weinberg Partners?
If you want to stress test your view on Perella Weinberg Partners, it can help to compare it with other businesses that share some of the traits you care about, whether that is value, resilience or income.
- If you are hunting for companies that look mispriced on the numbers, you could start with a focused set of opportunities through the 31 high quality undervalued stocks.
- For readers who care most about balance sheet strength and staying power through different market conditions, a curated list of solid balance sheet and fundamentals (25 results) can highlight candidates worth a closer look.
- If income is your priority and you want to see which companies currently offer stronger yields than Perella Weinberg Partners, consider scanning a selection of 6 dividend fortresses that have been filtered for payout potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com