


Markets are being pulled in several directions as regulators rewrite rulebooks, central banks signal possible shifts and trade disputes keep inflation worries alive. That mix can punish weaker businesses yet spotlight companies that earn a place in a Global Quality Defensive Stocks screener. Miss the sturdier options and you risk watching capital sit idle while others lean into resilience. This article walks through three such stocks exposed to these news catalysts.
The three stocks below are just a first look at this Global Quality Defensive Stocks idea. The full quantitative screen surfaced 67 more large, resilient businesses with similarly detailed stories that are not covered here. If you want to identify stronger fits for your own watchlist, head straight into the Global Quality Defensive Stocks screener to filter, analyze and focus on the highest conviction opportunities.
Gruma. de (BMV:GRUMA B)
Overview: Gruma is a global food producer that makes and sells corn flour, tortillas and related staple products across multiple continents.
Operations: Gruma generates most of its revenue in the United States and Mexico, with US$3.4b from US corn flour and tortillas and US$1.8b from Mexican corn flour.
Market Cap: MX$79.4b
Gruma fits the Global Quality Defensive Stocks theme because it sells everyday foods people keep buying through economic swings, while management works to protect earnings in more volatile channels.
"The planned capacity expansion in Central America to meet strong demand indicates potential for increased sales and EBITDA in the region due to enhanced production capabilities."
What happens to margins if a single pressure point on costs and pricing moves in Gruma’s favor at the same time?
If that margin swing is what you are watching, read the full narrative for Gruma. de to see how pricing, volume and capacity expansion could be quietly accelerating earnings quality.

Danone (ENXTPA:BN)
Overview: Danone is a global food and beverage group that sells dairy, plant based, nutrition and water products across multiple regions.
Operations: Danone generates about €13.2b from Essential Dairy and Plant Based products, €9.4b from Specialized Nutrition and €4.9b from Waters.
Market Cap: €37.8b
Danone fits the Global Quality Defensive Stocks idea because everyday yogurts, baby formula and bottled water can keep selling even as rates, regulations and trade policies shift around them. This can give the business a steadier demand backdrop than more cyclical sectors.
"Continued innovation and expansion in health-driven, functional foods and specialized nutrition, such as high-protein, probiotic, and medical nutrition products, positions Danone to participate in growth in these segments as global consumers become increasingly focused on wellness and science-based nutrition."
What happens to Danone’s earnings profile if one unresolved pressure on input costs and pricing power breaks in the company’s favor?
If that shift in input costs is the hinge you care about, go straight to the full narrative for Danone to see how Danone’s earnings mix could be quietly decoupling.

Cencora (COR)
Overview: Cencora is a global pharmaceutical distributor that supplies medicines and healthcare products to hospitals, pharmacies, clinics and manufacturers with recurring, volume driven revenue.
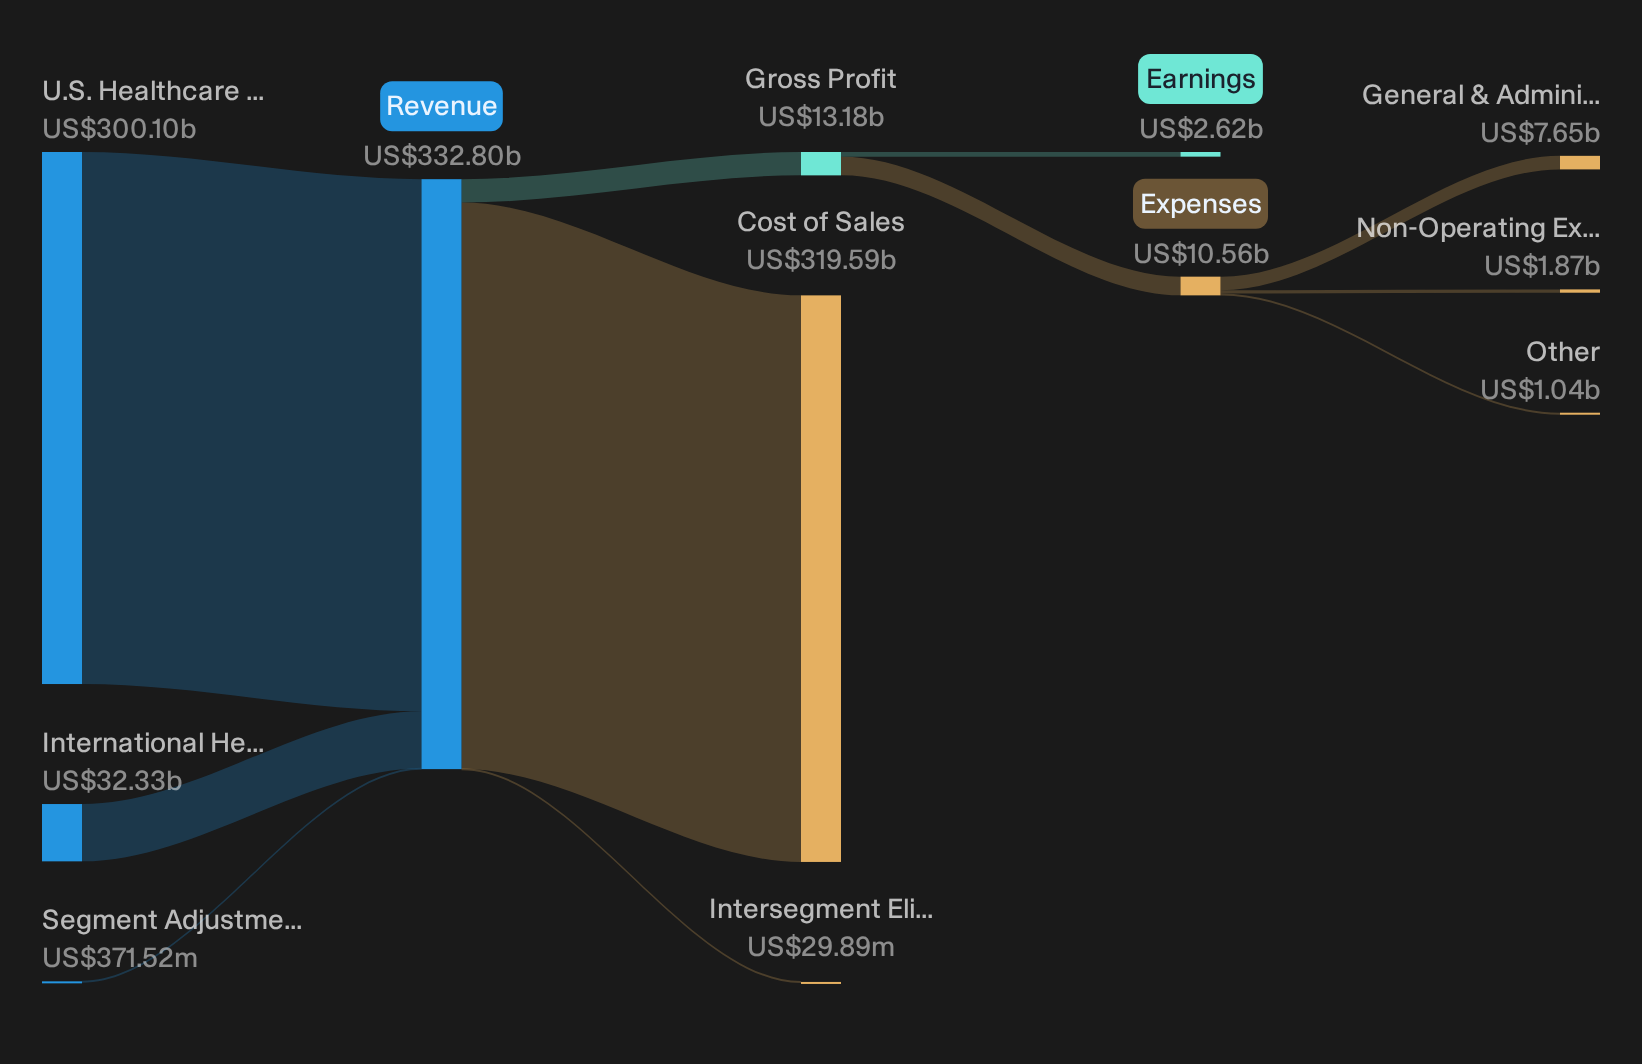
Operations: Cencora generates about US$300.1b from U.S. Healthcare Solutions and US$32.3b from International Healthcare Solutions, with smaller adjustments and eliminations.
Market Cap: US$58.0b
In a Global Quality Defensive Stocks context, Cencora matters because recurring drug distribution and healthcare services can keep cash flows steadier while policy, inflation and trade headlines keep shifting.
"Cencora's continued investment in digital infrastructure, including AI driven demand forecasting that is already being used to improve product availability and cash management, can support further efficiency in distribution operations and potentially lift net margins and earnings as these tools are rolled out more widely."
Consider what happens to Cencora’s earnings power if a quiet change in how high margin services scale against that distribution base moves in your favor.
That quiet shift in high margin services is exactly what the full narrative for Cencora unpacks, highlighting where Cencora’s earnings engine may be quietly accelerating beyond distribution scale.
Seeking Alternatives Before Momentum Flies
Fresh ideas often move first. Watch quiet, high-quality names build breakout momentum while others remain focused on yesterday’s stories. Use timely filters while they are still looking under the radar, and consider acting while these opportunities are less widely followed.
- Track cash-rich compounders that can keep options open when conditions shift by scanning the list of solid balance sheet and fundamentals (204 results) curated by strict balance sheet and fundamentals rules.
- Monitor early movers in AI infrastructure before enthusiasm becomes more widespread by running the 88 AI infrastructure stocks that highlights hand-picked enablers of data centers and compute capacity.
- Review potential opportunities in critical materials by using the 35 best rare earth metal stocks focused on carefully screened producers tied to advanced manufacturing trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com