


Life Time Group Holdings (LTH) has moved beyond its core clubs with the launch of Life Time Social, a private membership community built around curated wellness, nightlife and destination experiences.
Recent trading shows mixed momentum. The share price return is up 4.95% over the past week but down 7.88% over the last month. Life Time Group Holdings still carries a 50.17% year to date share price return and a 168.99% three year total shareholder return that keeps longer term performance in focus.
Spot similar lifestyle and wellness plays riding experience-led demand by scanning our hand picked 17 high quality undiscovered gems alongside Life Time Group Holdings.Life Time Group Holdings now trades near recent highs after a strong year, yet the latest pullback hints at fresh debate. Is most of the easy upside already captured, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 28% Undervalued
Against the last close of $40.08, the most followed narrative for Life Time Group Holdings pegs fair value at $55.43, which suggests the market is pricing its wellness platform below that framework.
The expanding pipeline of new and larger club openings in affluent and high-density markets positions Life Time for sustained membership and top-line revenue growth, benefiting from the growing consumer demand for premium health, wellness, and lifestyle experiences. Accelerating growth in ancillary, higher-margin services including personal training, Life Time Digital offerings, nutritional supplements, and health or wellness programs supports increased average revenue per member and improved net margins as consumer expectations shift toward holistic wellness.
See why 10 investors see Life Time Group Holdings as 28% undervalued.
Result: Fair Value of $55.43 (UNDERVALUED)
Still, the bullish Life Time Group Holdings story frays quickly if heavy club build outs strain capital or if higher priced memberships encounter softer discretionary spending.
Find out about the key risks to this Life Time Group Holdings narrative.
Another View on Life Time Group Holdings Valuation
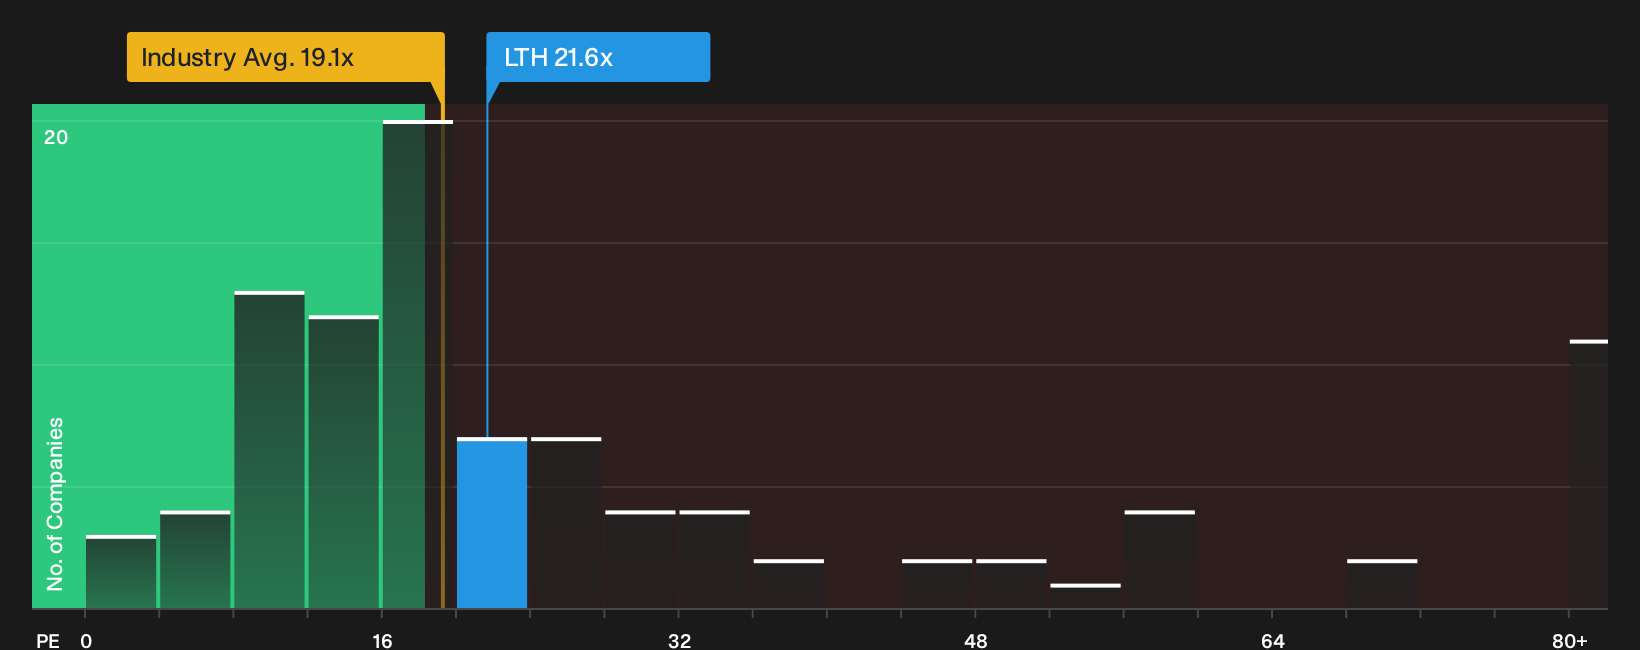
There is a different read on Life Time Group Holdings when the focus shifts from analyst targets to the current P/E. The stock trades on 21.6x earnings, above the US Hospitality average of 19.1x, and slightly above its own fair ratio of 21.1x.
That kind of premium can signal confidence in the wellness model, but it also narrows the margin for error if growth or margins do not match expectations. Does this look like a valuation cushion, or more like a full price for what Life Time Group Holdings delivers today?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Life Time Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Life Time Group Holdings are clear, so act while the data is fresh and form your own stance using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Life Time Group Holdings?
If you stop with Life Time Group Holdings, you risk missing other opportunities that match your style, risk comfort, and return expectations across the market.
- Target fresh upside potential by scanning 31 high quality undervalued stocks that combine compressed valuations with solid underlying fundamentals.
- Strengthen income resilience by reviewing 6 dividend fortresses that pair higher yields with business models built around recurring cash flows.
- Dial down portfolio stress by focusing on 32 resilient stocks with low risk scores that score well on financial stability and volatility control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com