


Amidst a backdrop of fluctuating global markets and inflation concerns, the Asian market presents unique opportunities, particularly within its small-cap segment. As investors navigate these dynamic conditions, identifying stocks with strong fundamentals and growth potential becomes increasingly crucial.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xinxiang Chemical Fiber | 69.88% | -0.33% | -29.16% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Natural Food International Holding (SEHK:1837)
Simply Wall St Value Rating: ★★★★★☆
Overview: Natural Food International Holding Limited is an investment holding company that focuses on manufacturing and selling natural health food products in China, with a market capitalization of approximately HK$3.01 billion.
Operations: The company's primary revenue stream is from the processing and selling of natural health products, generating approximately CN¥2.84 billion.
Natural Food International Holding, a smaller player in the food industry, is making waves with impressive earnings growth. Over the past year, earnings surged by 54%, outpacing the industry's modest 0.8% rise. The company trades at a significant discount of 52.5% below its estimated fair value and maintains high-quality earnings with positive free cash flow. Recent financials for the half-year ended June 2026 show sales climbing to CNY 1.45 billion from CNY 1.13 billion last year, while net income jumped to CNY 155.9 million from CNY 106.77 million, reflecting robust operational performance and promising future potential.

Youzan Technology (SEHK:6051)
Simply Wall St Value Rating: ★★★★★☆
Overview: Youzan Technology Limited is an investment holding company offering e-commerce solutions both online and offline in China, Japan, and Canada, with a market cap of approximately HK$1.98 billion.
Operations: The company's primary revenue streams include Merchant Services, generating CN¥1.30 billion, and Third Party Payment Services, contributing CN¥313.05 million.
Youzan Technology, a dynamic player in the Asian tech landscape, has been making waves with its strategic moves and financial performance. The company reported CNY 769.38 million in sales for the first half of 2026, up from CNY 713.59 million year-on-year, reflecting its successful merchant expansion and AI commercialization efforts. Despite a slight dip in net income to CNY 67.73 million from last year's CNY 72.74 million, Youzan's proactive share buyback strategy saw it repurchase over 251 million shares for HKD 27.21 million this year alone, enhancing shareholder value amidst ongoing growth initiatives and industry challenges.
- Take a closer look at Youzan Technology's potential here in our health report.
Understand Youzan Technology's track record by examining our Past report.

MoneyMax Financial Services (SGX:5WJ)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: MoneyMax Financial Services Ltd. is an investment holding company that provides financial services and operates as a retailer and trader of luxury products in Singapore and Malaysia, with a market capitalization of SGD711.80 million.
Operations: MoneyMax generates revenue primarily from its retail and trading of gold and luxury items (SGD477.52 million) and pawnbroking services (SGD163.98 million). The secured lending segment contributes an additional SGD23.64 million to its revenue streams.
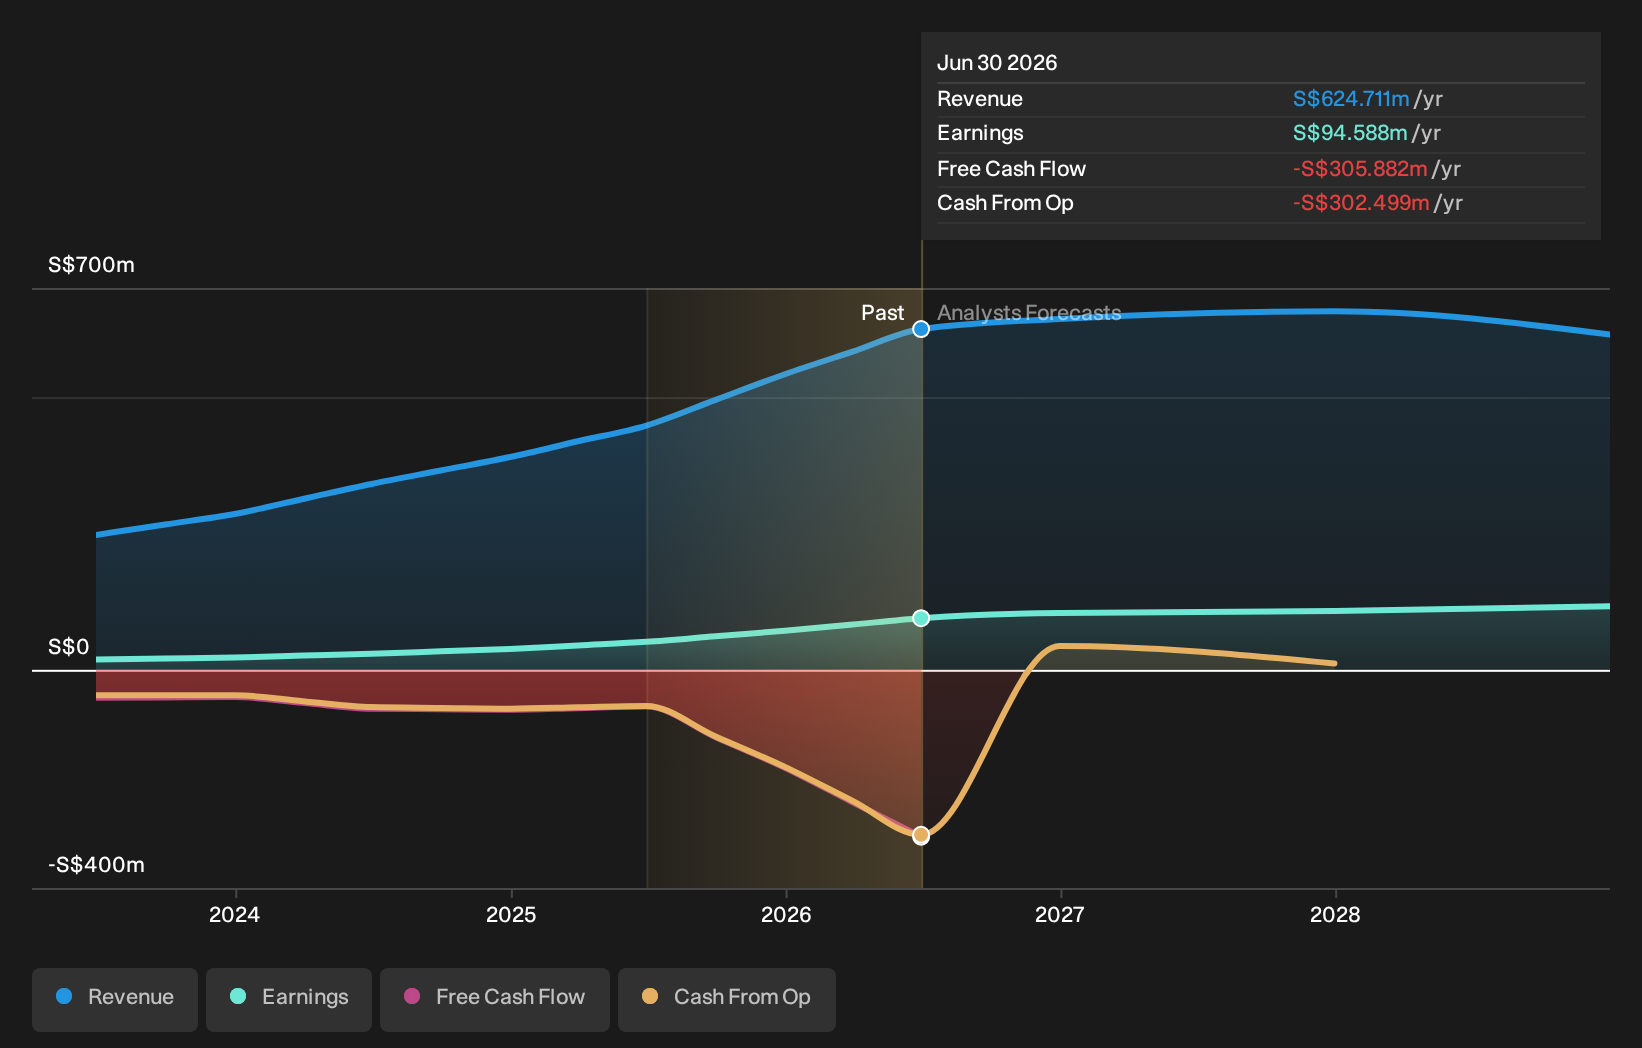
MoneyMax Financial Services, a financial entity in Asia, has shown promising growth with earnings surging 84.4% over the past year, outpacing the Specialty Retail industry’s 35%. Despite a high net debt to equity ratio of 266%, its interest payments are well covered by EBIT at 4.5 times. The company trades at a good value, being 15.5% below estimated fair value and was recently added to the S&P Global BMI Index. For H1 2026, sales reached SGD325.73 million compared to SGD242.96 million last year, with net income climbing to SGD52.55 million from SGD29.64 million previously.
Where To Now?
- Get an in-depth perspective on all 121 Asian Undiscovered Gems With Strong Fundamentals by using our screener here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com