


Asahi Intecc (TSE:7747) has drawn fresh attention after a recent price move, with the stock closing at ¥3,330. Investors are now weighing that level against the firm’s medical device footprint.
Recent trading has been choppy for Asahi Intecc, with a 1-day share price return of 1.99% and a 7-day gain of 1.68% following a 30-day share price decline of 12.60% and a 90-day drop of 10.82%. At the same time, the year-to-date share price return of 12.20% and 1-year total shareholder return of 40.48% indicate that short-term momentum has cooled while performance over the longer period remains positive.
Scan beyond Asahi Intecc and track other potential breakouts in medical and quality-focused names with our hand picked 75 high quality undiscovered gems.
Asahi Intecc appears to be a solid medical device player on the business side. However, the latest swing to ¥3,330 raises a different question: Are you paying a fair price for that quality today?
Price-to-Earnings of 27.5x: Is it justified?
On simple earnings terms, Asahi Intecc trades on a P/E of 27.5x, which places a clear premium on the ¥3,330 share price compared to peers.
The P/E ratio compares what investors pay today with the company’s current earnings per share. For a healthcare equipment producer like Asahi Intecc, it often reflects how much investors are willing to pay for its profit profile and the perceived durability of those earnings.
Here the market is assigning a richer multiple than both the peer average of 21.3x and the broader JP Medical Equipment industry on 16.8x. That means buyers are accepting a much higher price tag per unit of earnings than the sector norm. The estimated fair P/E of 23.9x is also below the current 27.5x. This suggests the valuation may move closer to that lower level if sentiment cools or expectations reset.
Explore the SWS fair ratio for Asahi Intecc.
Result: Preferred multiple of 27.5x price-to-earnings (OVERVALUED)
Still, Asahi Intecc faces clear risks if medical device demand softens or if higher priced rivals and OEM partners pressure margins and pricing power.
Find out about the key risks to this Asahi Intecc narrative.
Another View on Asahi Intecc’s Value
The earlier P/E workup painted Asahi Intecc as expensive at 27.5x earnings. The SWS DCF model points in a different direction. It puts estimated future cash flow value around ¥3,994.59 per share versus the current ¥3,330 level, which implies the stock trades at about a 16.6% discount.
Both lenses cannot be right at the same time for long. If one side of this gap closes first, which story do you think the market will end up believing?
Look into how the SWS DCF model arrives at its fair value.
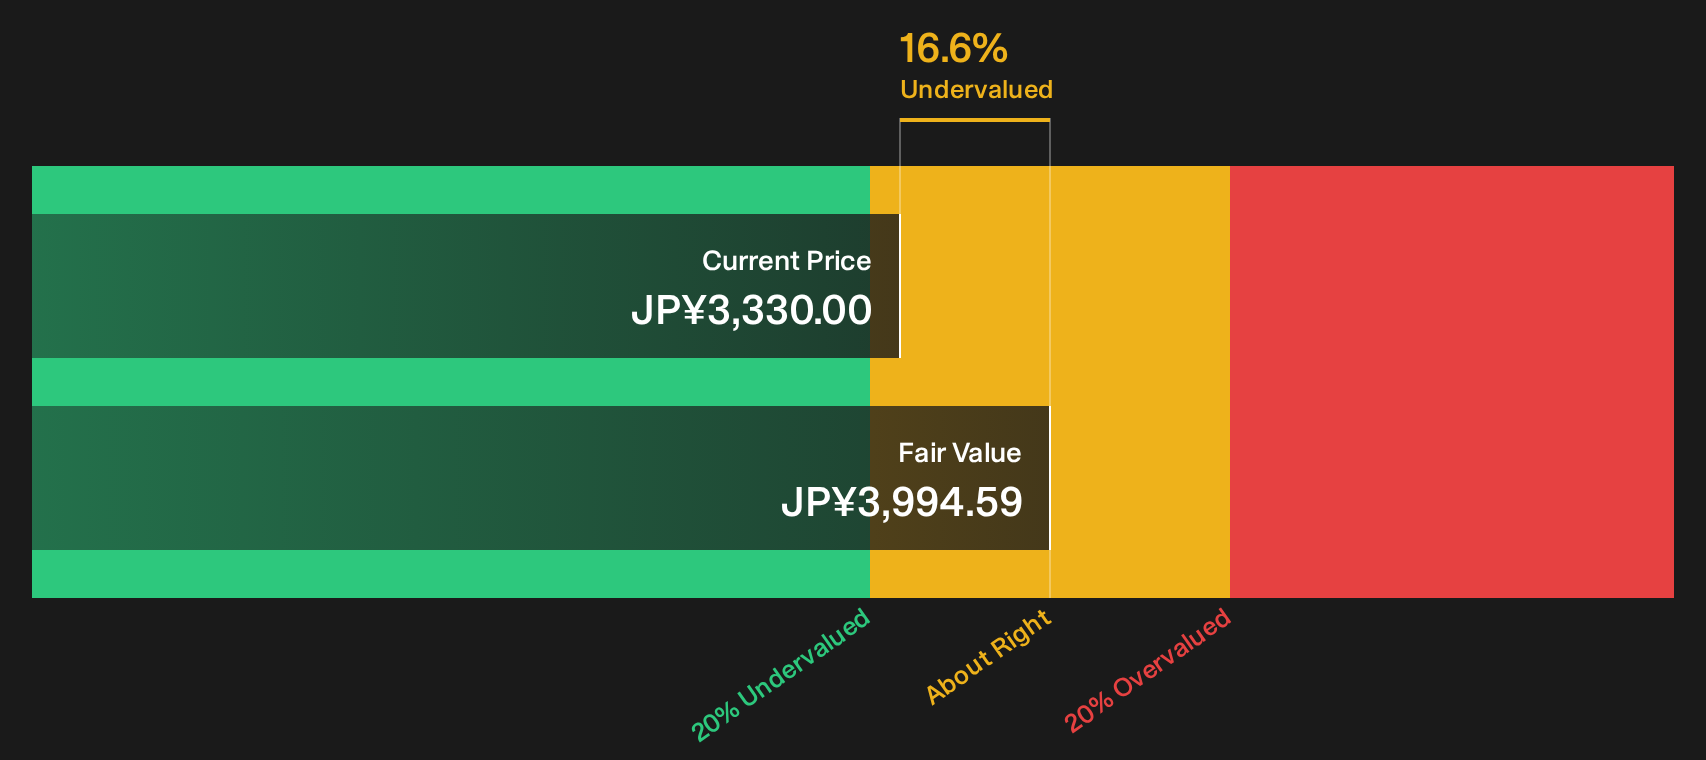
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Asahi Intecc for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split view on Asahi Intecc’s value leaves you torn, act while the data is fresh and decide where you stand on the outlook. Then pressure test that early view by digging into the 3 key rewards
Looking for more Asahi Intecc investment ideas?
Do not stop at Asahi Intecc. Use this momentum to scan the wider market now, before the next wave of opportunities moves out of reach.
- Target potential mispricings by running through our 19 high quality undervalued stocks that highlight businesses with quality fundamentals trading below their implied worth.
- Strengthen your income stream by reviewing the 20 dividend fortresses that focus on companies offering higher yields with staying power.
- Prioritise resilience by scanning the 21 resilient stocks with low risk scores that feature businesses with lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com