


Constellation Brands has seen its share price slide in recent years, and that drop has sharpened the question of whether the current US$112.77 level still lines up with the earnings power behind the beer and spirits group. With sentiment hit by weaker alcohol demand and shifting expectations, the core issue now is what those earnings are really worth.
- The stock has fallen 51.5% over the past 3 years, which puts a spotlight on whether the market is reassessing how much investors should pay for Constellation Brands' earnings stream.
- Recent pressure from tariffs on aluminum cans and softer US alcohol consumption may affect profit margins and future earnings expectations, which can directly shape how supportive the current P/E multiple is.
- The analysts covering Constellation Brands have run their own numbers. See what analysts think Constellation Brands's shares could be worth.
The issue now is whether Constellation Brands' current share price is justified by the earnings it is generating today and is expected to deliver over time.
If you want a wider starting point while you weigh Constellation Brands’ earnings story, a focused screen of 32 high quality undervalued stocks can help surface other ideas worth researching alongside it.
Is Constellation Brands a Bargain on Earnings?
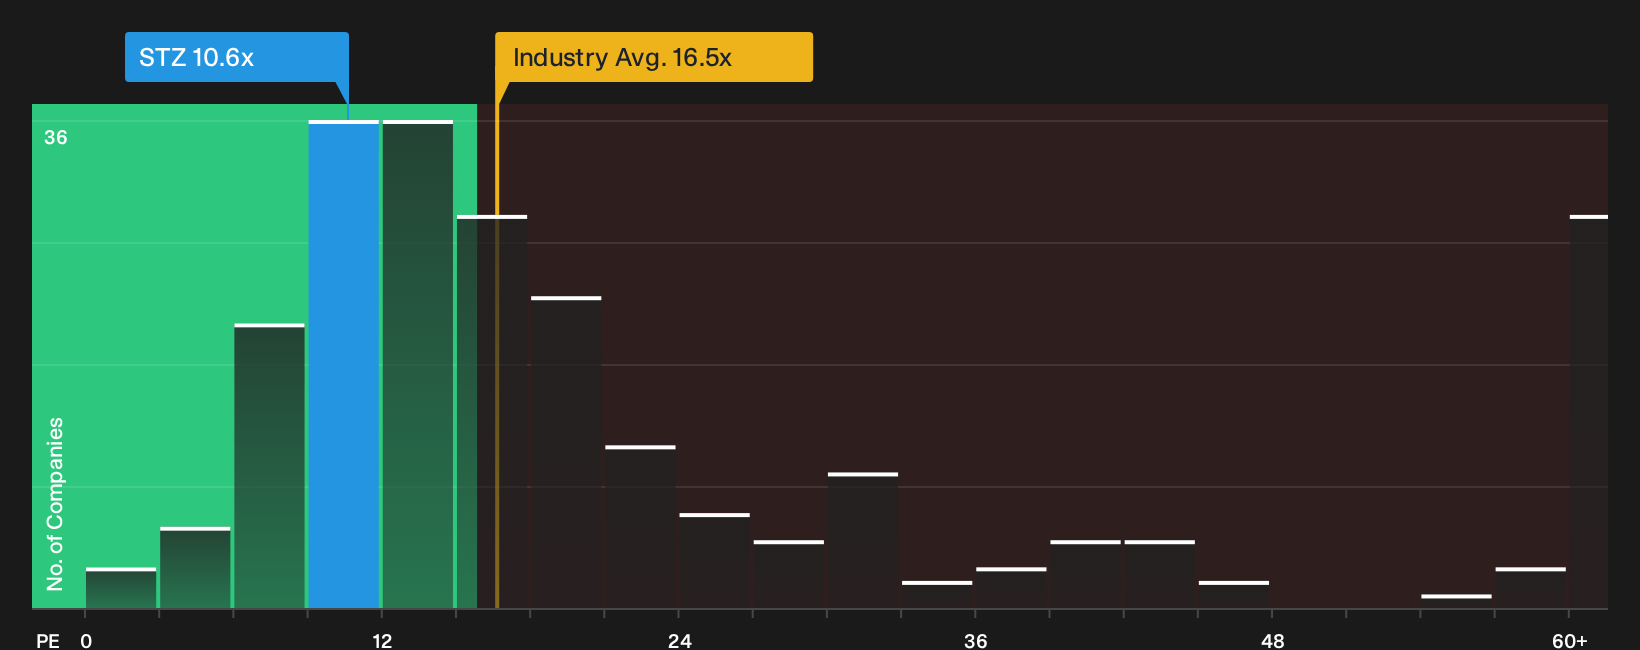
The P/E ratio is a useful lens for Constellation Brands because earnings are still the key driver most investors watch for this kind of consumer staples group. At roughly 10.6x earnings, the stock changes hands at a sizeable discount to both the Beverage sector average of about 16.5x and a broader peer group closer to 22.0x. That gap suggests the market is assigning a lower value to each dollar of the company’s profit than to many competitors in the same space.
On this framework, the Fair Ratio model, which factors in Constellation Brands’ margins, growth profile, size and risk, points to a higher multiple than the one currently attached to the shares, so the stock screens as undervalued on earnings. Because the business has pulled its fiscal 2028 outlook and faces softer US alcohol demand, the discounted P/E looks tied to the uncertainty now hanging over future results rather than to a clear collapse in the current earnings base. Explore the numbers behind Constellation Brands's P/E valuation.
The Constellation Brands Narrative: What Would Justify Today's Price?
Constellation Brands' Simply Wall St Narratives pick up where the P/E puzzle leaves off by spelling out which mix of future growth, margins and earnings paths would need to play out for the stock to be worth materially more or materially less than today’s price, all housed on the company’s Community page. Rather than a single multiple or model output, each narrative lays out the assumptions behind its estimated value so you can compare those moving parts with actual results as they arrive.
One of the top community narratives on Constellation Brands: 31% undervalued
"The current valuation implies that the market is pricing Constellation Brands as if flat beer sales, weaker alcohol demand, and margin pressure will persist..."
Discover why this Narrative puts Constellation Brands at 31% undervalued.
One more Constellation Brands check that sits alongside the price tag
The leadership behind Constellation Brands and the way their pay packets line up with long term shareholder outcomes can be just as important as any P/E screen. See who runs Constellation Brands and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com