


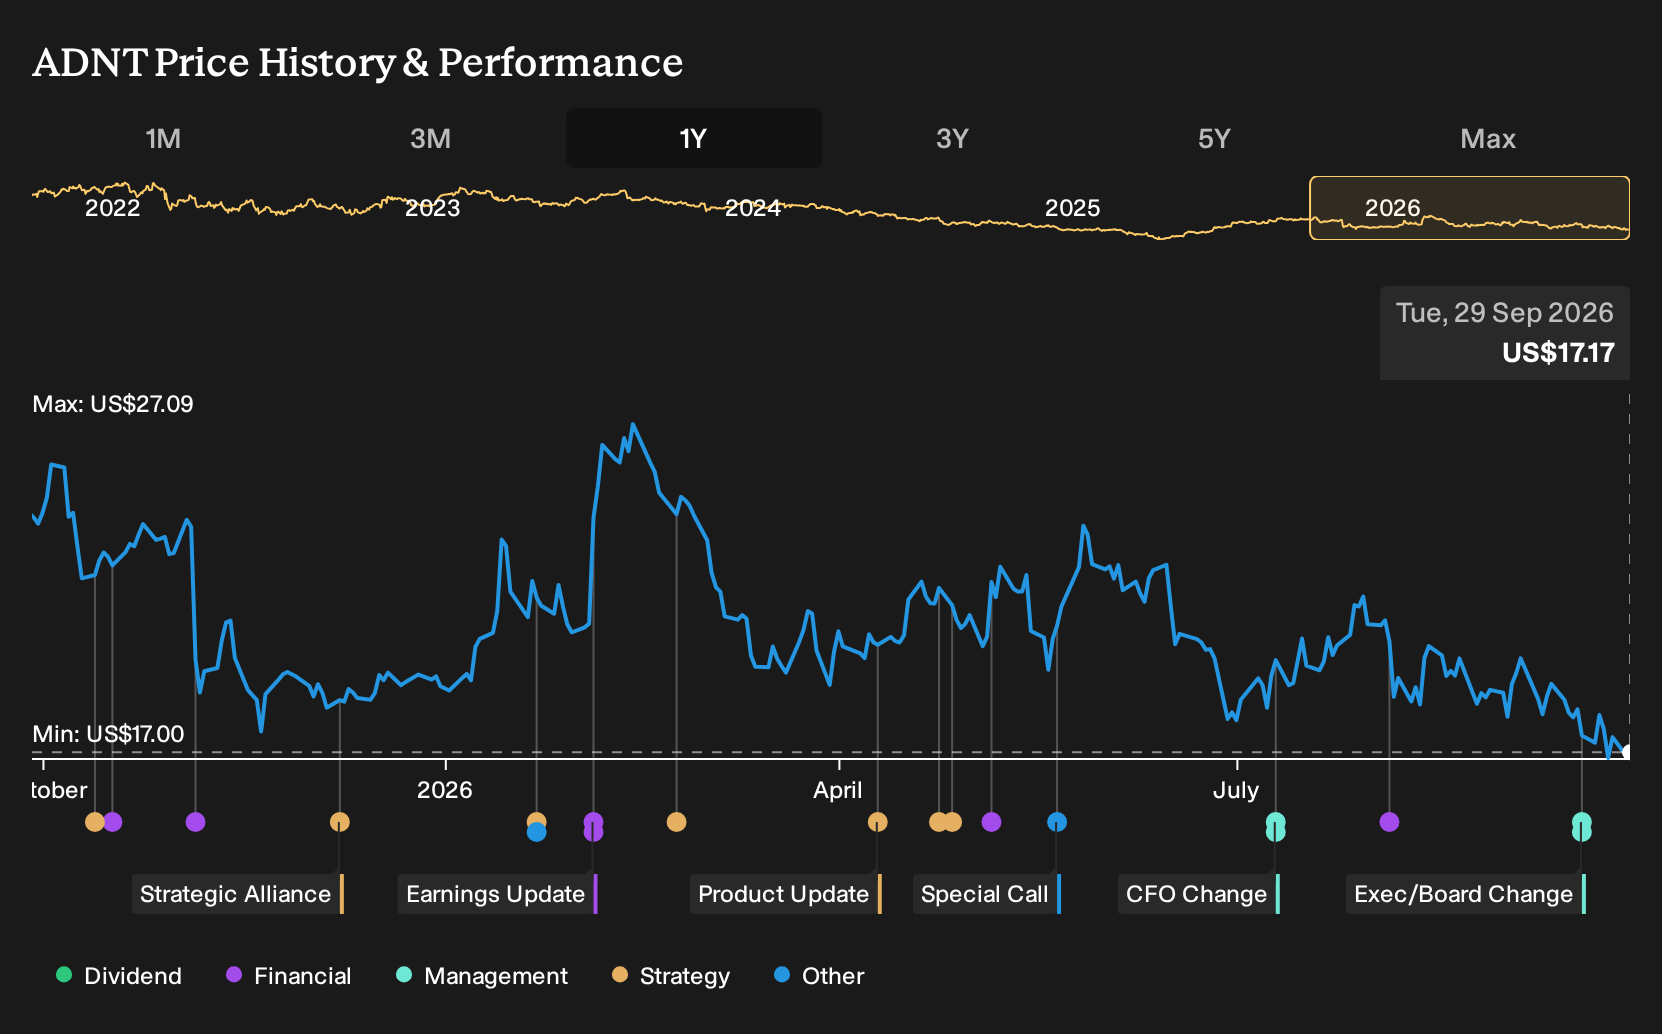
- Adient reported that Peter Carlin stepped down from its board on October 1, 2026. He joined management as vice president of finance and is scheduled to become chief financial officer and executive vice president on November 16, 2026. The board size will be reduced to seven directors following his departure.
- Carlin brings a long track record in investment analysis, capital allocation, and board oversight from roles at GameStop, multiple investment firms, and Investors Bancorp. This background gives Adient a finance leader with experience in evaluating business performance, balance sheet choices, and risk.
- The following section reviews how Adient's investment narrative could be affected by the appointment of Peter Carlin as incoming CFO.
Scan how Adient's CFO transition compares with peers by reviewing a curated list of financially resilient companies in our list of solid balance sheet and fundamentals (25 results).
Adient Investment Narrative Recap
To own Adient, you need to believe the seating supplier can turn a complex, global footprint into steadier earnings while adapting to EV focused platforms. The key near term swing factor is execution on restructuring and cost programs, especially in Europe where margins have been described as trough level and cash outflows remain heavy.
The biggest risk right now is that weaker volumes in EMEA and China, plus any new tariffs or commodity cost spikes, keep squeezing profitability and free cash flow. The CFO transition itself does not materially change these operational pressures. However, it puts more attention on balance sheet decisions and on how aggressively management tackles underperforming contracts.
The most relevant development is Peter Carlin moving from Adient's board into the finance seat as incoming CFO and executive vice president. He steps into a business that has only recently become profitable and where interest payments are not well covered by earnings, so the finance brief is tightly linked to day to day resilience rather than just high level capital allocation.
For you as a shareholder, the question is whether this change improves execution on the existing catalysts. Those catalysts include potential gains from EV focused seating programs, U.S. onshoring wins and ongoing restructuring to lift European margins. If cost control slips or restructuring cash demands stay elevated, that would directly challenge the thesis that Adient can steadily improve earnings quality.
Adient's current analyst narrative points to revenue of US$15.8b and earnings of US$335.6m by 2029, based on a 2.0% yearly revenue growth assumption and an earnings increase of about US$276.6m from US$59.0m today.
Uncover why Adient's fair value indicates an 83% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Adient's exposure to slower electric vehicle adoption and shrinking seating demand. Under that lens, the lowest analysts were only penciling in 1.0% yearly revenue growth to about US$15.4b and earnings of roughly US$267.1m by 2029. With Peter Carlin now stepping into the CFO role, those pre news assumptions may shift, so treat them as moving pieces and explore how different analysts frame the trade off.
Explore 3 other Adient fair value estimates, including one that suggests it could be worth just $28.01!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Adient research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adient's overall financial health at a glance.
Looking for more Adient sized investment ideas?
If Adient is already on your radar, it can help to compare it with a mix of other resilient businesses so you can pressure test your thesis and spot fresh opportunities.
- For investors hunting for potentially underappreciated quality, scan a curated set of companies trading below what their fundamentals might justify through the 32 high quality undervalued stocks.
- If steady balance sheets matter most to you, focus on businesses with stronger financial footing using the list of solid balance sheet and fundamentals (25 results).
- When income is the priority, narrow in on established payers offering higher yields by reviewing the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com