


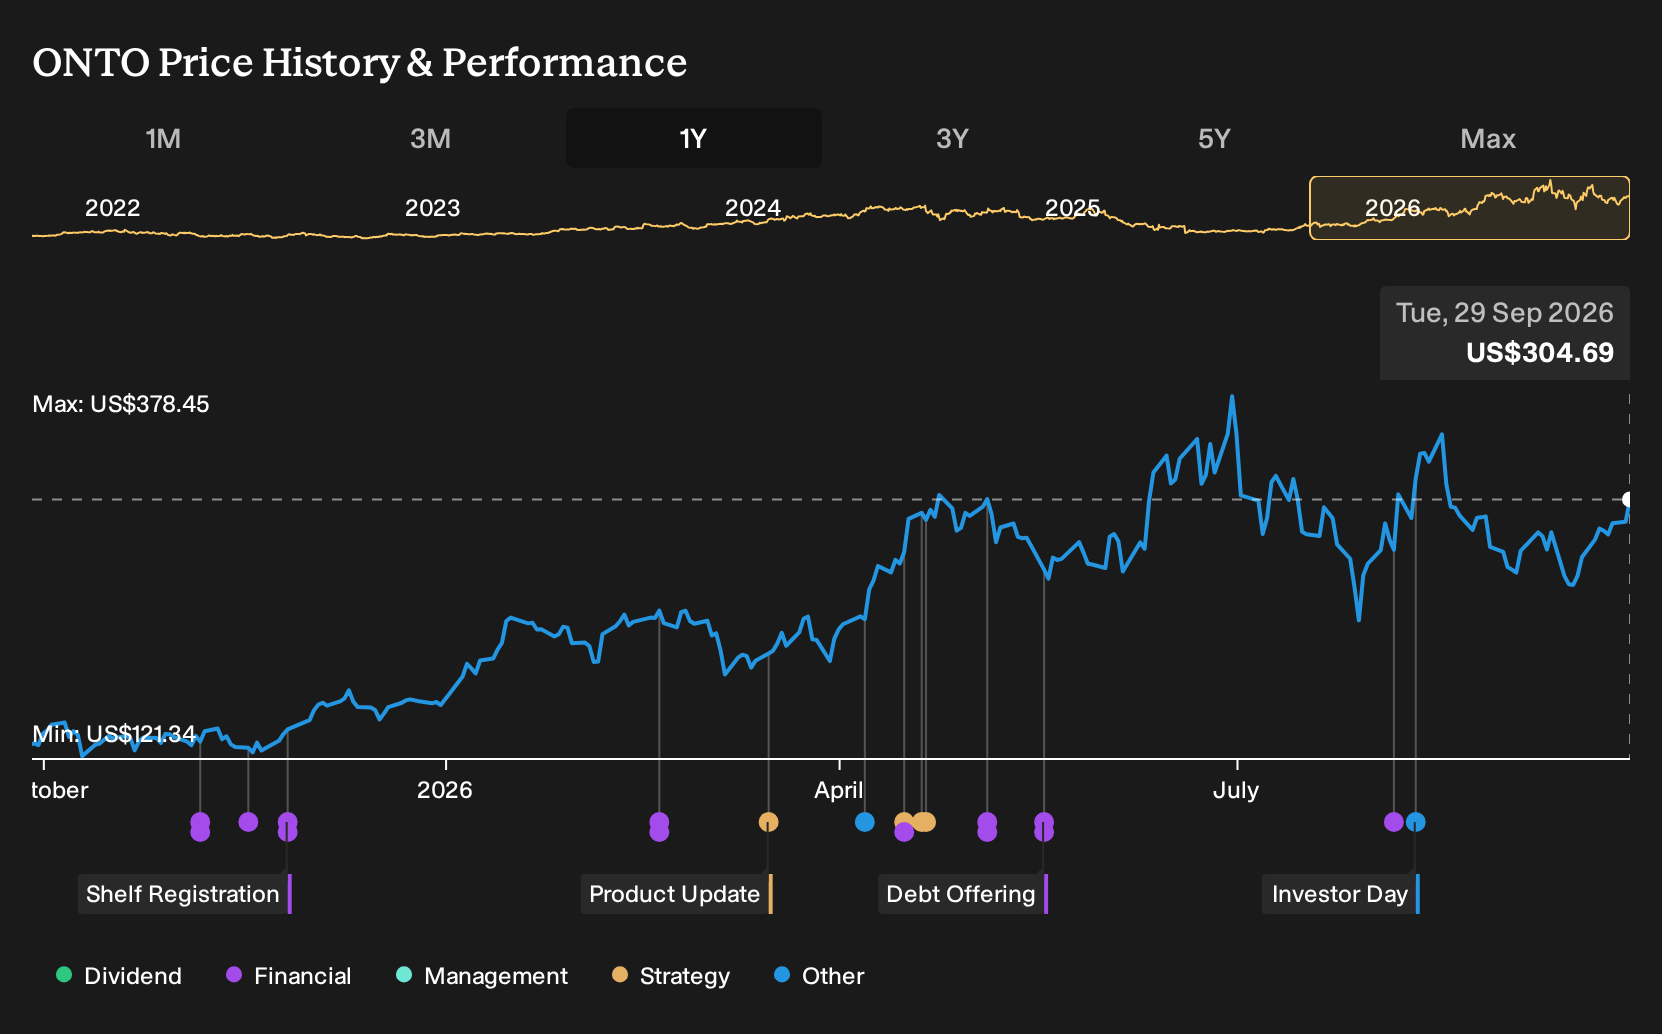
If you had chosen Onto Innovation on 29 September 2025, as analysts argued over whether AI packaging momentum or tariff and customer risks would matter more, your patience was tested more than once. Holding Onto Innovation over the past year would have returned 135.8%, including dividends. With record 2026 results, a major Rigaku stake, and even a fiduciary probe now on the table, which of those early trade offs should matter most to you today?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Onto Innovation has already moved. Pinpoint other ways to investigate the theme among 88 AI infrastructure stocks.
The Argument Onto Innovation Investors Were Really Having
The shares cost US$130 at the start of the period, so any decision on Onto Innovation began with whether that price already captured the AI packaging story or not.
The bullish Narrative put Fair Value at US$182. It leaned on the Dragonfly platform and Semilab acquisition supporting recurring revenue, higher margins, and a P/E of 28.3x on assumed 2028 earnings of US$352.9 million.
The bearish Narrative set Fair Value at US$90. It focused on rising operating costs from tariffs and regulation, tougher competition in metrology tools, and a lower assumed P/E of 15.9x on the same earnings figure.
What The Results Changed For Onto Innovation
Onto Innovation’s Rigaku stake turned the original debate toward scale. The US$720 million spend and deeper X-ray partnership backed the bullish view that product breadth and process control depth could matter more than tariff drag. Q2 2026 results added weight, with revenue at US$343.1 million and net income at US$60.1 million, taking net margin to 17.5%. The evidence cut both ways because valuation concerns persisted in later coverage.
The useful checkpoint for a future Onto Innovation type decision is simple. When a thesis hangs on higher quality earnings, track whether margin and cash going into acquisitions move together or pull apart in subsequent reported numbers.
What Onto Innovation’s Price Now Assumes
Onto Innovation trades at US$305 today after a 135.8% gain over the past year. The selected Narrative argues that Fair Value still sits above this level, framed around AI packaging bottlenecks rather than a simple semiconductor equipment cycle.
In that view, today’s price still underplays how entrenched Onto Innovation could become in advanced packaging inspection as AI workloads scale.
"Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Onto Innovation’s Demand Flows Next
Onto Innovation helps measure and inspect. Something else quietly keeps that work busy.
Every new chip, package, or AI workload needs more digital plumbing. Data must move quickly, reliably, and with tight control.
Another large infrastructure specialist builds that connective tissue, from networking hardware to private cloud software. Its customers care less about specific models and more about performance, reliability, and scale.
Those needs do not depend on which AI chip wins. They depend on whether data keeps growing and systems stay complex.
That argument has a Narrative and a number behind it. → See the company one Narrative values 83% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com