


Bond yields in the US just touched a 24 year high, which has made expensive growth stories harder for investors to get comfortable with. When money markets pay more, every dollar paid for future profits comes under tougher scrutiny. That is where overlooked tech stocks trading on lower valuations can start to look interesting. This article highlights three such opportunities from the undervalued technology screen.
The three undervalued tech stocks below are just a small sample from a much wider opportunity set, with the full screen surfacing 122 more companies that carry similarly compelling setups that are not covered here. To identify which of those ideas fit your risk profile and return goals, head straight into the Undervalued Tech screener to filter, analyze, and focus on the highest conviction plays.
Adobe (ADBE)
Overview: Adobe is a global software company that powers creative content production and enterprise customer experiences through its Creative Cloud and Experience Cloud platforms.
Operations: Adobe generates multi billion dollar revenue primarily from Europe, Middle East and Africa at US$7.1b and Asia-Pacific at US$3.6b.
Market Cap: US$89.9b
Adobe appears in this undervalued tech screen because its Experience Cloud sits in the flow of enterprise digital experience spending, while Creative Cloud supplies the content that feeds those high value customer journeys.
"Monetization Clarity: As "AI-first ARR" moves from $250 million toward the $1 billion mark, the market will stop viewing AI as a threat and start viewing it as a growth engine."
For investors watching Adobe, a quiet shift in how its AI features are actually paid for could start to reshape margins.
That margin story is only half the picture. The full narrative for Adobe unpacks how AI-first pricing, ecosystem stickiness and competitive pressure could be quietly reshaping Adobe’s risk reward profile.
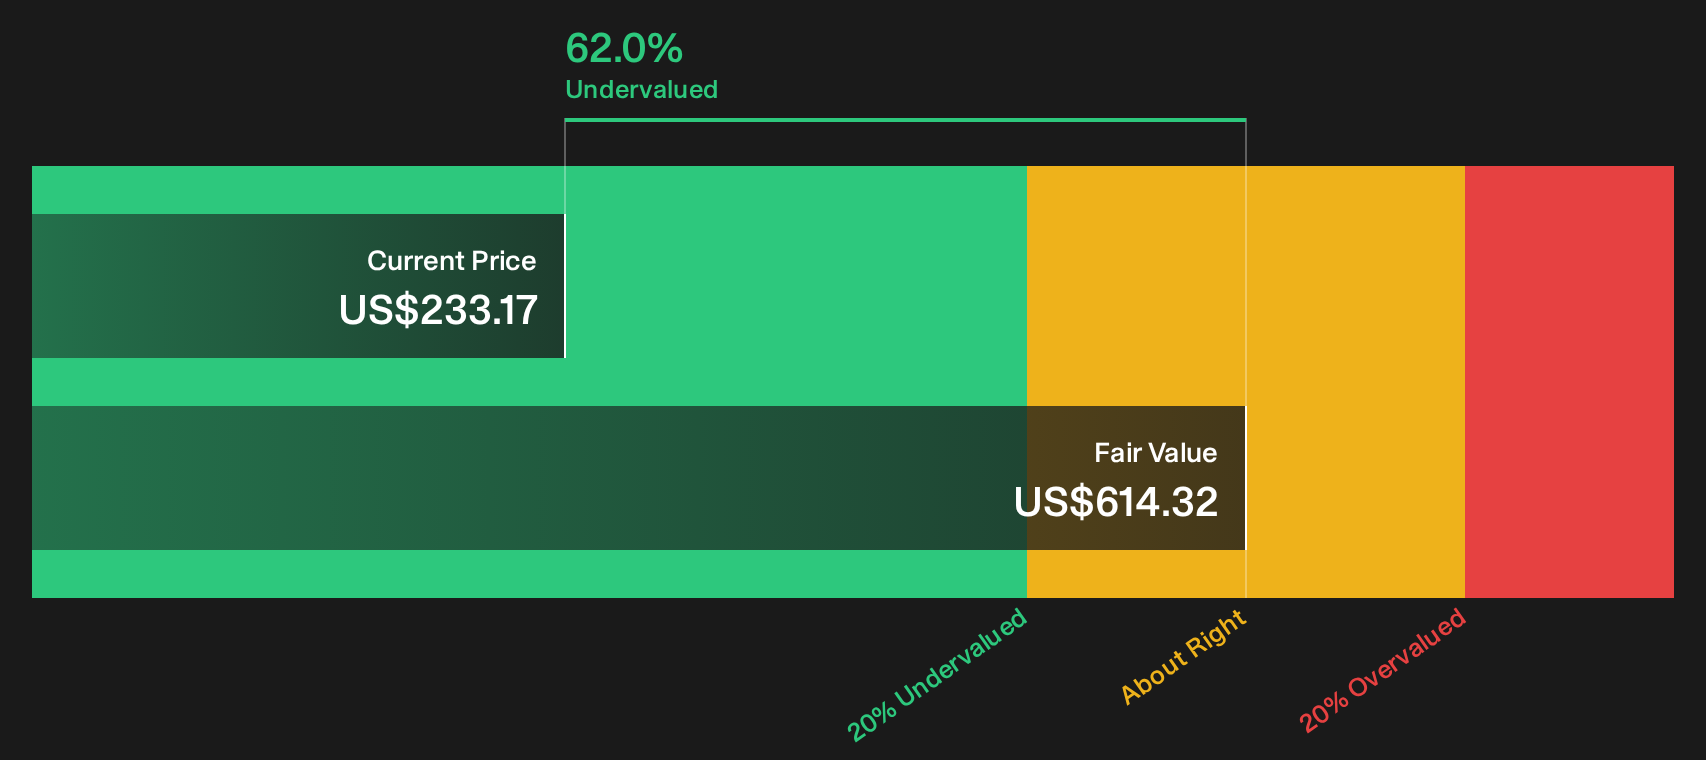
Broadcom (AVGO)
Overview: Broadcom designs semiconductor hardware for data centers and networking alongside infrastructure software, tying the business directly into the Undervalued Tech theme.
Operations: Broadcom generates US$59.4b from Semiconductor Solutions and US$29.7b from Infrastructure Software, with chips remaining the larger economic engine.
Market Cap: US$1,668.7b
Broadcom matters for this screen because its data center and networking chips turn rising AI and cloud demand into concrete hardware orders, while the software arm adds a second, more diversified earnings stream in the same digital infrastructure story.
"Broadcom benefits from growth in AI infrastructure, rising networking and bandwidth requirements, increasing data center complexity, greater demand for custom silicon solutions, and continued enterprise software monetization."
What happens if one quiet shift in where AI customers concentrate their long term hardware budgets changes the balance of that story?
If that budget shift is what you are watching, the full narrative for Broadcom outlines how Broadcom’s AI demand, bargaining power and cash generation could be quietly decoupling.

Intuit (INTU)
Overview: Intuit provides QuickBooks cloud software and related tools that help small and midsize businesses manage finances, payroll, payments, taxes, and marketing.
Operations: Intuit generates US$12.9b from Global Business Solutions and US$8.6b from Consumer, with US$19.7b of revenue primarily from the United States.
Market Cap: US$72.0b
Intuit matters for an Undervalued Tech lens because QuickBooks is a recurring cloud platform that plugs directly into how smaller firms run their financial lives.
"Intuit is now trying to close that exit door. The Intuit Enterprise Suite, launched recently, is designed for mid-sized businesses that need multi-entity accounting, more sophisticated reporting, and workflow automation, but do not want the cost and complexity of a full enterprise system."
The real lever is what happens to Intuit’s growth and pricing power if one quiet shift in customer adoption trends accelerates.
If that acceleration risk is what you care about, the full narrative for Intuit explains how Intuit’s Enterprise Suite could turn rising complexity into stickier revenue and stronger pricing power.

Seeking Fresh Alternatives Before They Fly
Markets move fast, and the most interesting ideas often gain momentum quietly before the crowd notices. Scan fresh stock sets while information still matters and aim to get in early.
- Track dependable income streams and target companies in the 6 dividend fortresses that aim to keep paying investors even when growth stories fall out of favor.
- Spot early movers in automation trends and work through the curated 93 robotics and automation stocks before industrial robotics demand becomes fully reflected in prices.
- Review the hand picked 39 power grid technology and infrastructure stocks to explore companies connected to potential power upgrade cycles while these infrastructure plays remain relatively less followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com