


Cloud computing and cybersecurity firm Akamai Technologies (AKAM) may have just changed its narrative by teaming up with a top artificial intelligence start-up.
Akamai announced an $11.6 billion, seven-year agreement with Anthropic, the AI company behind Claude. Anthropic will use Akamai Cloud’s infrastructure and software to support its rapidly growing CPU workloads. And the deal could nearly double in size—a provision allows the agreement to expand by another $9 billion, bringing the potential commitment to roughly $20 billion. Akamai also issued Anthropic warrants that could ultimately represent roughly 5% of its outstanding shares. About 2% is tied to the initial commitment, with additional warrants vesting as Anthropic expands its spending.
“Anthropic is advancing the AI revolution, and we are thrilled they chose Akamai’s capabilities for building and operating AI infrastructure at scale,” Akamai CEO Tom Leighton said. “Akamai has an unparalleled reputation for helping our customers achieve their business-critical goals and build the future. Our expanding global footprint, combined with our years of experience serving the world’s largest enterprises, positions us to be the infrastructure provider for secure and responsible AI applications and workloads.”
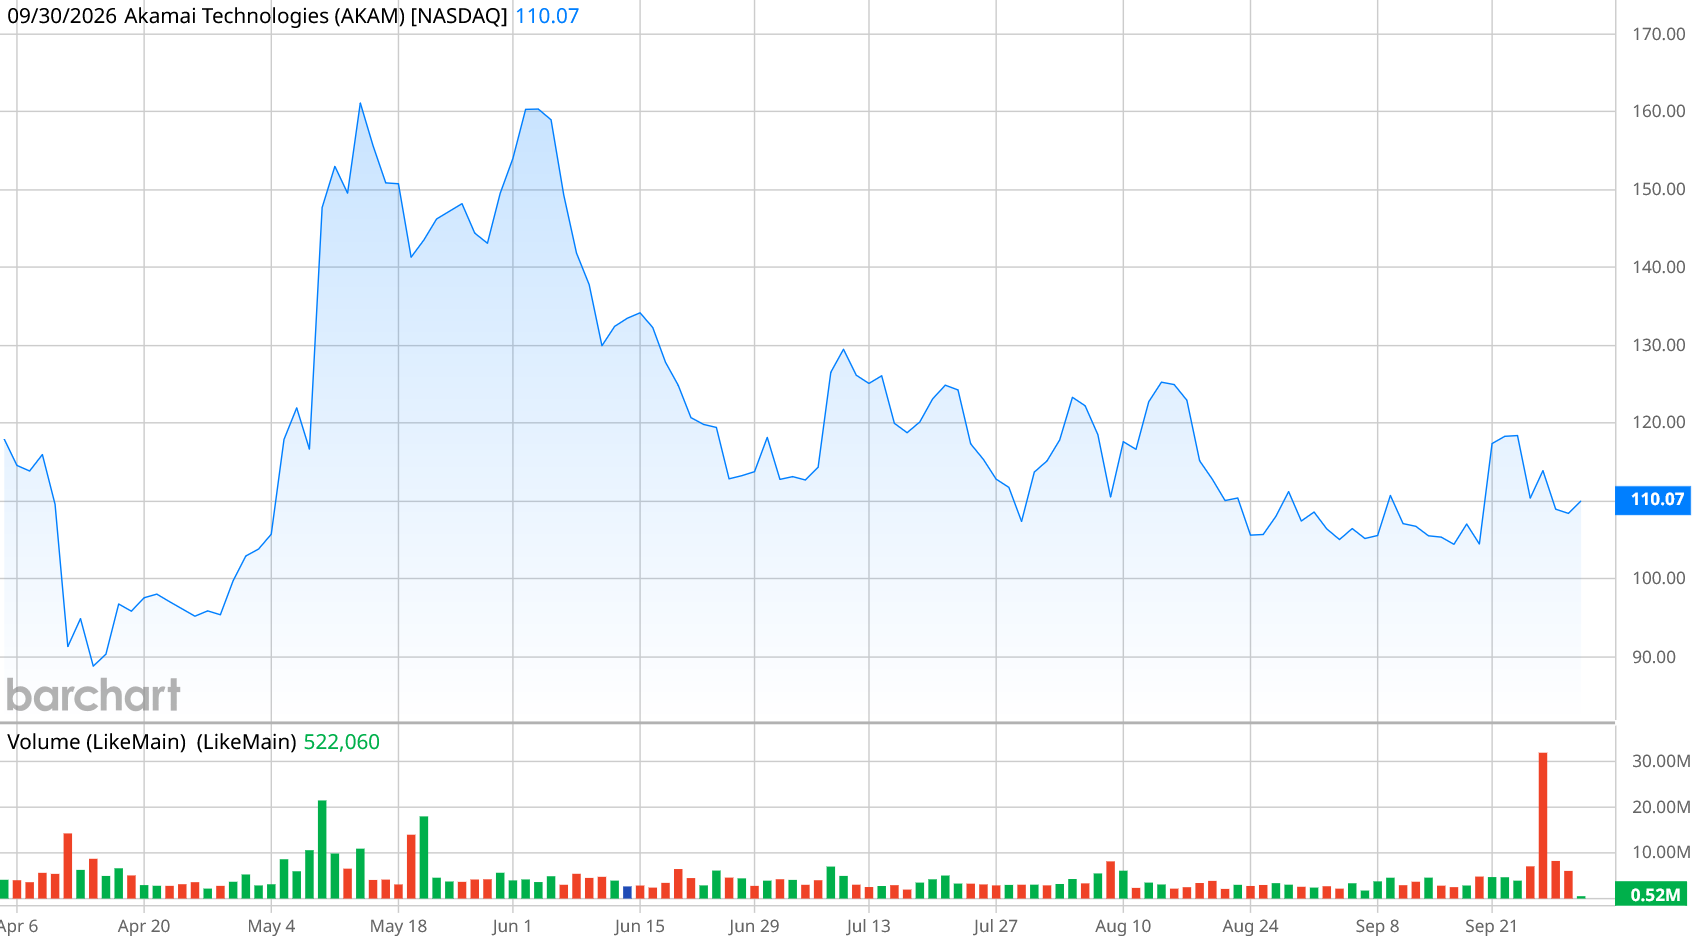
Akamai had already announced more than $2.8 billion in multi-year cloud infrastructure commitments this year, so the Anthropic deal suggests its efforts to expand into AI infrastructure are gaining traction. Shares jumped by more than 20% following last week’s announcement.
About Akamai Stock
Akamai has been around for nearly 30 years. The Massachusetts-based company got its start supplying content delivery networks (CDNs), placing servers close to users so websites and videos download or stream faster. It also developed a security business to help companies protect websites, applications, APIs, and corporate networks from cyberattacks. The company’s cloud computing operation, which is vying for market share in a field dominated by Amazon (AMZN), Microsoft (MSFT), and Alphabet’s (GOOG) (GOOGL) Google in providing computing, storage, database, and networking services.
Shares are up 45% in the last year, more than double the gain of the S&P 500 ($SPX). And shares are historically affordable right now—AKAM stock trades at a forward price-to-earnings ratio of 17.1, which is substantially below the stock’s five-year forward P/E mean of 28.9.
Beats on Earnings
Akamai’s most recent results topped Wall Street’s consensus expectations. For the second quarter, the company reported adjusted earnings of $1.59 per share, 1 cent above the consensus estimate, while revenue rose 5% from a year ago to $1.10 billion, ahead of the $1.09 billion analysts expected. However, adjusted EPS declined 8% from $1.73 in the year-ago period.
Management noted that security revenue increased 10% to $604 million, while cloud infrastructure services revenue jumped 39% to $99 million.
For the third quarter, Akamai guided for adjusted EPS between $1.60 and $1.80, compared with the $1.70 consensus estimate. Revenue is expected to range from $1.105 billion to $1.13 billion, with the midpoint falling below Wall Street’s $1.132 billion forecast. For the full year, management expects adjusted EPS of $6.40 to $7.05 versus the $6.71 consensus, while its $4.445 billion to $4.53 billion revenue forecast brackets analysts’ $4.502 billion estimate.
As part of the $2.8 billion worth of multi-year cloud infrastructure services contracts year-to-date (YTD), Akamai signed a new agreement worth more than $600 million over four years with an unnamed U.S. technology company to support robotics development. Akamai expects its cloud infrastructure services revenue to grow at least 50% in constant currency for the full year, but the company will also take on significant capital expenditures, including $5.5 billion in new capex related to the newly announced Anthropic deal. About $1.7 billion of that will be realized in the fourth quarter of this year.
What Do Analysts Expect for AKAM Stock?
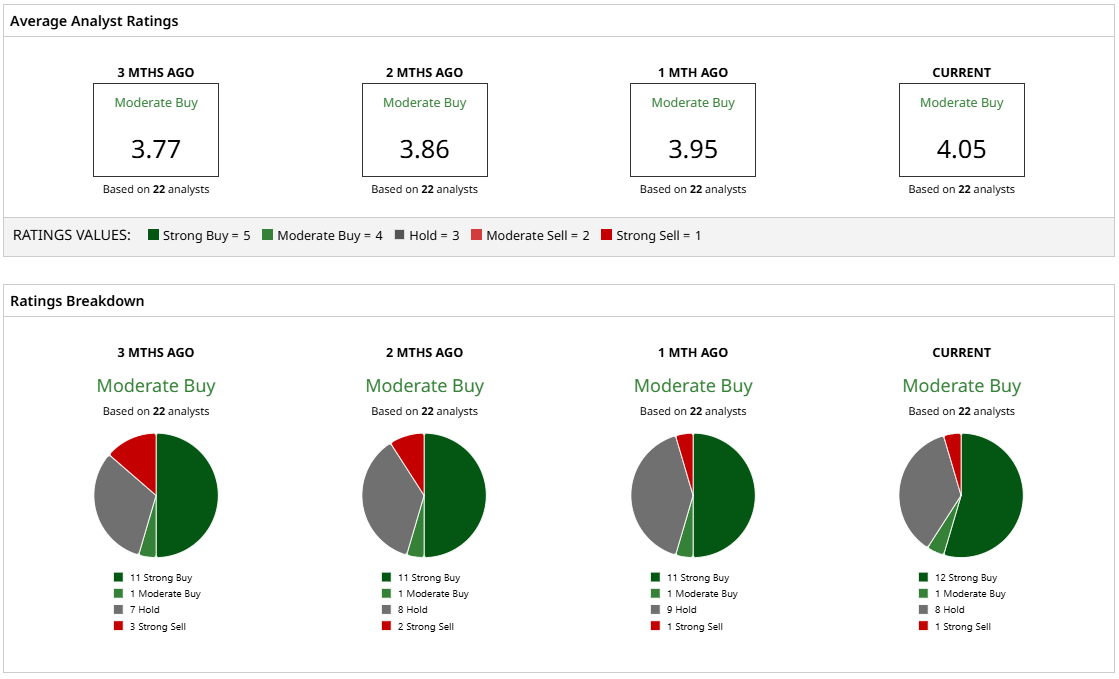
Wall Street has become increasingly bullish on Akamai. Of the 22 analysts tracked by Barchart, 13 have “Buy” ratings and only one recommends selling, with the rest maintaining “Hold” ratings.
Analysts also see considerable room for AKAM stock to run. The mean price target of $158.05 represents a potential upside of 44%.
While Akamai has considerable potential, the bigger question for investors is whether Anthropic represents a one-off blockbuster customer or proof that Akamai can become a meaningful AI infrastructure provider. If additional customers follow, the $11.6 billion agreement could look less like a big contract and more like the beginning of a very different Akamai.
On the date of publication, Patrick Sanders did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.