


- Lumentum Holdings announced AI focused optical interconnect and external laser module demonstrations with Qualcomm Technologies and Corning at ECOC 2026, featuring high density die to die links and an eight wavelength DWDM ELSFP module aligned with OCI MSA requirements.
- The demonstrations highlight how Lumentum Holdings is applying its high volume 3D sensing and Ultra High Power laser platforms to AI scale up architectures, linking advanced packaging, co packaged optics, and high fiber density into one coherent product story.
- This article examines how Lumentum Holdings' AI focused optical interconnect work with Qualcomm and Corning may influence the existing investment narrative.
Scan how Lumentum Holdings fits into the broader AI hardware buildout by comparing it against 88 AI infrastructure stocks powering the next wave of bandwidth hungry data centers.
Lumentum Holdings Investment Narrative Recap
For a shareholder, a key belief in Lumentum Holdings is that AI and cloud customers will continue to rely on high performance photonics, and that the firm can translate this demand into profitable, less constrained operations. The short term swing factor still lies in execution on capacity ramps and product mix, especially given current losses of US$6.9b on US$3.0b of revenue.
The biggest risk remains dependency on a small set of hyperscale buyers, combined with lower margin cloud modules and a price-to-sales multiple of 29x. The ECOC 2026 demos help Lumentum refine its AI narrative but do not, by themselves, alter that near term risk-reward balance.
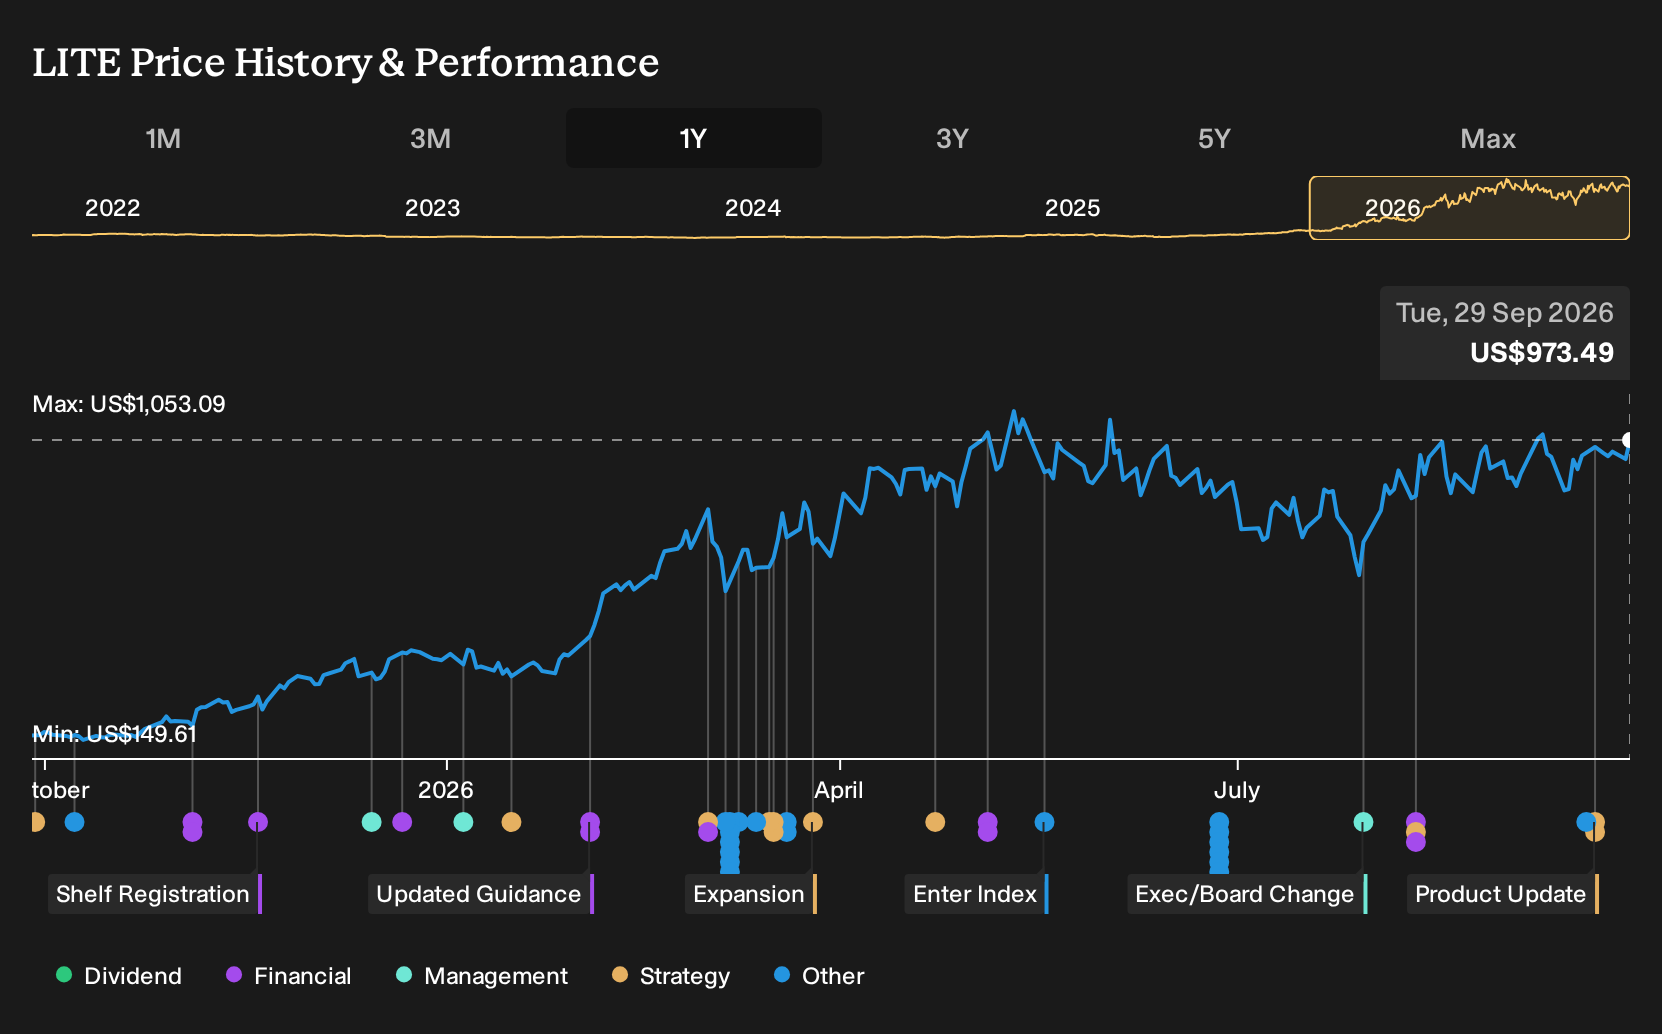
The most relevant update for this story is the planned ECOC 2026 die-to-die optical interconnect showcase with Qualcomm Technologies and Corning. It ties directly into the AI scale-up thesis, since it focuses on extending chip-to-chip links over optical media while aiming to keep latency and power usage under control in dense systems.
As a potential catalyst, this proof of concept relies on Lumentum Holdings’ 1060 nm VCSEL engine, its 3D sensing manufacturing base, and Corning’s high density fiber, which together target high shoreline bandwidth for future CPO and NPO designs. The key operational factor is whether these platforms convert into repeat orders from a concentrated hyperscaler base rather than remaining showcase technology.
Lumentum Holdings' current analyst storyline points to forecast revenues of US$12.7b and earnings of US$4.4b by 2029, which implies revenue growth of 61.3% per year and an earnings swing of US$11.3b from today’s loss of US$6.9b.
Uncover how Lumentum Holdings' fair value indicates an 18% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate view focuses on margin pressure instead of headline AI demand. The most cautious analysts worry that hyperscale buyers could keep pricing tight, even if Lumentum’s ECOC 2026 demos win technical praise. Before this news, that group was only penciling in about US$11.1b of 2029 revenue and US$4.2b of earnings. That is far more conservative than the top end of forecasts, and it shows how sharply opinions can differ. Use this spread in expectations as a prompt to explore several narratives, and then decide which assumptions feel closest to your own.
Explore 8 other Lumentum Holdings fair value estimates, including one that suggests as much as 9% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lumentum Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lumentum Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lumentum Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Lumentum Holdings?
If this Lumentum Holdings story has sharpened your thinking on AI and optical hardware, it can be useful to compare it with other businesses that fit very different profiles. Use the Simply Wall St Screener to quickly surface a wider watchlist that suits your risk tolerance and income goals.
- For investors who care most about balance sheet strength and fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying on aggressive financing.
- If you are hunting for mispriced quality, scan a 32 high quality undervalued stocks where cash flows and balance sheets do more of the talking than headlines.
- Income focused investors can focus on stability and yield by reviewing a 6 dividend fortresses that aims to combine payout strength with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com