


Microchip Technology (MCHP) moved on the back of fresh product news, after it expanded its 10BASE-T1S Ethernet portfolio with new PMD transceivers and integrated endpoint devices targeting automotive, industrial and robotics connectivity.
For context, Microchip Technology shares trade at US$78.78, with recent product launches tied to Ethernet and power monitoring arriving against a mixed backdrop. The 30-day share price return of 8.02% and year-to-date gain of 21.14% contrast with a 90-day decline of 11.17%, while the 1-year total shareholder return of 25.89% points to momentum that has cooled in the short term but remains constructive over a longer horizon.
Scan how Microchip Technology’s Ethernet and power-monitoring themes play out across other listed players with our curated 89 AI infrastructure stocks for data and connectivity hardware leveraged to AI workloads.
Microchip Technology appears to be a solid embedded control and connectivity business, and the latest Ethernet move underlines that. The key question for investors is whether the current US$78.78 price fairly reflects that strength.
Most Popular Narrative: 27% Undervalued
Compared with Microchip Technology’s last close at $78.78, the most followed narrative sets a fair value of $108.64, which suggests a wide gap that depends on how data center, AI and aerospace demand convert into orders over time.
Microchip Technology is seeing structural expansion in data center and AI infrastructure exposure, with total data center revenue expected to increase from about US$591 million in 2025 to roughly US$1 billion in 2026 and PCIe Gen6 design wins, including an estimated US$100 million annual program starting in 2027, which together point to a larger contribution to future revenue.
See why 53 investors see Microchip Technology as 27% undervalued.
Result: Fair Value of $108.64 (UNDERVALUED)
Still, Microchip Technology’s story can break if elevated inventories drag on margins for longer than expected or if external foundry constraints choke off high demand programs.
Find out about the key risks to this Microchip Technology narrative.
Another View: Microchip Technology On Earnings Multiples
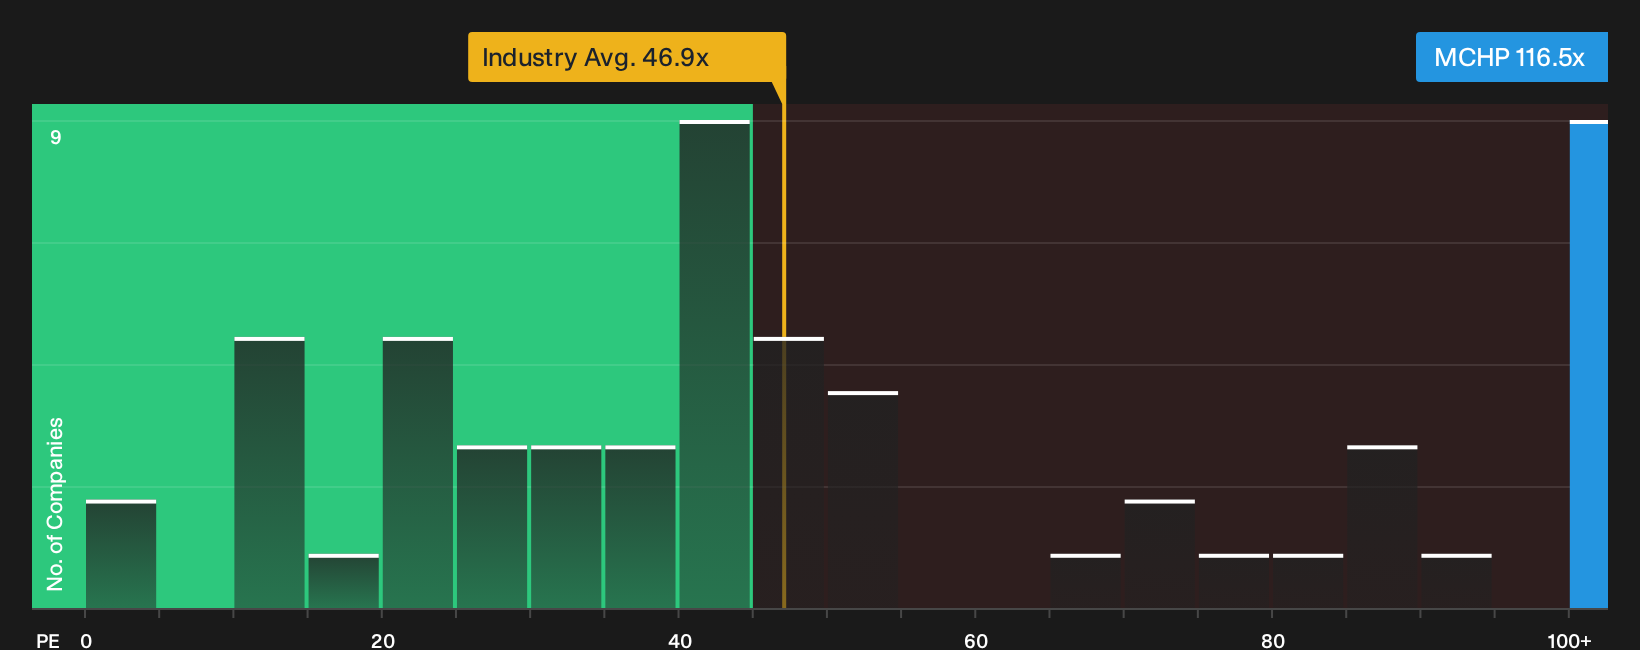
The analyst narrative presents Microchip Technology as undervalued at a fair value of $108.64, yet the current P/E of 116.5x tells a different story. That multiple is far above the fair ratio of 35.9x and also well above the US Semiconductor industry at 46.9x and the peer average at 67.9x.
Such a gap means buyers today are paying a substantial premium for every dollar of current earnings. Any disappointment in future delivery could affect sentiment significantly. If the story develops as expected, do you think the market moves closer to the analyst fair value or back toward the fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around Microchip Technology feels familiar, treat it as a prompt to inspect the numbers yourself and move quickly to form your own view while the debate is active, then weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Microchip Technology?
If you only focus on Microchip Technology, you could miss other setups with cleaner balance sheets, different risk profiles and income potential that complement your portfolio.
- Zero in on financial resilience by scanning a curated list of solid balance sheet and fundamentals (25 results) that highlights businesses built on stronger funding and liquidity foundations.
- Hunt for mispriced opportunities using our focused 32 high quality undervalued stocks to spot companies where fundamentals and current prices diverge meaningfully.
- Build a pay-you-while-you-wait approach with the targeted 6 dividend fortresses and focus on higher yielding stocks that still screen for strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com