


- BWX Technologies recently held an Investor Day for analysts and institutional investors, with management outlining current business priorities, strategic direction and updated medium term financial targets, followed by a live question and answer session.
- The detailed discussion of medium term targets at BWX Technologies’ Investor Day gives investors fresh context for assessing its contract driven nuclear and defense backlog and capital allocation choices.
- We will look at how BWX Technologies’ investment narrative is shaped by the fresh medium term targets unveiled at Investor Day.
BWX Technologies Investment Narrative Recap
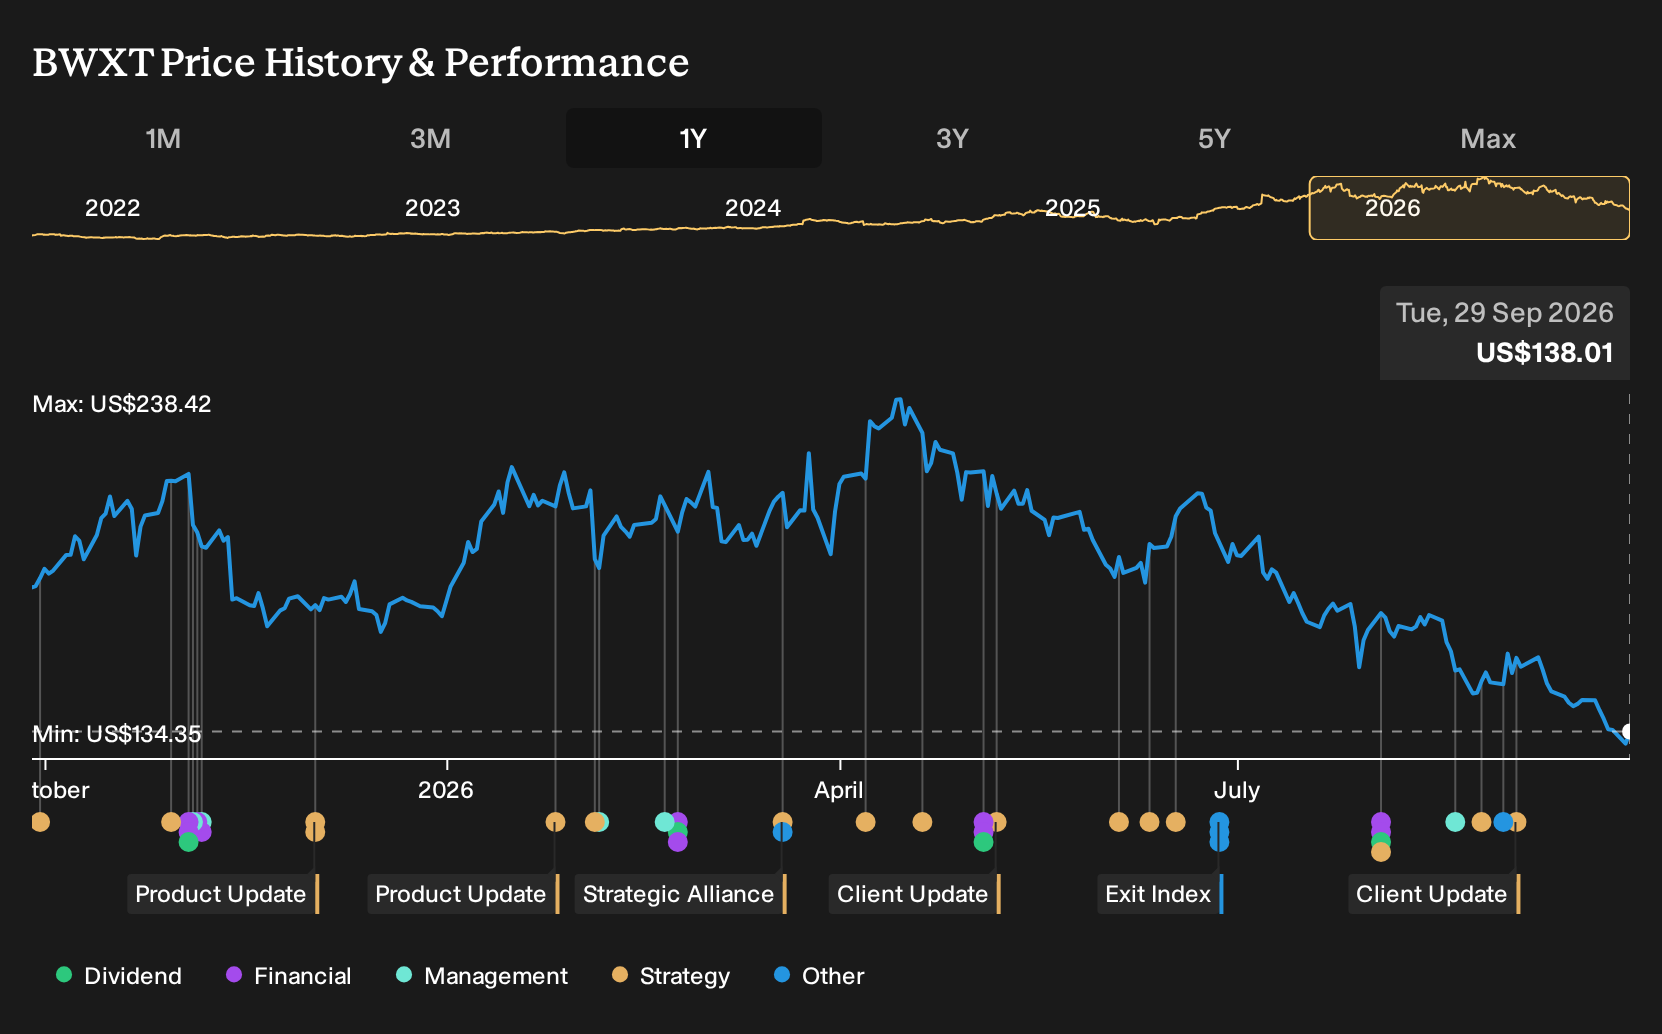
To own BWX Technologies, you need to be comfortable with a business that leans heavily on long duration government and Navy contracts, along with a growing civil nuclear and medical footprint. The central belief is that a record backlog and exposure to nuclear infrastructure can support steady work even when day to day trading is volatile, as recent share price pressure has highlighted.
The key near term swing factor is how efficiently that backlog converts into revenue and profit, especially in the commercial segment where margins have been under strain. The main risk remains dependence on U.S. defense budgets and procurement cycles. The Investor Day targets primarily frame these issues rather than changing them in a material way.
The most relevant disclosure tied to this Investor Day is management’s refreshed medium term financial targets, which are built on BWX Technologies’ roughly 6b backlog and recent multi year Navy propulsion awards worth more than 4.7b. That context matters if you are tracking how the company balances growth projects in microreactors, advanced fuels and services with capital intensity and debt.
Those contracts and the enlarged opportunity set in areas such as CANDU life extensions, SMRs and medical isotopes shape both the potential upside and the execution risk. They can support higher margin work and earnings growth, but also increase exposure to regulatory change, workforce constraints and renewals at the end of those long contracts.
BWX Technologies Analyst Assumptions in Focus
Analysts currently bake in a 9.8% yearly increase in BWX Technologies revenue over the next three years, alongside a move in profit margins from 10.1% today to 11.4% by year three. The same group expects earnings to reach US$531.6 million, or US$6.05 per share, by about 2029, compared with US$355.2 million today. That earnings path implies an increase of roughly US$176 million from current levels. Consensus models in the report also assume a modest 0.21% annual lift in the share count and apply a discount rate of about 8.2% to translate those future cash flows into a present value view.
BWX Technologies' narrative projects US$4.7b revenue and US$531.6 million earnings by 2029. This implies 9.8% yearly revenue growth and an earnings increase of about US$176 million from current earnings of US$355.2 million.
Valuation expectations tie directly into these forecasts. To line up with the analyst case, an investor would need to assume that by 2029 BWX Technologies delivers the US$4.7b in revenue and US$531.6 million in earnings cited in the report and that the stock trades on a P/E of 51x those earnings, compared with 40.2x today and a reported 36x for the broader U.S. aerospace and defense peer group. The same summary flags a consensus target price of US$232.31 versus a current share price reference of US$155.67, with the most optimistic forecast at US$290.00 and the lowest at US$170.00, which underlines that professional views on how the story plays out remain quite spread.
Uncover why BWX Technologies' fair value indicates a 68% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts policy risk front and center for BWX Technologies. The most cautious analysts worry that tougher nuclear regulation or pro renewables policies could slow new projects, so they only pencil in US$4.4b revenue and US$513.2 million earnings by 2029. That is more restrained than consensus and could shift once Investor Day details are absorbed.
Explore 7 other BWX Technologies fair value estimates, including one that suggests there may be as much as 5% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your BWX Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BWX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BWX Technologies' overall financial health at a glance.
Looking for more BWX Technologies investment ideas?
If the BWX Technologies story has your attention but you want a wider field of options, the Simply Wall St Screener can help you quickly sort through companies that fit different risk and return profiles.
- For readers who want value and quality in the same package, sort through a curated set of 32 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If capital preservation matters as much as upside, you can filter for 32 resilient stocks with low risk scores to see companies that show more resilient risk profiles based on the data Simply Wall St tracks.
- To hunt for potential future leaders that are not yet widely followed, scan a focused group of 17 high quality undiscovered gems that pair solid financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com