


Parker-Hannifin (PH) has drawn fresh attention after recent share moves that left the stock down about 2% over the past month while still showing a gain year to date.
Viewed over a longer stretch, Parker-Hannifin’s recent 2% dip over the past month sits against a steadier backdrop, with an 8.54% year-to-date share price return and a 29.06% one-year total shareholder return. This suggests that momentum has cooled slightly but remains supportive in the bigger picture.
Scan Parker-Hannifin alongside a hand-picked 39 power grid technology and infrastructure stocks benefiting from long-term electrification and infrastructure spending themes.
The recent pullback in Parker-Hannifin could be read as investors cooling on the story rather than the business, so how does that tension show up in the current valuation numbers?
Most Popular Narrative: 16.6% Undervalued
Parker-Hannifin’s most followed narrative pegs fair value at about $1,163 per share, above the recent $970.37 close. This frames the latest pullback as a move against a still-supportive long term story built on margins and aerospace exposure.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 46 investors see Parker-Hannifin as 17% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, the Parker-Hannifin story can wobble if slower organic growth persists or if the premium P/E and insider selling start to weigh on sentiment.
Find out about the key risks to this Parker-Hannifin narrative.
Another View On Parker-Hannifin’s Valuation
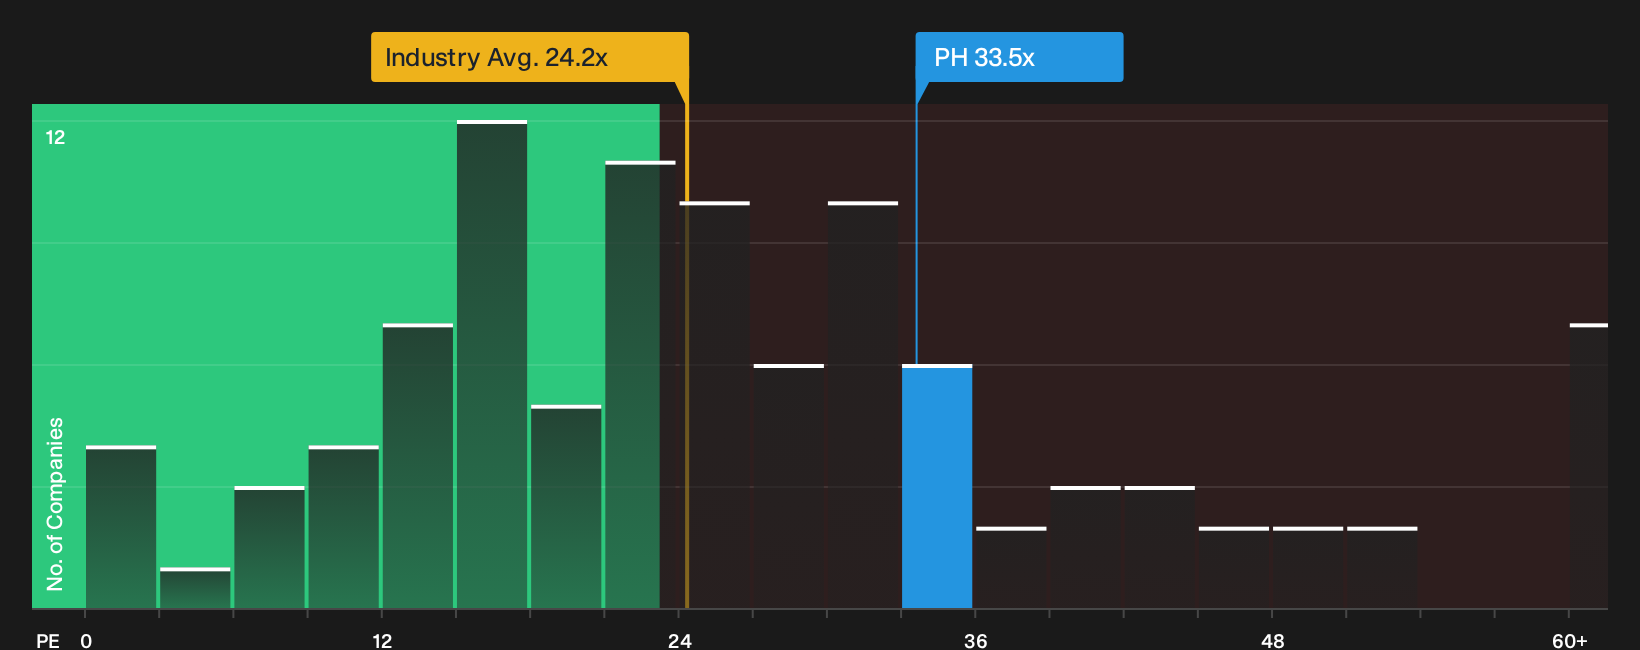
The narrative fair value suggests Parker-Hannifin is 16.6% undervalued, yet the market is already paying a P/E of 33.5x. That is above both the estimated fair ratio of 30x and the US Machinery peer average of 24.2x. If sentiment cools, how much room is there for that multiple to compress before returns feel the impact?
To see how this pricing gap looks through earnings ratios and what it might mean for future valuation swings, take a look at our breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about how Parker-Hannifin stacks up after this pullback and premium P/E? Act while sentiment is still forming, and weigh the upside against the downside yourself by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Parker-Hannifin style investment ideas?
If Parker-Hannifin has you thinking about quality, do not stop with a single ticker. Use the Simply Wall St Screener to quickly surface fresh opportunities before other investors move.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results), which can help anchor a more defensive part of your portfolio.
- Hunt for potential mispriced opportunities by reviewing a focused set of 32 high quality undervalued stocks that combine strong cash generation with cleaner financials.
- Spot ideas that others may be overlooking by zeroing in on 17 high quality undiscovered gems that pair quality fundamentals with relatively low current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com