


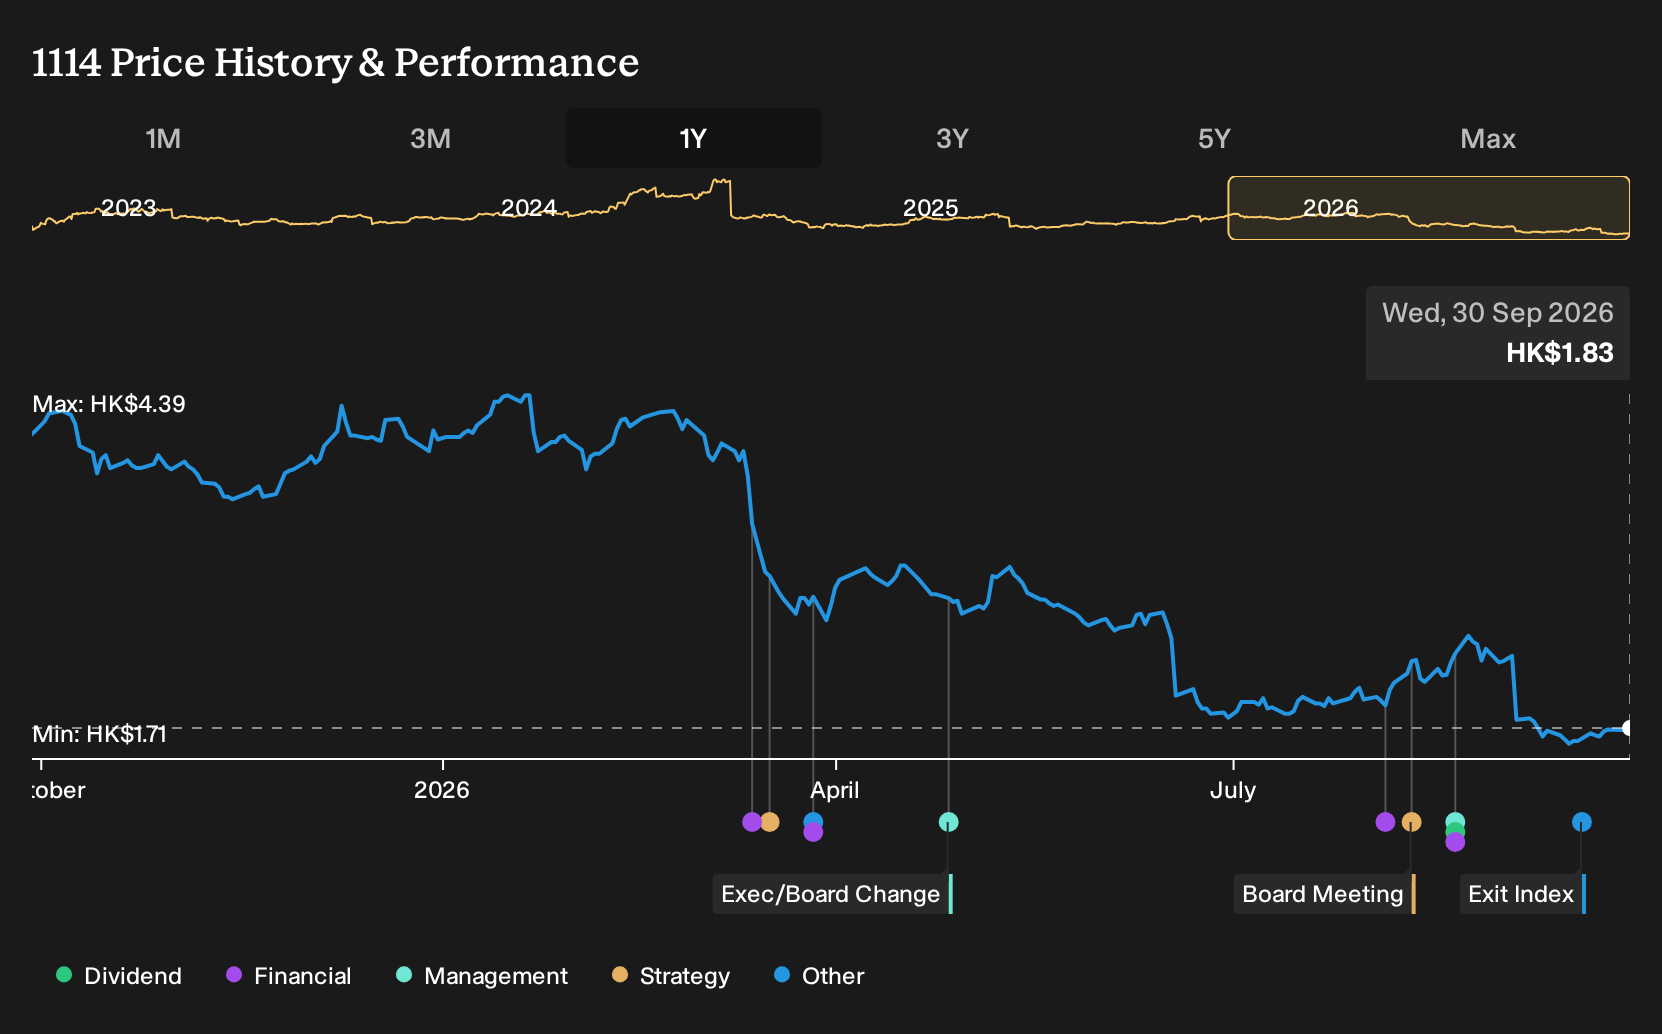
- Brilliance China Automotive Holdings was removed from the FTSE All-World Index in September 2026. As a result, many passive funds that track this benchmark can no longer hold the stock as part of their index-linked portfolios.
- The index exit highlights how benchmark status can influence liquidity and investor access. This can affect how easily Brilliance China Automotive shares trade and how the market perceives the business over time.
- This article examines how Brilliance China Automotive's investment narrative is affected by the FTSE All-World Index removal and related trading shifts.
Broaden your watchlist beyond Brilliance China Automotive by scanning our hand picked 189 high quality undervalued stocks, which currently sit off the major indices but still meet strict quality tests.
What Is Brilliance China Automotive Holdings' Investment Narrative?
To own Brilliance China Automotive Holdings, you need to be comfortable with a fairly concentrated auto story. Most of the value sits in manufacturing and selling BMW vehicles and components through its BBA operations, backed by a long list of partnerships that span BMW, Renault, Toyota and major battery suppliers. Earnings are forecast to grow 13.73% a year while revenue is expected to rise 3.1% a year, so the thesis leans more on profitability than on aggressive top line expansion.
The FTSE All World exit mainly affects who can hold the stock, not how many cars roll off the line or what pricing looks like. Trading liquidity and short term sentiment can shift, yet the bigger near term swing factors still look operational. Recent share price performance has been weak, the dividend payout of 27.32% is not well covered, and profit margins of 82% are lower than last year. This puts more pressure on execution and capital allocation at Brilliance China Automotive Holdings.
Even so, there is one structural pressure point in this story that rarely gets top billing...
There's only one way to know the right time to buy, sell or hold Brilliance China Automotive Holdings. Head to Simply Wall St's company report for the latest analysis of Brilliance China Automotive Holdings's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider relying on your own judgment.
- A great starting point for your Brilliance China Automotive Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Brilliance China Automotive Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brilliance China Automotive Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Brilliance China Automotive?
If Brilliance China Automotive Holdings is already on your radar, it can help to widen the net and compare it with other companies that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener lets you do exactly that, by surfacing stocks that fit clear, fundamental criteria rather than headlines.
- Prefer lower volatility and steadier profiles over sharp swings? Filter for companies with resilient financials using our 226 resilient stocks with low risk scores and see which businesses match that temperament.
- If income is your focus, concentrate on companies that aim to sustain higher yields by scanning through our hand picked 156 dividend fortresses and weigh how each payout stacks up against your goals.
- If you want to uncover lesser known opportunities before they gain wider attention, run through our curated 616 high quality undiscovered gems and compare their fundamentals side by side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com