


G Mining Ventures (TSX:GMIN) has put fresh exploration results from Brazil in front of investors, with new drilling at Gurupi and Tocantinzinho pointing to longer mineralized zones and a new near surface gold find at Grodiocal.
G Mining Ventures has delivered these drill results against a backdrop where the share price has eased over the past month, with the 30 day share price return down 7.18%, the 90 day share price return up 12.38%, and the 1 year total shareholder return at 73.08%. This signals momentum that has built over a longer horizon even as short term sentiment cools.
Scan G Mining Ventures alongside other gold-focused plays by reviewing a curated set of 36 elite gold producer stocks that are also pushing fresh drilling and resource updates into the market.
Fresh drill hits on one side and a 7.18% pullback over 30 days on the other put G Mining Ventures at an interesting crossroads. Do the current fundamentals still stack up in favour of new buyers here?
Most Popular Narrative: 21.9% Undervalued
G Mining Ventures last closed at CA$48.48, while the most followed narrative sees fair value closer to CA$62.08, so the market price trails the valuation work that underpins the analyst consensus.
The company reports strong free cash flow from TZ and expects this cash flow to fund a large part of Oko West construction and a record exploration budget of about $46 million across the portfolio. This could support future revenue and free cash flow if new resources and projects move into production.
See why 11 investors see G Mining Ventures as 22% undervalued.
Result: Fair Value of CA$62.08 (UNDERVALUED)
Still, the narrative around G Mining Ventures can shift quickly if gold prices weaken for a long stretch or if Oko West capital spending overruns squeeze cash flow.
Find out about the key risks to this G Mining Ventures narrative.
Another View on G Mining Ventures Valuation
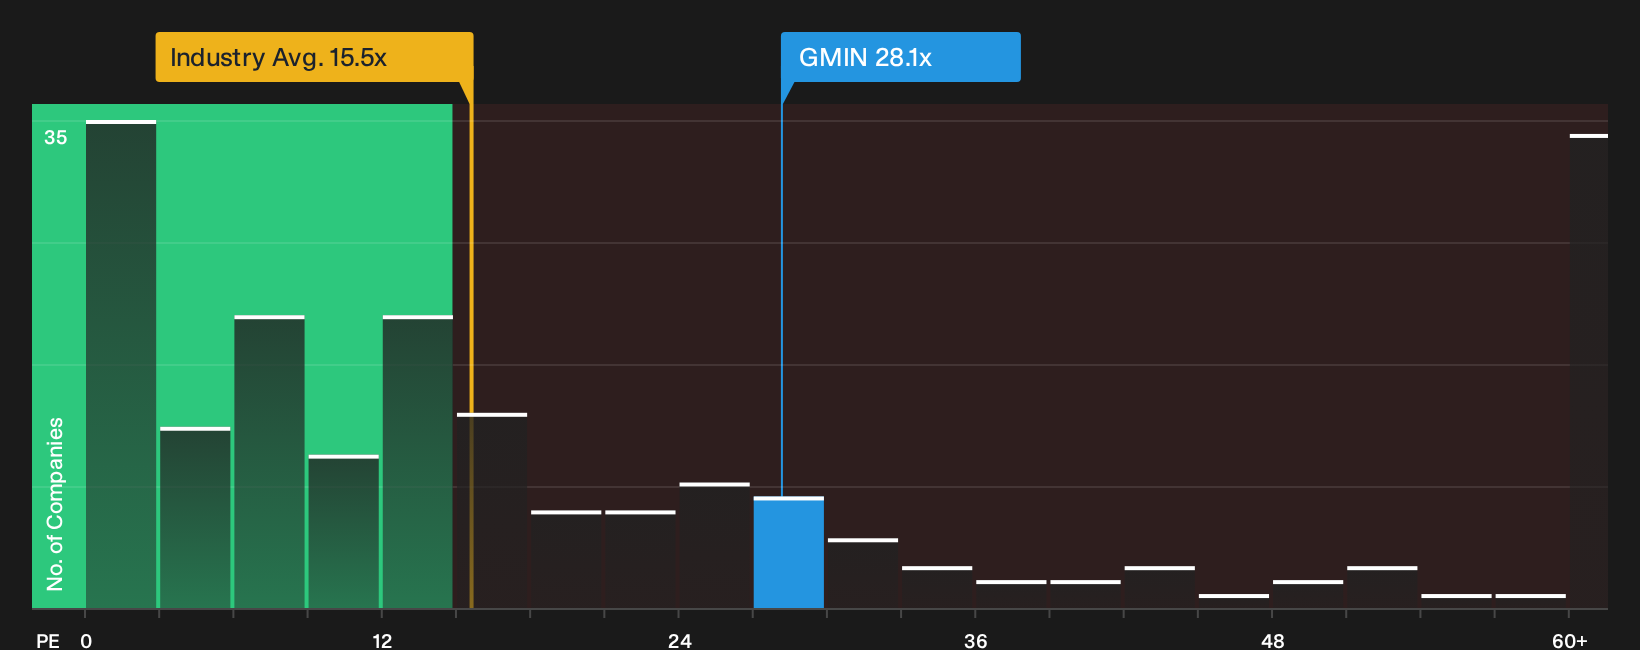
On one hand, G Mining Ventures screens as good value against internal fair value work, with the shares flagged as trading 63.6% below that estimate and also below a future cash flow value of CA$135.84. On the other hand, the current P/E of 28.1x looks expensive next to the Canadian Metals and Mining industry at 15.4x, its peers at 13.9x, and even its own 27.8x fair ratio. That kind of gap can indicate either meaningful upside if earnings deliver or a risk of the multiple compressing if the story cools.
To see how that richer P/E stacks up against profit quality, growth forecasts and peer comparisons in one place, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on G Mining Ventures or a clear setup in disguise? Act while sentiment is still split and weigh the upside against the concerns by checking the 4 key rewards and 3 important warning signs.
Ready for more investment ideas beyond G Mining Ventures?
If G Mining Ventures has your attention, do not stop here. Broaden your watchlist using focused stock ideas that match your risk appetite and return goals.
- Target potential mispricing by scanning a curated set of 6 high quality undervalued stocks that pair solid fundamentals with prices that still look beaten down by cautious sentiment.
- Build a steadier income stream by lining up 1 dividend fortresses that combine higher yields with balance sheets designed to shoulder ongoing cash payouts.
- Strengthen your defensive side by sorting through 7 resilient stocks with low risk scores that aim to limit surprises when markets turn choppy and headlines get noisy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com