


Australian inflation has accelerated to 4%, with the Reserve Bank pushing interest rates to a 15 year high of 4.6% as housing and transport costs bite. That jump in transport costs is closely tied to oil, which puts local energy exposure squarely on the radar. This article walks through three stocks from the global oil and gas producers list that could help you think more clearly about that theme.
The three producers below are just a starting sample, with the wider screen surfacing 21 more oil and gas companies worldwide that carry equally compelling narratives not covered here.
If you want to go deeper into this theme straight away, head into the Oil and Gas screener to identify, filter and analyze the highest conviction ideas that match your own view on risk and return.
Tamboran Resources (ASX:TBN)
Overview: Tamboran Resources is a Sydney based gas developer focused on unconventional natural gas projects across multiple permits in Australia's Beetaloo Basin.
Market Cap: A$2.0b
Tamboran Resources gives you direct exposure to Australian natural gas, with early production in the Beetaloo Basin starting to connect geology to real cash flows.
"Progress towards first gas from the Beetaloo Basin Pilot Area in the third quarter of calendar 2026, supported by an 88% complete compression facility and an APA owned pipeline in final commissioning, is expected to move Tamboran Resources from a pre revenue phase toward contracted gas sales."
Future returns will depend heavily on how a single capital intensive build out phase ultimately reshapes unit costs and pricing power.
If that capital heavy pivot is what interests you, read the full narrative for Tamboran Resources to see how Tamboran Resources could evolve as contracts and infrastructure mature.

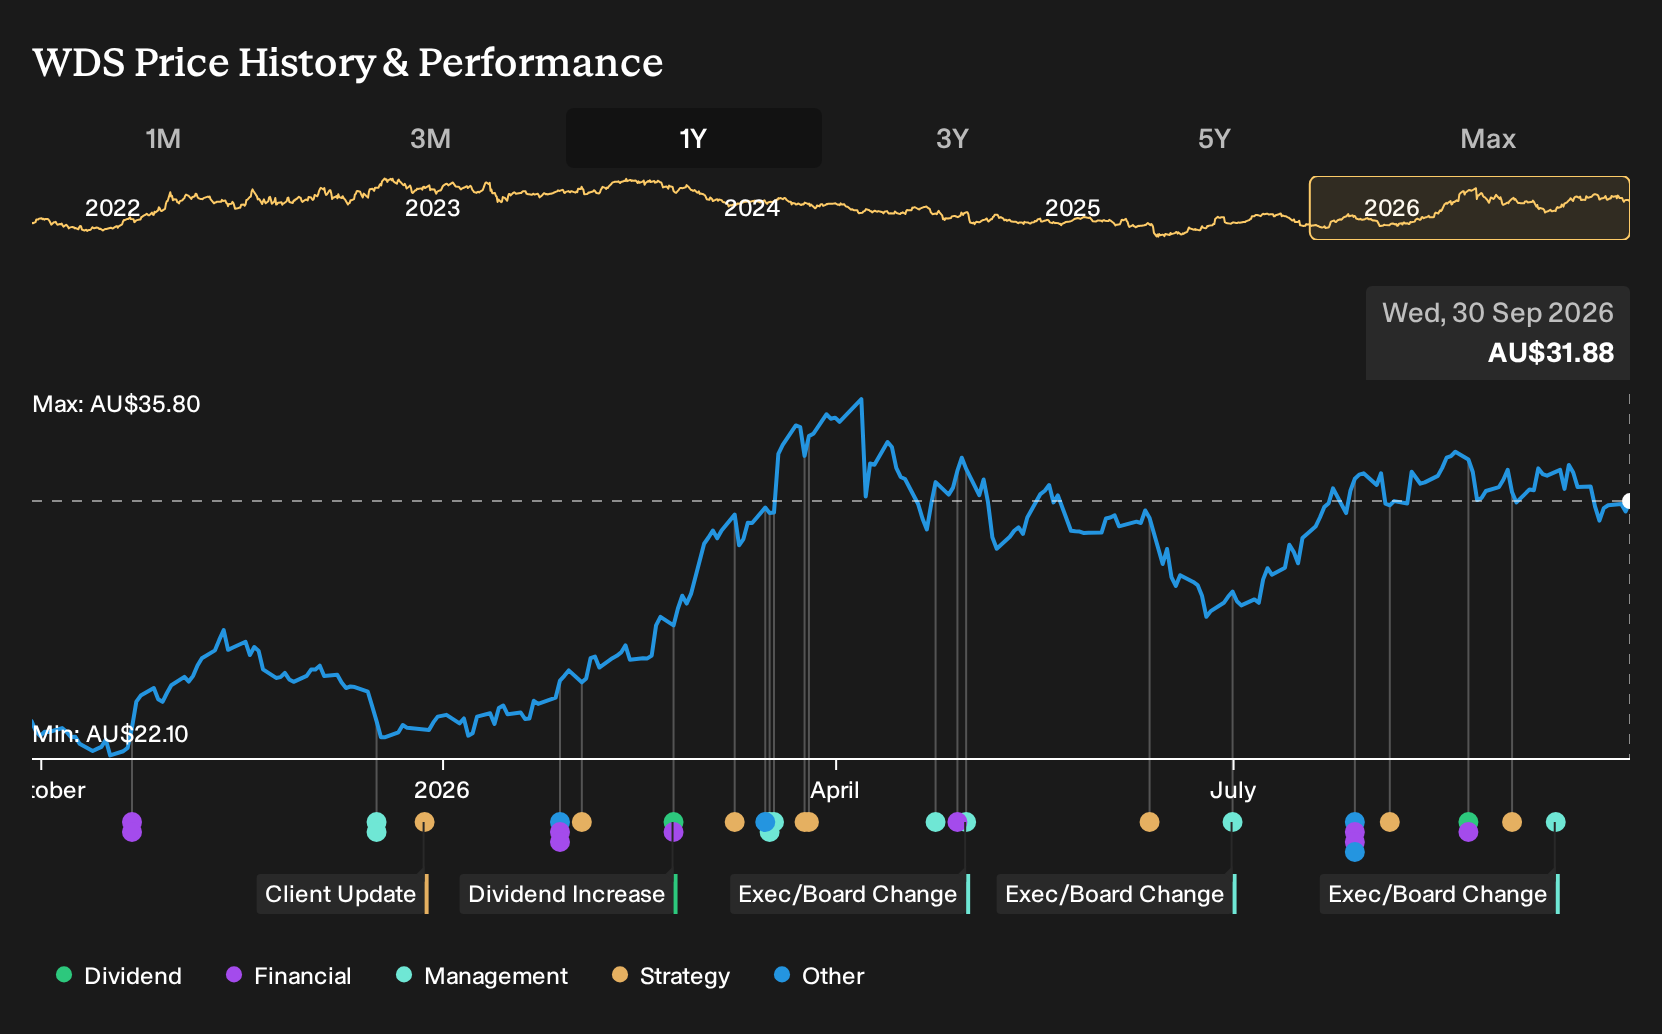
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based producer and seller of LNG, pipeline gas, crude oil and condensate across global projects.
Operations: Woodside Energy Group reports around US$7.3b from Australia, US$4.6b from International and US$1.9b from Marketing activities.
Market Cap: A$60.6b
Woodside Energy Group gives you direct exposure to large scale LNG output alongside oil production, with flagship projects that sit squarely in the Oil and Gas theme.
"The valuation also allows for Scarborough and Pluto Train 2 beginning production as planned, with the project 96% complete and targeting its first LNG cargo in the fourth quarter of 2026."
There is also the question of what happens if a single unseen pressure on cash generation shifts the balance between paying dividends and funding these large projects.
If you are weighing the trade off between funding megaprojects and maintaining cash flows to shareholders, read the full narrative for Woodside Energy Group to see how Woodside Energy Group could be positioned if those pressures accelerate or ease.
Santos (ASX:STO)
Overview: Santos is an Adelaide based hydrocarbon producer focused on upstream natural gas and LNG, plus crude oil and related liquids across Australia and Papua New Guinea.
Operations: Santos generates revenue mainly from Papua New Guinea at US$2.4b, Queensland & NSW at US$1.0b, Western Australia at US$735 million and Cooper Basin at US$495 million.
Market Cap: A$27.9b
Santos gives you another pure Oil and Gas producer on this list, with a heavy tilt toward LNG and pipeline gas linked to Asia facing contracts.
"The recovery is supported by Santos’ low operating break-even of below $35 per barrel, solid cash flows, and major projects including Barossa LNG and Pikka, which could significantly boost production and free cash flow."
What really matters from here is how one pressure on future cash generation shapes the balance between reinvestment, dividends and growth optionality.
That cash flow tension is exactly why it is worth reading the full narrative for Santos to see how Santos could accelerate or stall under different price and project scenarios.

Seeking Alternatives Before The Crowd Moves
Fresh ideas often appear first, then the data gets stale and the most attractive entry points can slip away while momentum is still building under the radar. Review these curated shortlists to explore opportunities at an earlier stage.
- Identify potential breakouts earlier by tracking under followed small caps using the curated 15 high quality undiscovered gems before momentum traders respond and liquidity conditions change.
- Explore income ideas with staying power by reviewing companies in the 3 dividend fortresses while yields remain elevated and prices have not yet fully adjusted.
- Monitor capital flows into real assets by scanning the curated 36 elite gold producer stocks before renewed interest in hard assets affects valuations and reduces your margin for error.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com