


Graham Holdings (GHC) is back on investor radars after subsidiary Code3 collected the 2026 Amazon Ads Partner Award for Programmatic Optimization and swept all its nominated categories at the 2026 Meta Agency Awards.
Against that backdrop, Graham Holdings’ share price has moved to US$1,134.67, with short term momentum mixed as the 90 day share price return declined 4.1%, while longer term performance remains strong, with the 3 year total shareholder return close to 97%.
Scan beyond Graham Holdings and evaluate other diversified businesses riding similar momentum with our 18 high quality undiscovered gems in today’s market.
After a 3 year total return near 97% and a share price above US$1,100, Graham Holdings now forces a tougher question: Does the balance of risk and potential reward still lean toward new buyers at this level?
Price-to-Earnings of 8.9x: Is it justified?
On simple earnings math, Graham Holdings trades on a P/E of 8.9x, which looks modest next to both its recent share price above $1,100 and the strong 3 year total return near 97%.
The P/E ratio compares what investors pay for each dollar of current earnings. For a diversified group like Graham Holdings, with education, healthcare, media, manufacturing and automotive dealerships all contributing to profit, that single number pools a wide range of business profiles into one valuation shorthand.
Recent results add some wrinkles. Reported earnings over the last twelve months include a large one off gain of $166.4m and net profit margins of 10.7% that are lower than the 14% level a year earlier. At the same time, earnings grew 13.9% per year over the past 5 years, while the most recent year showed a decline of 20.3%, which makes any P/E snapshot feel more like a moving target rather than a steady baseline.
Even with those caveats, the comparison to peers is hard to ignore. Management is running on a P/E of 8.9x, compared with a US Consumer Services peer average of 13.3x and a broader peer average of 16.8x. That gap suggests investors are paying a much lower multiple for Graham Holdings’ earnings than for similar businesses. This points to the market applying a clear discount to the stock’s current profit stream rather than paying up for its diversified model.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 8.9x (UNDERVALUED).
Still, two factors weigh against the Graham Holdings story: earnings that rely on one-off gains and a share price that already trades above analyst targets.
Find out about the key risks to this Graham Holdings narrative.
Another view on Graham Holdings’ value
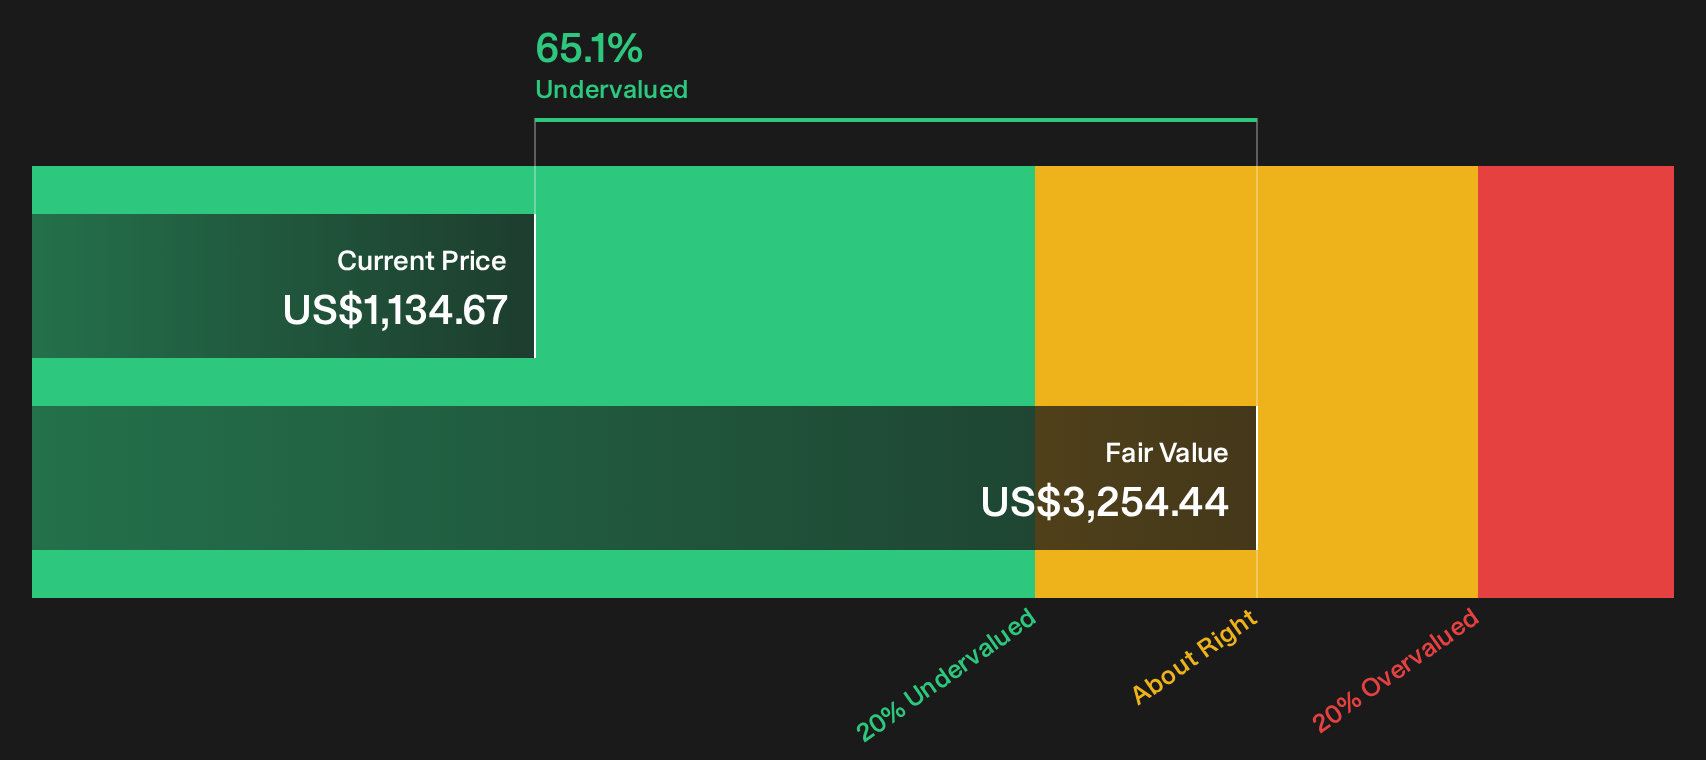
The earlier look at Graham Holdings leaned on its 8.9x P/E and the gap to peers. A different lens tells a stronger story. Our DCF model estimates future cash flows at about $3,254 per share, which is well above the current $1,134.67 price and indicates that the stock may be undervalued.
That is a sizable difference for you to consider. If the SWS DCF model is closer to reality than the simple earnings multiple, the bigger risk may be underestimating Graham Holdings rather than overpaying at today’s level.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Graham Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early opportunity for Graham Holdings. If you want a confident view, move quickly, run the numbers yourself, and weigh the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Graham Holdings?
Do not stop with Graham Holdings. The same tools that flagged this opportunity can help you uncover fresh ideas before the wider market pays attention.
- Target quality at a discount and scan companies that combine solid fundamentals with attractive valuations through the 32 high quality undervalued stocks.
- Build a steadier income stream by focusing on reliable payers screened via the 7 dividend fortresses.
- Reduce portfolio stress by focusing on companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com