


CarMax stock just dropped about 7% to US$55.09, erasing the recent bounce and reminding investors how skittish the market still is on used cars. The hit came even as Q2 delivered the kind of headline that usually earns a reprieve. Earnings per share reached US$1.16 and total revenue landed at about US$8.3b.
The real story is not today’s red screen. Same store sales growth of 18.9% signals a sharp turn from last year’s slump, which forces anyone thinking beyond this week to reassess what CarMax’s multi year earnings path might look like.
Is CarMax stock pricing in a real earnings reset, or just a temporary margin hit and one off loss? Map your view against our valuation analysis for CarMax
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): US$8,340.21m vs. US$7,084.48m (up 17.7%)
- Net Income (Q2 2027 vs Q2 2026): US$165.29m vs. US$95.38m (up 73.3%)
- Basic EPS (Q2 2027 vs Q2 2026): US$1.16 vs. US$0.64 (up 82.4%)
- Same Store Sales Growth (Q2 2027 vs Q2 2026): 18.9% vs. a decline of 7.1% (a swing of 26.0 percentage points)
Tired of scrolling through walls of earnings tables and raw figures on CarMax? See the full story of how the business is valued in one clean visual dashboard with our company report for CarMax.
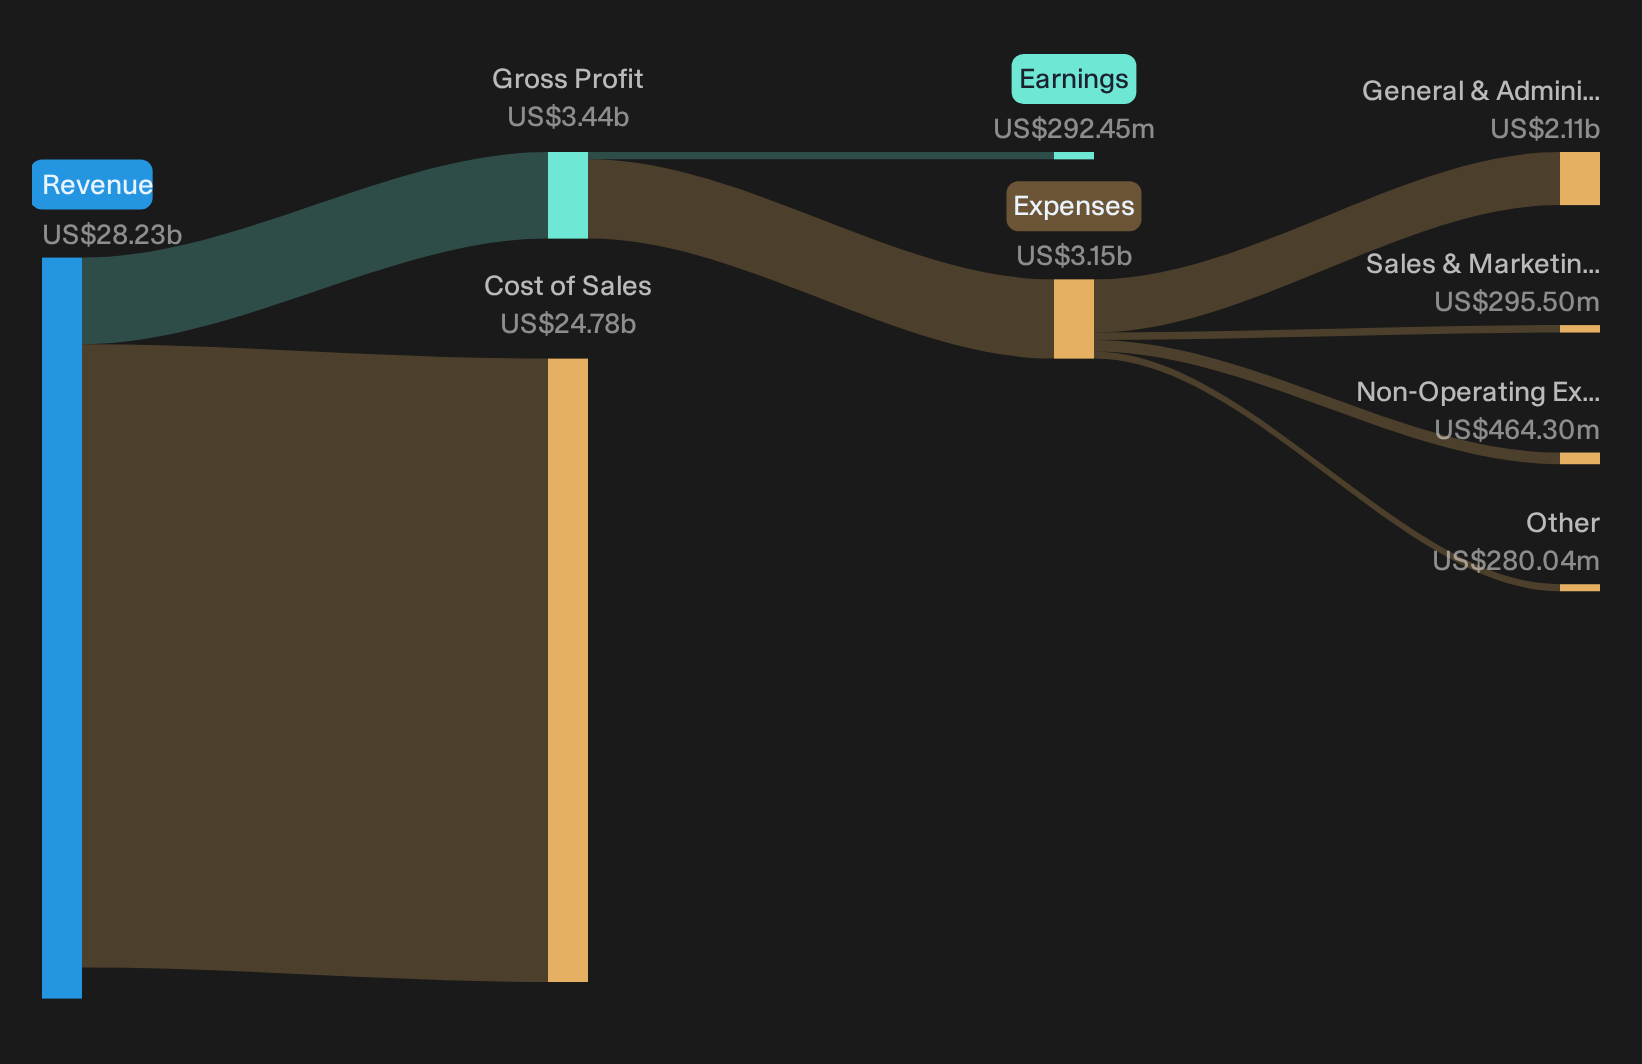
Evaluating CarMax’s Turnaround Claims Against Q2 Milestones
Bulls argue CarMax can use its omnichannel platform, data tools and captive finance arm to rebuild earnings power as volumes recover. Q2 gives some concrete checkpoint wins for that story.
On retail execution, used unit comps rising and same store sales growth of 18.9% show customers are responding to the “right car, right price, easier experience” push. Management intentionally trimmed profit per used unit to support volume, yet still delivered total gross profit growth and SG&A that grew far slower than revenue. This points to early “run lean” traction rather than a pure price war.
The finance pillar also moved in the intended direction. CarMax Auto Finance income advanced, helped by lower provisions and higher servicing fees, while Tier 2 penetration roughly doubled year over year. That is the kind of incremental earnings lever the bullish thesis has been looking for as unit volume improves.
Compare this on-the-ground progress at CarMax with how institutions are repositioning their models. Reveal where the Street has its upside and downside lines drawn in our consensus price target analysis for CarMax.CarMax Bear Case: Margin Fears Ease, Governance Does Not
The harshest CarMax critics argue that tighter credit standards at CarMax Auto Finance and heavier omnichannel spend would choke earnings, while governance noise sits in the background. This quarter cuts straight across the first part of that story. CAF income reached US$136m, helped by a US$29m lower loan loss provision, even as Tier 2 penetration doubled to 22% of that band. That mix shift points away from the idea that stricter underwriting is forcing provisions sharply higher right now.
The margin worry is not fully resolved though. Retail gross profit per unit slipped to US$2,105, and management is openly guiding to further GPU pressure in Q3 and Q4 to keep share, which lines up with the bears’ concern that volume comes at a cost. On governance, the ongoing shareholder investigation and a roughly 53% five year share price decline remain untouched by any Q2 milestones.
After a five year share price decline and margin compression, it is fair to ask whether these are isolated bruises or symptoms of deeper structural pressure inside CarMax. Review the full risk analysis for CarMax which shows 3 important warning signsTake Charge Of Your Next Move
If the sharp swing in CarMax’s same store sales and the stock’s recent drop has your attention, register for free with Simply Wall St and add it to a Watchlist to watch how the share price trades against fair value and spot a potential entry point that fits your plan. Once you are invested, keep your focus on what matters by tracking CarMax alongside your other positions in the Portfolio Command Center so you see key developments without getting buried in noise. For longer term conviction, use the Community to compare your thinking with other investors and pressure test your thesis as new information lands. That combination helps you surface hidden catalysts or emerging risks early and stay a step ahead of the market.
Seeking Fresh Alternatives Beyond CarMax?
Markets move fast. Breakout themes gather momentum, quiet winners start flying and tired stories get dropped before the crowd notices. Scan fresh stock ideas while it matters and get in early.
- Spot steadier compounding opportunities and move capital toward companies with strong balance sheets using our curated list of solid balance sheet and fundamentals stocks (25 results) before others catch on.
- Target potential cash rich AI leaders that already fund their own momentum by screening for 37 profitable AI stocks that aren't just burning cash while many investors still focus on story stocks.
- Shift attention to real infrastructure behind the AI boom by filtering for 90 AI infrastructure stocks that could benefit as data demand keeps building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com