


Hewlett Packard Enterprise (HPE) is back in the spotlight after securing a US$1.2b order from Vultr for its new AMD Helios AI Rack systems, highlighting demand for HPE’s data center AI hardware.
Recent moves in Hewlett Packard Enterprise’s share price show that momentum has been strong, with a 30-day share price return of 22.3% and a 90-day gain of 54.96%, while the year-to-date share price return of 164.34% aligns with a 1-year total shareholder return of 160.88%. This points to investors reacting positively to AI infrastructure orders like Vultr’s, expanded HPE Networking distribution through D&H, and new quantum collaborations with QuEra as part of a broader rerating of the stock.
Scan Hewlett Packard Enterprise’s AI surge alongside a hand-picked set of other infrastructure players by checking the 90 AI infrastructure stocks.
Hewlett Packard Enterprise’s surge now sits at the crossroads of improving AI infrastructure traction and a hotter story around the stock itself. How much of this move reflects business progress, rather than a reset in sentiment on HPE’s valuation?
Most Popular Narrative: 23% Overvalued
The most followed narrative pegs Hewlett Packard Enterprise’s fair value at $52, compared with the last close at $63.89. This puts the recent AI driven rally under a tougher spotlight for anyone weighing potential upside from here.
The assumed bearish price target for Hewlett Packard Enterprise is $52.0, which represents up to two standard deviations below the consensus price target of $67.43. This valuation is based on what can be assumed as the expectations of Hewlett Packard Enterprise's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 3 investors see Hewlett Packard Enterprise as 23% overvalued.
Result: Fair Value of $52 (OVERVALUED)
Still, Hewlett Packard Enterprise could upset this cautious fair value view if the Juniper deal closes cleanly, or if AI and GreenLake recurring demand convert faster than expected.
Find out about the key risks to this Hewlett Packard Enterprise narrative.
Another Take On Hewlett Packard Enterprise’s Valuation
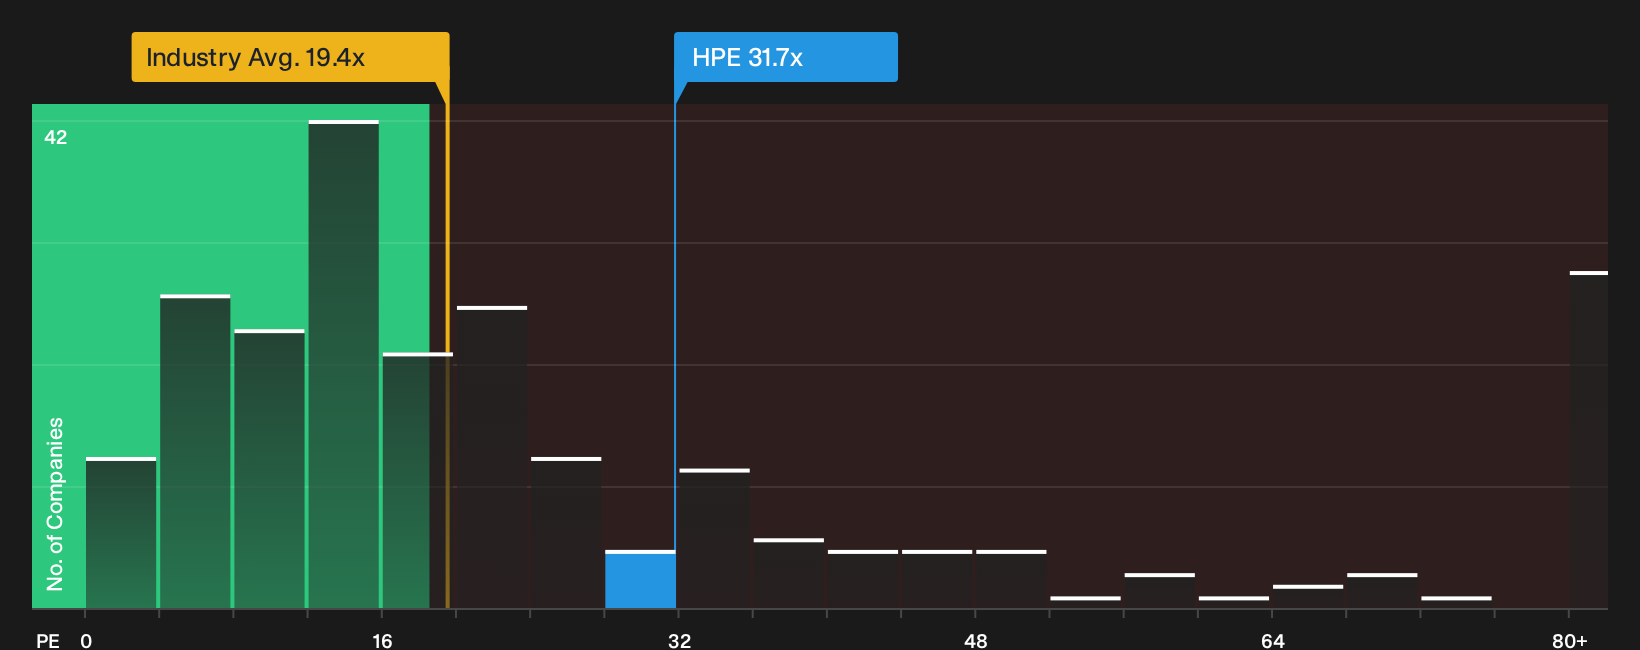
The narrative pegs Hewlett Packard Enterprise as 23% overvalued at $63.89 versus a $52 fair value, yet the company scores as good value on several earnings multiples. A P/E of 31.7x compares with 71.2x for peers, while the fair ratio sits at 38x. This comparison suggests the gap could represent potential upside or a cushion if sentiment cools.
These conflicting signals leave a simple question for investors: Is Hewlett Packard Enterprise priced for disappointment, or are multiples still catching up to the story unfolding in AI and networking? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Hewlett Packard Enterprise feels split, that is the point. You are weighing real concerns against real optimism, so pressure test both sides and walk through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hewlett Packard Enterprise?
Do not let your research stop with Hewlett Packard Enterprise. Broaden your watchlist with focused stock ideas that match how you like to balance opportunity and risk.
- Target potential bargains by scanning companies that screen as attractively priced with solid fundamentals through the 33 high quality undervalued stocks.
- Strengthen your income stream by reviewing stocks built around robust payouts with the 7 dividend fortresses.
- Dial down portfolio risk by focusing on companies that score well on resilience and financial stability using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com