


Government borrowing costs are at the highest levels in years, which can pressure many asset classes but also sharpen the focus on real assets that supply essential materials. Lithium producers fit that story for investors watching the shift toward electrification and energy security. This article looks at three United Kingdom linked lithium mining stocks from our global metals screener and explains why they may deserve a spot on your research list right now.
The three lithium miners covered below are just a starting sample from the broader opportunity set, and the full screen surfaced 3 more companies with equally compelling narratives that are not discussed here. To identify and analyze those additional global lithium miners and processing businesses with the most potential for your watchlist, head straight into the Lithium Mining screener.
Kodal Minerals (AIM:KOD)
Overview: Kodal Minerals is a London based explorer focused on the Bougouni Lithium Project in Mali, with additional early stage gold interests.
Market Cap: £56.5 million
Bougouni directly links Kodal Minerals to the lithium mining theme through spodumene concentrate shipments and recent profit from lithium focused operations. Investors get focused exposure to a single flagship project that is already generating product and cashflow, with future returns dependent on how efficiently Bougouni scales from its current phase.
To see how that scaling trade off looks in practice, review the 3 key rewards and 2 important warning signs (2 are major!) for a concise view of what might accelerate or stall Bougouni.

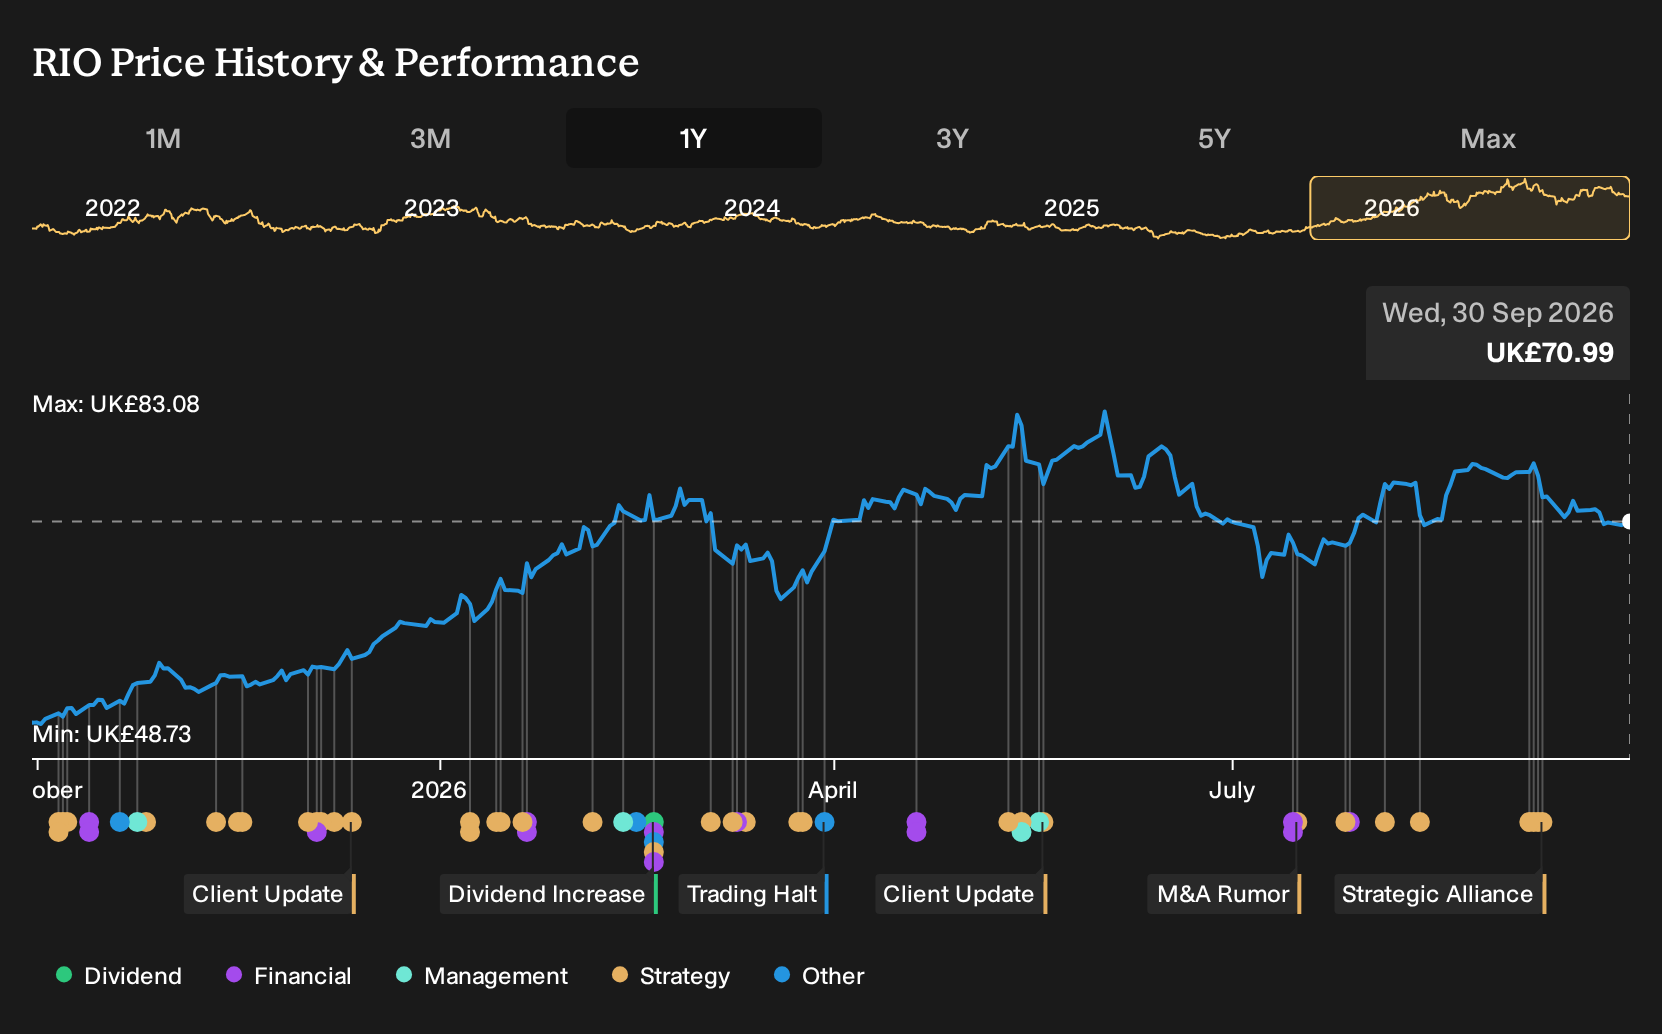
Rio Tinto Group (LSE:RIO)
Overview: Rio Tinto Group is a global miner that produces iron ore, aluminium, copper and lithium, anchored by its Rincon lithium project and Aluminium & Lithium processing arm.
Operations: The group generates about US$29.5b from Iron Ore and US$19.0b from Aluminium & Lithium, with Copper adding US$16.1b to total revenue.
Market Cap: £121.6b
For lithium focused investors, Rio Tinto Group offers a very different proposition from pure play juniors because its Rincon project and lithium processing lines sit inside a much larger iron ore and aluminium centred portfolio that already generates sizeable cash flows.
"The company's heavy dependence on iron ore, especially from the aging Pilbara assets and the slow ramp-up of Simandou, exposes Rio Tinto to heightened operational risk and increasing price volatility as Chinese steel demand plateaus and depletion of higher-grade ore accelerates, threatening long-term revenue and margin stability."
What happens to Rio Tinto’s lithium economics if one quiet shift in project execution costs starts to squeeze the group’s wider profit pool?
If that pressure point matters to you, read the full narrative for Rio Tinto Group to see how Rio Tinto Group’s lithium ambitions could still accelerate regardless of iron ore headwinds.
Savannah Resources (AIM:SAV)
Overview: Savannah Resources is a London based miner developing the 100% owned Barroso hard rock lithium project in northern Portugal.
Operations: The group currently reports about £1.7 million from Portugal Lithium and £1.1 million from HQ and other activities, before eliminations.
Market Cap: £156.2 million
Savannah Resources gives you direct exposure to a single advanced hard rock lithium project in Europe. Progress on Barroso is starting to align technical work, community agreements and fresh funding around a clearer development path.
"The €110m non repayable Portuguese state grant, with around €82m due during construction and the balance over the first five years of production, directly lowers the amount of equity and debt required and can support improved returns on capital and potential upside to long term net margins."
The key factor for Savannah Resources now is how one crucial financing milestone ultimately shapes future profitability and resilience.
That financing hinge is exactly what the full narrative for Savannah Resources unpacks. It shows how grant timing, permitting progress and funding choices could accelerate or stall Savannah Resources’ lithium ambitions.

Curious About Fresh Investing Alternatives
Some opportunities are already building quiet breakout momentum while others risk being caught before they fly. Use these fresh ideas while it matters and get in early.
- Spot resilient cash generators before the crowd by scanning the list of solid balance sheet and fundamentals (9 results) and zeroing in on businesses with room to fund growth from their own resources.
- Track where real income strength still holds by reviewing the 1 dividend fortresses and focusing on payouts that may better withstand shifting rate expectations.
- Target under the radar growth stories by working through the curated 5 high quality undiscovered gems and filtering for financial quality that can support a longer runway.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com