


Executive reshuffle puts ASX in the spotlight
ASX (ASX:ASX) is back on investor radars after a broad refresh of its senior ranks, including a new Chief Financial Officer, Chief Operating Officer and head of Clearing and Settlement.
Investors have been leaning back into ASX over 2026, with the share price up 12.13% over 90 days and delivering a 13.97% year to date share price return, even though the 5 year total shareholder return is still down 12.34%. This suggests recent momentum is building from a weaker long term base.
Scan how ASX compares with other market operators and exchanges by reviewing our hand picked list of solid balance sheet and fundamentals (12 results) in a single view.
ASX has already delivered a sharp rebound, yet the 5 year total shareholder return is still down. Is the recent executive overhaul a late entry point, or just the tail end of the rerating?
Most Popular Narrative: 36.3% Overvalued
ASX last closed at A$58.59, while the most followed narrative pegs fair value closer to A$43. That gap turns the focus to whether the executive clean-out and heavy investment phase can rebuild earnings power fast enough to support the current price.
ASX is the vertically-integrated operator of Australia's equity, derivatives and fixed-income markets and, critically, the statutory monopoly in cash-equity clearing and settlement, riding a legislated superannuation tailwind. The franchise clears the Quality Gate and the hard Truth Tests, and its earnings are described by some analysts as highly predictable a decade out. However, this is not the elite capital-light-compounder lane while a twice upgraded cost programme and a forced capital build compress returns and leave the base-case owner return well below a 12 to 15% hurdle at current prices.
See why 8 investors see ASX as 36% overvalued.
Result: Fair Value of A$43.00 (OVERVALUED)
Still, ASX faces two clear swing factors: any further cost blowout or a regulatory push for rival clearing could puncture this overvaluation story fast.
Find out about the key risks to this ASX narrative.
Another view on ASX’s valuation
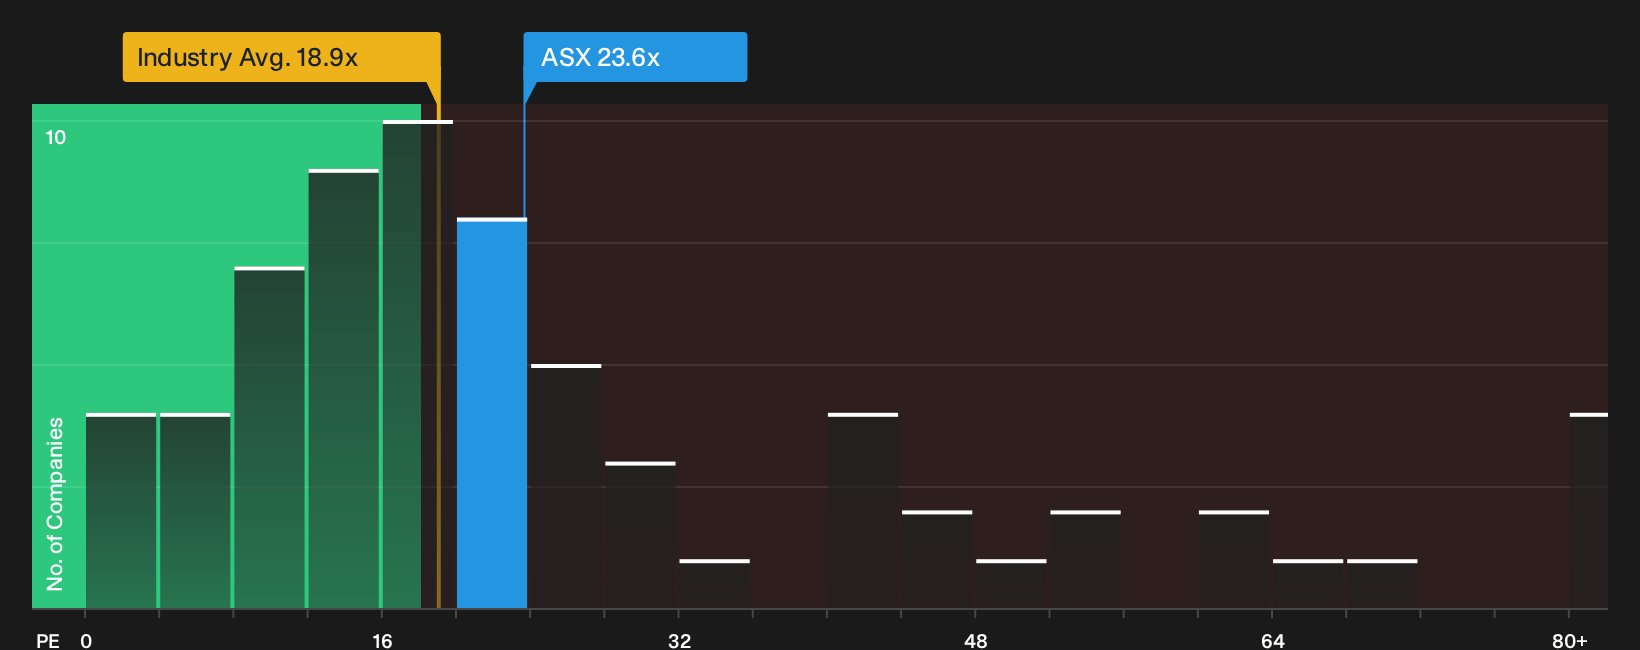
The sticker shock from that A$43 fair value estimate softens a little when you look at where ASX trades on earnings. The stock changes hands on a P/E of 23.6x, below the 28x average for peers, yet well above the fair ratio of 18.4x that our model indicates the market could move toward.
That mix of cheaper than peers but richer than the fair ratio points to a thinner safety margin rather than a clear bargain. The key question is whether investors are being paid enough for paying up on earnings quality when growth and returns on equity are only moderate.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
On balance, does ASX look like a stretched quality story or a fair premium for a resilient franchise? Act while the data is fresh and scrutinise the risk profile yourself by reviewing the 1 important warning sign
Looking for more ASX investment ideas?
Do not stop your research at ASX alone. Broaden your watchlist with fresh ideas and give yourself more options before the next key market move.
- Target resilience first and filter for financially sturdy businesses using the list of solid balance sheet and fundamentals (12 results) that can help anchor your portfolio.
- Hunt for value and scan the 5 high quality undervalued stocks to spot companies where quality fundamentals and pricing look out of sync.
- Build your income stream and review the 3 dividend fortresses that focuses on higher yielding payouts with an eye on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com