


Cactus has delivered a strong run over the past few years, and the recent share price swings are now putting the focus squarely on what investors are paying for its earnings. With the stock moving sharply over different time frames, the key issue is how much of that track record is already embedded in today’s valuation.
- Over the past 5 years Cactus has returned 66.4%, which puts real weight on the question of whether its current earnings base can support the price you see today.
- The business model relies heavily on its ability to turn equipment demand into consistent profit margins and cash generation, which can shape how much investors are prepared to pay for each dollar of earnings.
- Your read on Cactus is one view; the desks covering it have another. See what analysts think Cactus's shares could be worth.
The issue now is whether Cactus stock’s recent price, after that multi year run, is justified by its earnings power.
If you want to pressure test Cactus against other opportunities where price is anchored to fundamentals, scan through the 32 high quality undervalued stocks
Does Cactus Look Pricey on Earnings?
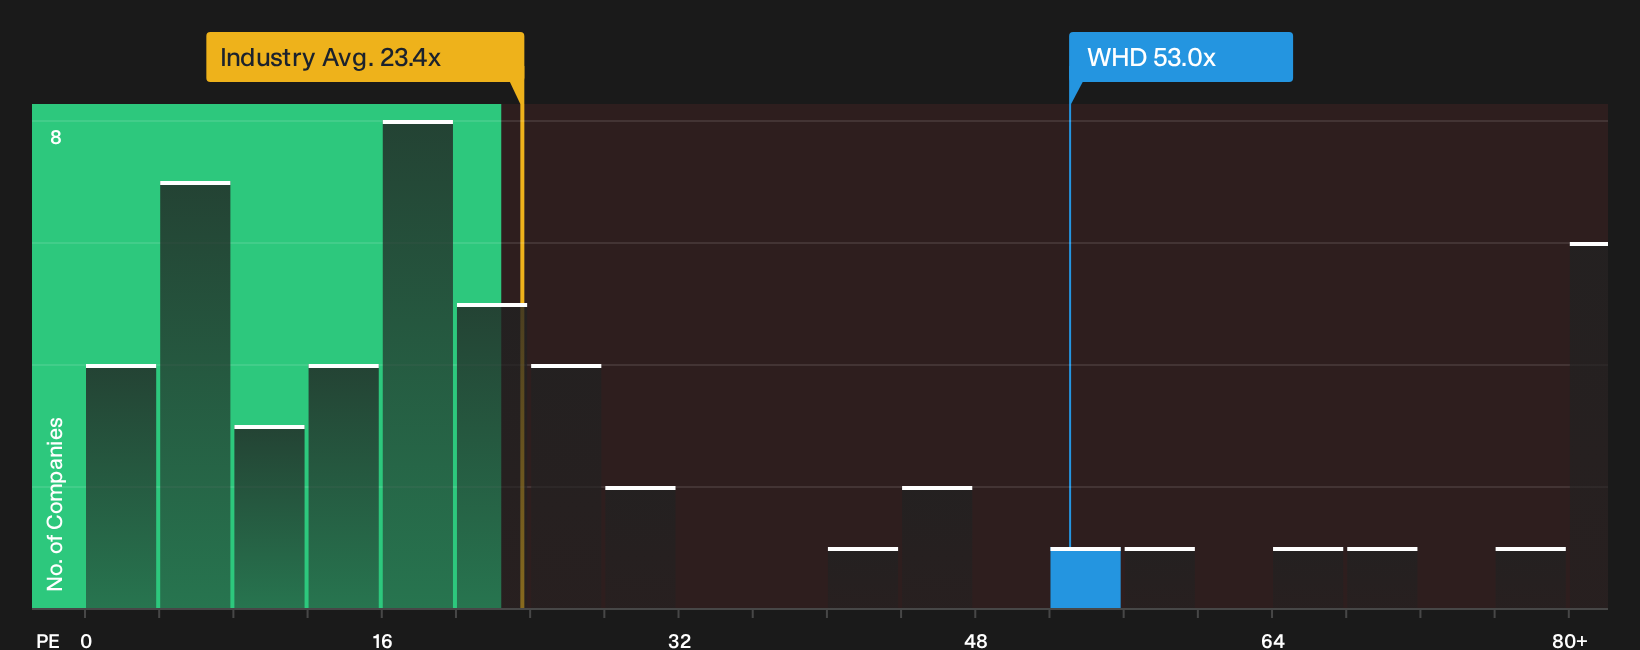
The P/E ratio fits Cactus because earnings are a key anchor for how investors judge an equipment focused energy services business. On this yardstick, Cactus trades on about 53.0x earnings, which is well above both the Energy Services industry average of roughly 23.4x and the peer group around 28.1x. That is a hefty premium for each dollar of profit.
The fair multiple implied by Cactus’ own growth profile, margins, size and risk sits below the current 53.0x. That signals the stock screens overvalued on this framework, with buyers today paying more than that tailored benchmark suggests for the existing earnings base. To decide whether that premium feels acceptable, you would need to weigh how durable you think Cactus’ profitability and cash generation are, and how much of that is already reflected in the share price. Explore the numbers behind Cactus's P/E valuation.
The Cactus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Cactus pick up where the P/E question leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for Cactus' valuation to look meaningfully higher or lower than today. Each narrative treats fair value as a thesis you can track over time, so you can see how the underlying business either lines up with it or drifts away.
Community views on Cactus split between those who see international expansion and efficiency gains as underappreciated and others who focus on backlog risk and margin pressure.
Bull case: 8% undervalued
"The acquisition of a majority interest in Baker Hughes' Surface Pressure Control business will significantly expand Cactus' geographic footprint and customer base into the Middle East..."
Discover why this Narrative puts Cactus at 8% undervalued.
Bear case: 9% overvalued
"Growing exposure to international and sour service spoolable pipe, including new orders in the Middle East and Africa, ties a larger portion of revenue to long lead, project based markets..."
Explore why this Narrative puts Cactus at 9% overvalued.
Cactus valuation leaves one influential factor in the background
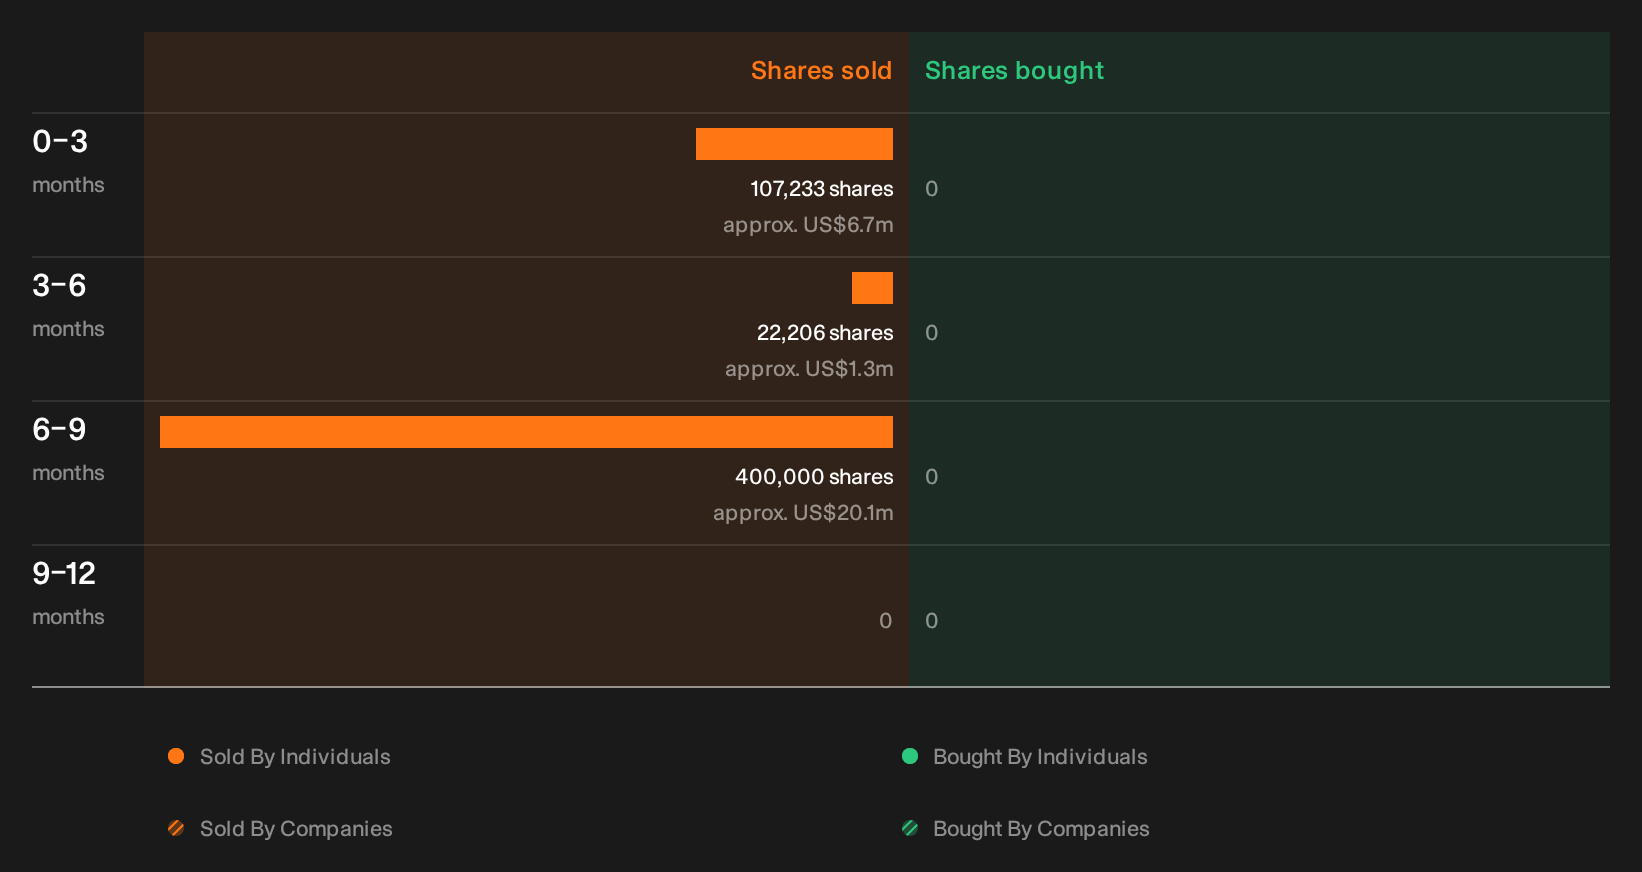
There is one more angle that deserves your attention, because recent activity by people inside Cactus has been flagged by our checks and the identities, volumes and potential read throughs are still for you to unpack. See the recent insider selling flagged for Cactus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com