


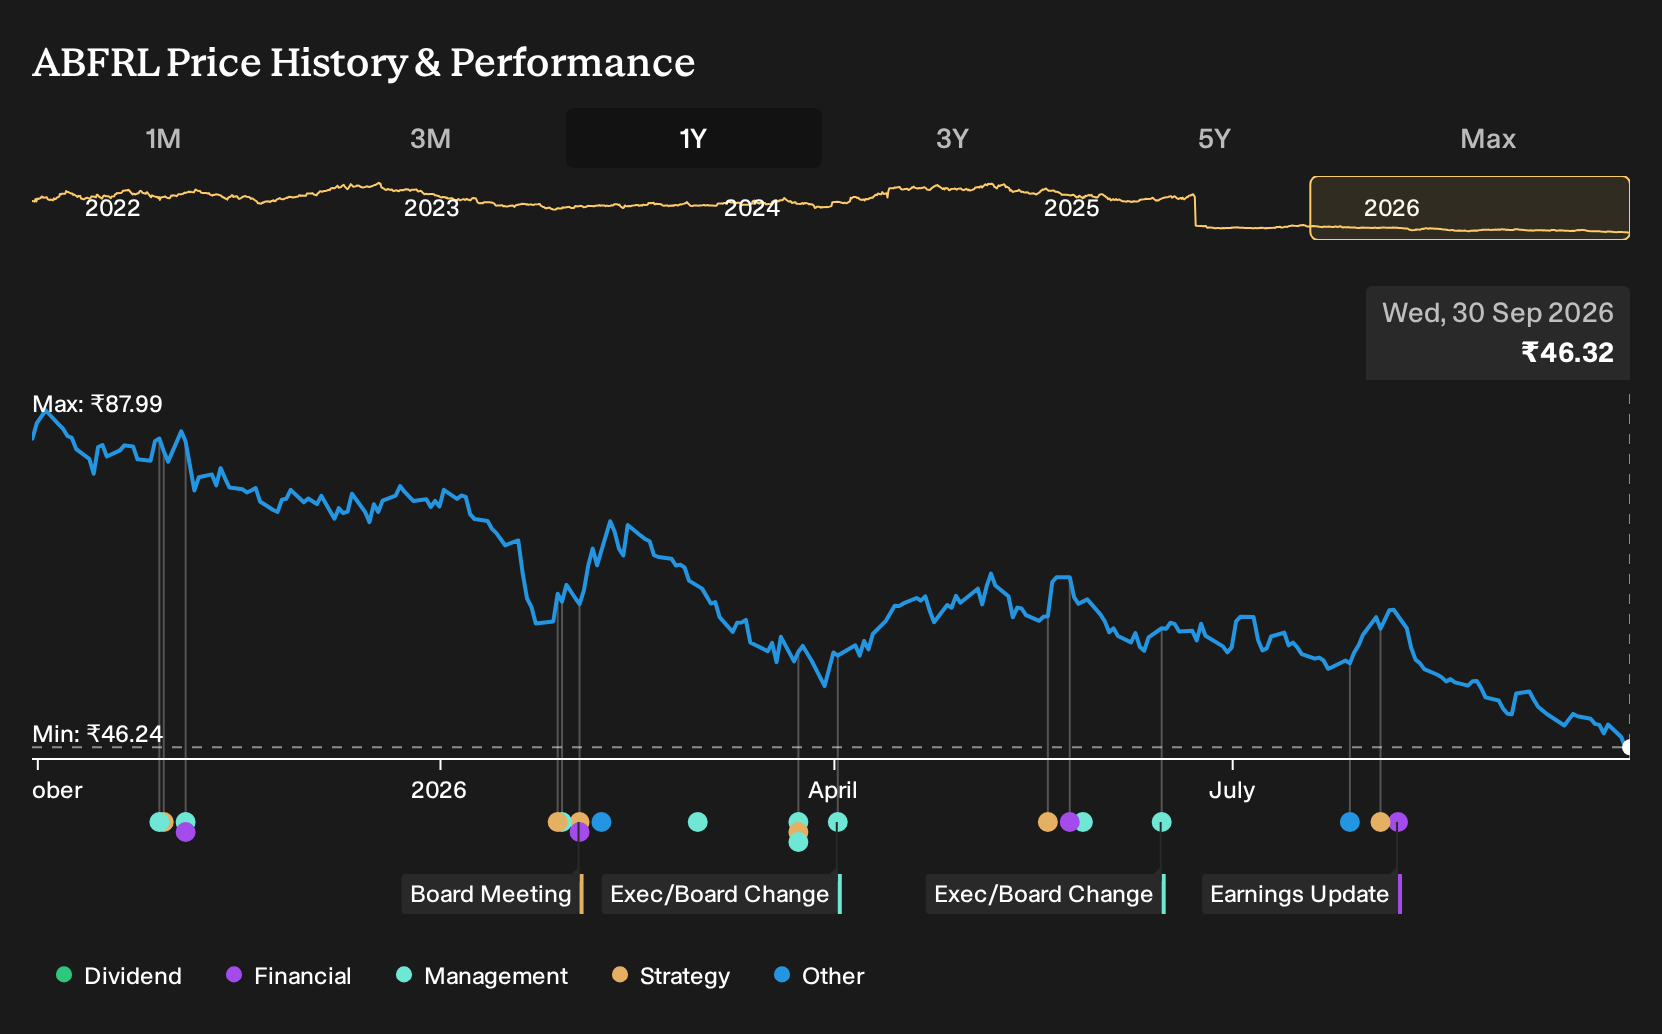
If you had backed the bullish September 2025 case on Aditya Birla Fashion and Retail, the past year has been painful. For Aditya Birla Fashion and Retail shareholders, the loss over the past year was 46.4%, including dividends. That drop sits alongside later results that showed higher reported revenue but a continued net loss, with margin still in negative territory. So what did the original investment thesis miss about demerger benefits, digital momentum, and the path from heavy losses to industry-level margins?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Aditya Birla Fashion and Retail harder to judge, start where the gap is still open and scan 192 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Aditya Birla Fashion and Retail
The shares cost ₹84.49 at the start of the period, and Aditya Birla Fashion and Retail sat between two sharply different stories that still looked plausible. One side focused on urban consumers and digital commerce. The other worried about e-commerce pressure and balance sheet strain.
The bullish Narrative put Fair Value at ₹103, which was 22% above the start price. It leaned on the demerger and capital raise helping focused leadership and M&A, plus heavy omnichannel and supply-chain investment to support margin expansion.
The bearish case set Fair Value at ₹58, or 31% below the start price. That view highlighted rising e-commerce competition hurting store traffic, alongside high leverage and ongoing capital needs keeping net earnings and returns under pressure.
What The Results Changed For Aditya Birla Fashion and Retail
For Aditya Birla Fashion and Retail, the clearest data point was the Q1 2027 numbers. Revenue reached ₹20,255.6m against ₹18,314.6m a year earlier, while the firm still reported a net loss, which widened slightly from ₹2,119.8m to ₹2,152.4m. Net margin moved from a loss of 11.6% to a loss of 10.6%. That mix of higher sales, smaller-loss margin and ongoing red ink had implications for both more optimistic and more cautious interpretations.
The useful takeaway is simple. When a thesis leans heavily on margin recovery, track the reported net margin each quarter and compare it with any stated path toward industry levels before focusing on share price moves or revenue alone.
What Aditya Birla Fashion and Retail’s Drop Leaves You Weighing
Aditya Birla Fashion and Retail now trades at ₹46.32, well below the starting price a year ago. The selected bullish Narrative still places its Fair Value above the current price, based on how ethnic wear, premium brands and digital-first labels could reshape the mix.
If you consider that view, the key question is whether expansion in TMRW, Style Up and ethnic formats can eventually cover cost pressures and debt so that today’s fall reflects potential operating leverage in the future rather than a lasting warning.
"Expansion in ethnic wear and digital-first brands is increasing market share, with premiumization and new consumer segments fueling sustained revenue and margin growth. Investments in omnichannel capabilities, operational efficiencies, and geographic expansion are enhancing store productivity and positioning for greater penetration in organized retail."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Aditya Birla Fashion
Aditya Birla Fashion and Retail depends on shoppers who increasingly expect to transact online. Your attention keeps drifting to stores and clothing lines.
Yet those same buyers also need somewhere to pay, borrow and move money securely.
Another business concentrates on that financial side of digital commerce for these users.
It runs a marketplace and a payments platform together, so spending and lending sit inside one ecosystem.
The mix of checkout, credit and money storage could reshape what customers rely on, leaving open how much value settles around that combined role.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 85% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com