


Graphic Packaging Holding has seen its share price fall sharply in recent years, which puts a spotlight on whether the current valuation really matches what the business earns. With the stock under pressure, the key issue for you is whether today's price is properly grounded in the company’s earnings power.
- Over the past 3 years, Graphic Packaging Holding shares have declined 55.4%, which raises fresh questions about how the market is weighing its earnings against the risks in the business.
- The business model relies heavily on converting earnings into cash flow through packaging contracts and capital intensive assets, which can shape how dependable those earnings look when you assess the valuation.
- The analysts covering Graphic Packaging Holding have run their own numbers. See what analysts think Graphic Packaging Holding's shares could be worth.
The issue now is whether Graphic Packaging Holding's current share price is justified by the earnings the business is generating today.
If you want to explore the same earnings-focused question beyond Graphic Packaging Holding, compare it with a wider group of 31 high quality undervalued stocks.
Is Graphic Packaging Holding Still Cheap on Earnings?
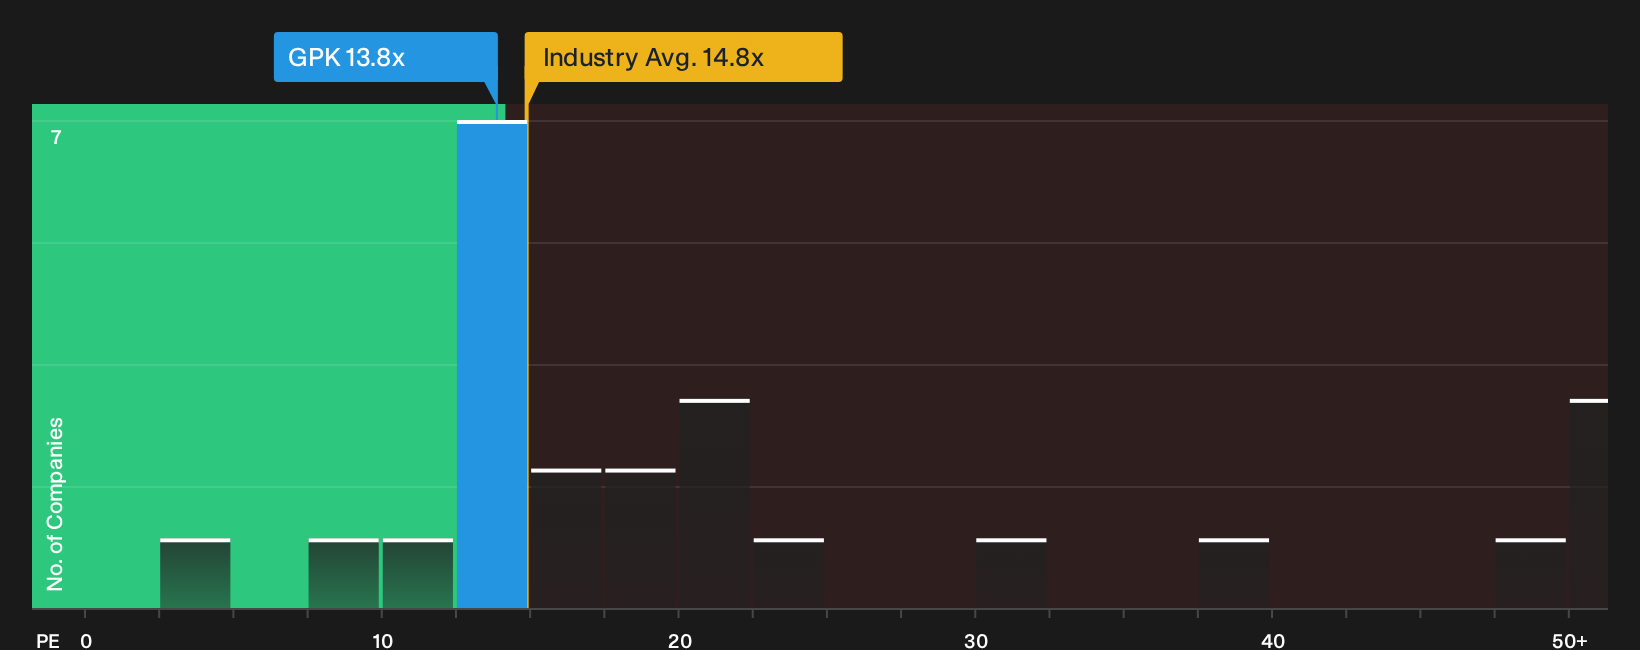
The P/E ratio is a useful lens for Graphic Packaging Holding because earnings remain the key reference point for how this packaging business is priced. On this measure, the stock trades on roughly 13.8x earnings, which is slightly below the Packaging industry average of about 14.8x and also below the broader peer group around 18.2x.
The Fair Ratio model, which looks at what multiple might make sense given Graphic Packaging Holding's profitability profile, growth path, scale and risk, points to a higher figure than where the shares currently change hands. That gap means the current P/E sits on the low side of what this tailored framework would suggest, so the market is putting a relatively modest earnings tag on the business compared with what the model-implied multiple indicates. Explore the numbers behind Graphic Packaging Holding's P/E valuation.
The Graphic Packaging Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Graphic Packaging Holding valuation question leaves off, since they spell out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today and sit on the Community page. Each scenario ties a fair value estimate to a particular storyline about Graphic Packaging Holding's potential catalysts and key risks, so you can track over time which version of events seems to be unfolding in the real world.
One of the top community narratives on Graphic Packaging Holding: 9% undervalued
"The main thing that has to go right is that Graphic Packaging Holding turns its lower sub $450 million capital expenditure plan and targeted $600 to $700 million of 2026 adjusted free cash flow into sustained cash generation and meaningful debt reduction over the next few years..."
Discover why this Narrative puts Graphic Packaging Holding at 9% undervalued.
One more angle on Graphic Packaging Holding that could change how you see it
Everything so far has focused on what Graphic Packaging Holding earns today, while analyst projections sketch out where profits and cash generation might be a few years from now and give you a different reference point to compare with the current share price. Explore where analysts expect Graphic Packaging Holding to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com