


- Astellas Pharma announced that the first patient has been dosed in a Phase 3 trial of setidegrasib versus docetaxel in KRAS G12D-mutated advanced or metastatic non-small cell lung cancer after platinum chemotherapy and checkpoint inhibitor therapy.
- The move pushes Astellas Pharma deeper into targeted protein degradation, using in-house R&D to pursue an area with no approved KRAS G12D-specific treatments, with potential long-term implications for oncology development costs and portfolio mix.
- This article examines how Astellas Pharma's investment narrative is influenced by the Phase 3 setidegrasib program in previously treated KRAS G12D NSCLC.
Compare Astellas Pharma's push into targeted protein degradation with other potential oncology opportunities by scanning the 76 high quality undiscovered gems that may still sit under most investors' radar.
Astellas Pharma Investment Narrative Recap
To own Astellas Pharma, you need to believe the oncology and rare disease pipeline can offset pressure from drug pricing and eventual patent losses on blockbusters like XTANDI. The Phase 3 setidegrasib trial raises the stakes in targeted protein degradation, but by itself it does not yet change the near term earnings picture or headline risk.
The more immediate swing factors still look tied to how strategic brands such as PADCEV, VYLOY, and IZERVAY perform while analysts expect revenue and earnings to decline over the next few years. Cost programs and disciplined R&D spend matter as much as pipeline news, because pricing pressure and future generics could weigh on profitability.
The most relevant update here is the Phase 3 launch for setidegrasib in KRAS G12D NSCLC, backed by earlier New England Journal of Medicine data and now being tested against docetaxel in around 356 patients. This is an operational bet on in house R&D and targeted protein degradation to create a new oncology franchise.
For catalysts, investor attention will likely focus on study recruitment progress, interim efficacy and safety signals, and how management frames this asset at venues such as the AACR pancreatic cancer conference. The key risk is execution. Any clinical setbacks or delays would leave Astellas Pharma more reliant on existing oncology products as patent and pricing headwinds build.
Astellas Pharma's current analyst narrative points to revenues of ¥1,888.3 billion and earnings of ¥245.4 billion by 2029, based on a forecast yearly revenue decline of 6.0%. That earnings outlook implies a decrease of about ¥119.5 billion from earnings of ¥364.9 billion today.
Uncover why Astellas Pharma's fair value indicates an 8% potential upside to its current price that may not last much longer.
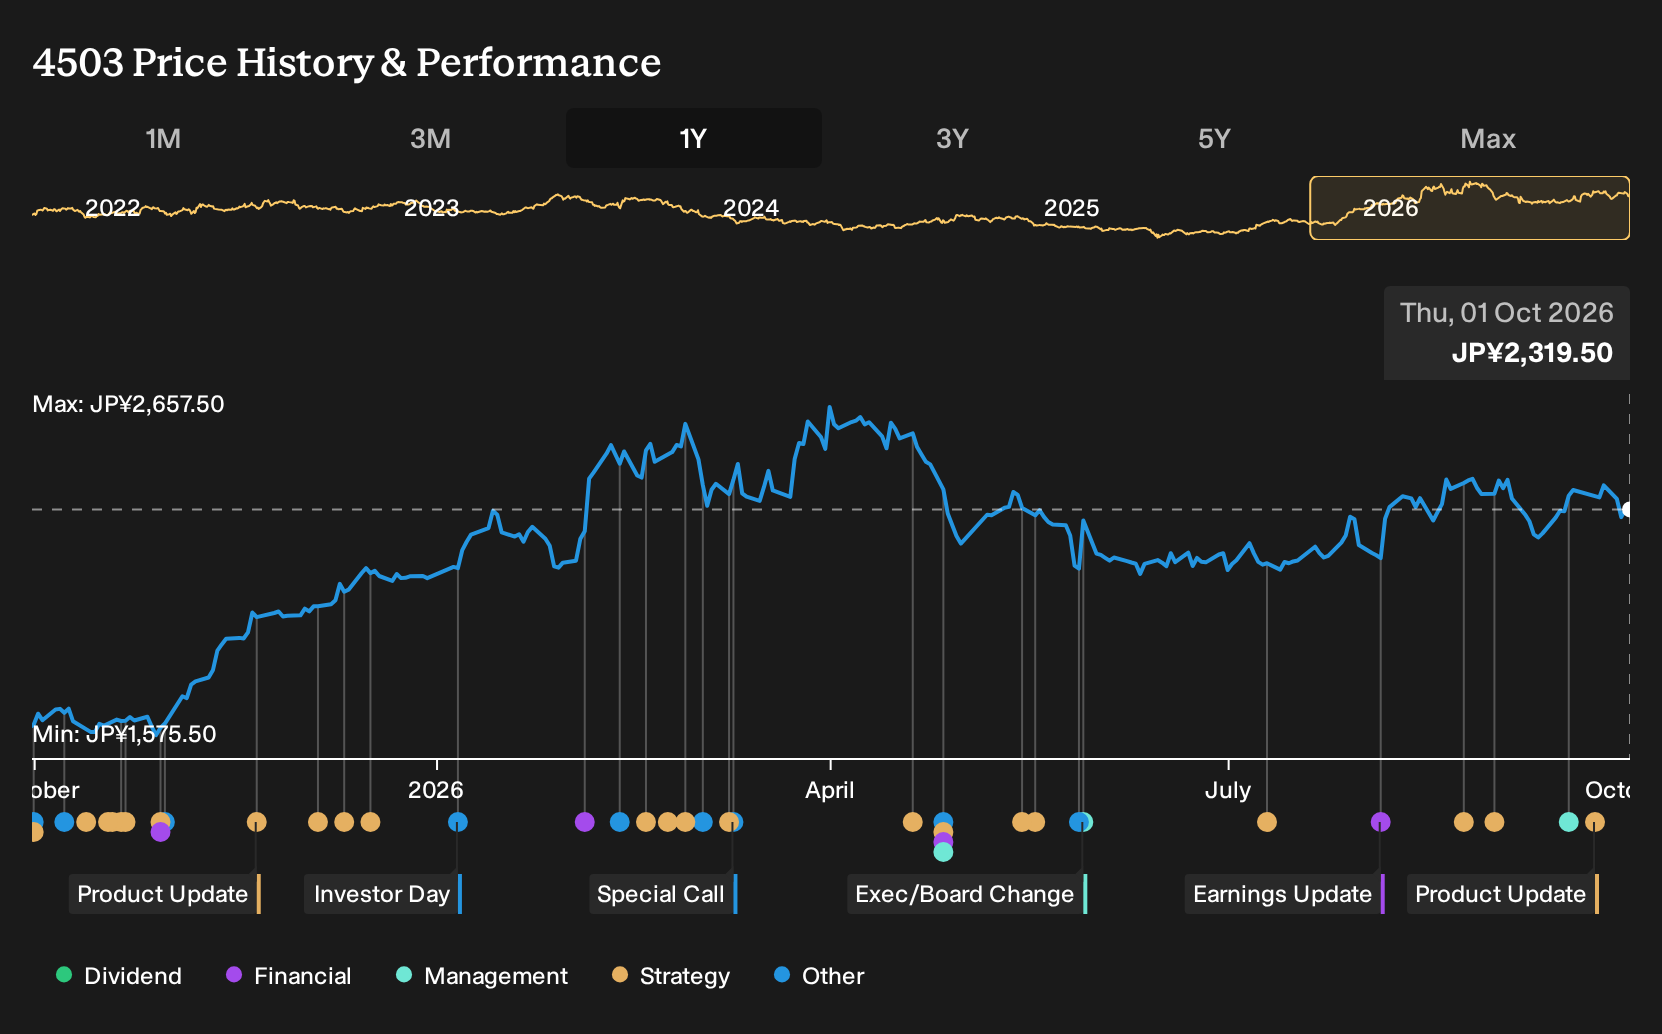
Exploring Other Perspectives
One alternate angle to watch is oncology concentration risk. The most cautious Astellas Pharma analysts were assuming revenues of ¥1,628.3b and earnings of ¥135.9b by 2029, far below consensus. Those views came before this KRAS G12D Phase 3 news, so opinions on the stock could shift sharply in either direction.
Explore 2 other Astellas Pharma fair value estimates, including one that suggests it could be worth just ¥2,512.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astellas Pharma research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astellas Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astellas Pharma's overall financial health at a glance.
Looking For More Astellas Pharma Sized Ideas?
If you want to pressure test the Astellas Pharma thesis, a useful next step is to line it up against other businesses with different risk and return profiles using the Simply Wall St Screener.
- If capital protection is high on your list, scan a set of resilient companies via the 21 resilient stocks with low risk scores that may offer steadier return potential than a single oncology focused stock.
- If balance sheet strength is your starting filter, sort through a list of solid balance sheet and fundamentals (23 results) to find businesses where debt and liquidity look more conservative on paper.
- If you want ideas that are not widely followed yet, widen your search to a 76 high quality undiscovered gems that could complement or contrast with Astellas Pharma in your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com