


Lunchables parent Kraft Heinz (KHC) is leaning into fan habits with a limited-edition Lunchables Pizza Grill, launched for National Pizza Month and sold through Walmart.com with a free Lunchables Pizza coupon attached.
Kraft Heinz shares have been under pressure, with the 30 day share price return down 11.49% and the year to date share price return down 6.85%, while the 1 year total shareholder return has declined 7.63% and the 5 year total shareholder return is down 21.70%. This points to softer momentum even as the company leans on brand driven launches like the Lunchables Pizza Grill to refresh sentiment.
Scan for other packaged food and beverage stocks that may be setting up stronger momentum profiles than Kraft Heinz by checking our curated list of 31 high quality undervalued stocks.
Kraft Heinz still owns powerful pantry brands, but the recent share price slide raises a different issue. Is this solid grocery franchise now quietly cheap, or is the weaker trading action pointing to a fair price for the risk?
Most Popular Narrative: 35.1% Undervalued
Kraft Heinz closed at $22.72, while the most followed valuation story pegs fair value around $35. According to woodworthfund, that disconnect rests on cash generation, a defended dividend, and a reset focus on brands instead of financial engineering.
The case for KHC is not that it is cheap for no reason. The reasons are obvious: sluggish top-line history, category pressure, inflation, consumer softness, and years of strategic drift. The opportunity is that the stock appears priced as though these problems are permanent while the business itself is showing signs of being merely repairable.
See why 35 investors see Kraft Heinz as 35% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, Kraft Heinz faces pressure if brand spending fails to lift volumes or if inflation and consumer pushback continue to squeeze a business already reporting a net loss.
Find out about the key risks to this Kraft Heinz narrative.
Another View: Kraft Heinz Through A Sales Multiple Lens
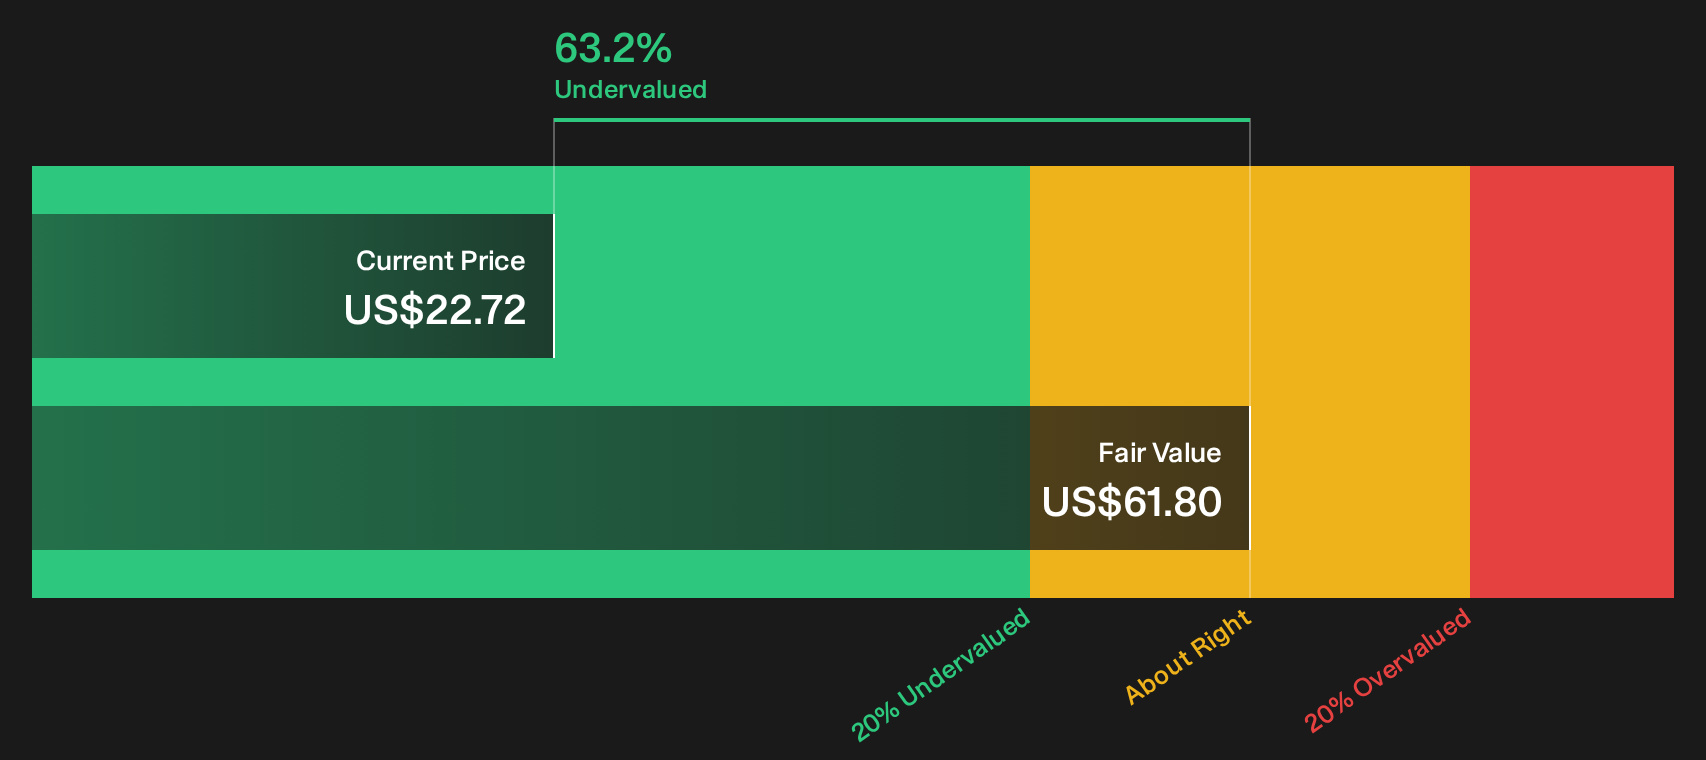
The SWS DCF model points to a big gap between price and estimated value, with Kraft Heinz at $22.72 compared with an implied $61.80 future cash flow value, which screens as deeply undervalued. That is a wide margin. It raises a blunt question for investors: Is this a bargain or a value trap hiding behind spreadsheets?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Kraft Heinz can create a lot of noise. Move quickly from headlines to hard numbers and weigh both sides of the story with 2 key rewards and 2 important warning signs.
Ready To Find More Ideas Beyond Kraft Heinz?
If Kraft Heinz has you thinking about value and momentum, use that curiosity as a springboard to compare it with other opportunities through the Simply Wall Street Screener.
- Target sturdier potential havens by scanning a 31 resilient stocks with low risk scores that focuses on businesses with more resilient risk profiles than the broader market.
- Hunt for possible bargains by lining up Kraft Heinz beside a 19 high quality undiscovered gems where quality fundamentals have not yet attracted broad attention.
- Zero in on balance sheet strength by checking a list of solid balance sheet and fundamentals (25 results) so you are not caught off guard by hidden financial fragility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com