


Premier Investments (ASX:PMV) has drawn fresh attention after reporting full year results showing lower sales and sharply reduced net income, while at the same time affirming a fully franked A$0.36 dividend for the six month period.
Premier Investments shares trade at A$11.98, with the 30 day share price return up 3.01% but the 90 day share price return down 16.92%. That weaker recent momentum lines up with a 1 year total shareholder return that has fallen 34.26%.
Compare Premier Investments' mix of weaker earnings, a maintained payout and recent share price pressure with hand-picked income ideas screened for resilience and yield in our 3 dividend fortresses
Premier Investments trades well below both analyst targets and some intrinsic value estimates after this latest slide. Is that discount justified when you compare the earnings reset with those valuation ranges?
Price-to-Earnings of 14.8x: Is it justified?
Premier Investments now trades on a P/E of 14.8x, which points to a softer earnings multiple even as the share price reflects recent selling pressure and analyst targets sit higher.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much you are paying for each dollar of profit. For a retailer like Premier Investments, this yardstick is often used because net income is a key driver of long term returns and cash generation.
On these figures, the stock is described as good value on several fronts. The current 14.8x P/E is below the estimated fair P/E of 15.7x, below the Oceanic Specialty Retail industry average of 15.5x and below a peer group average of 22.4x. That combination suggests the market is applying a clear discount to Premier Investments compared with both its sector and direct competitors, while the fair ratio points to a level the valuation could move toward if sentiment improved.
Explore the SWS fair ratio for Premier Investments.
Result: Price-to-Earnings of 14.8x (UNDERVALUED)
Still, the weak 1 year total return and pressure on multi year performance leave Premier Investments exposed if earnings soften again or if consumer demand tightens further.
Find out about the key risks to this Premier Investments narrative.
Another View on Premier Investments' Value
The P/E points to Premier Investments looking inexpensive, but the SWS DCF model goes much further. On that approach, the shares at A$11.98 sit against an estimated future cash flow value of A$24.61, which implies a very wide gap. Is that a genuine opportunity or a signal that the cash flow assumptions are too optimistic?
Our DCF model is only one tool, so it helps to understand how it builds from long term cash flows and discount rates before leaning on it too heavily. Look into how the SWS DCF model arrives at its fair value.
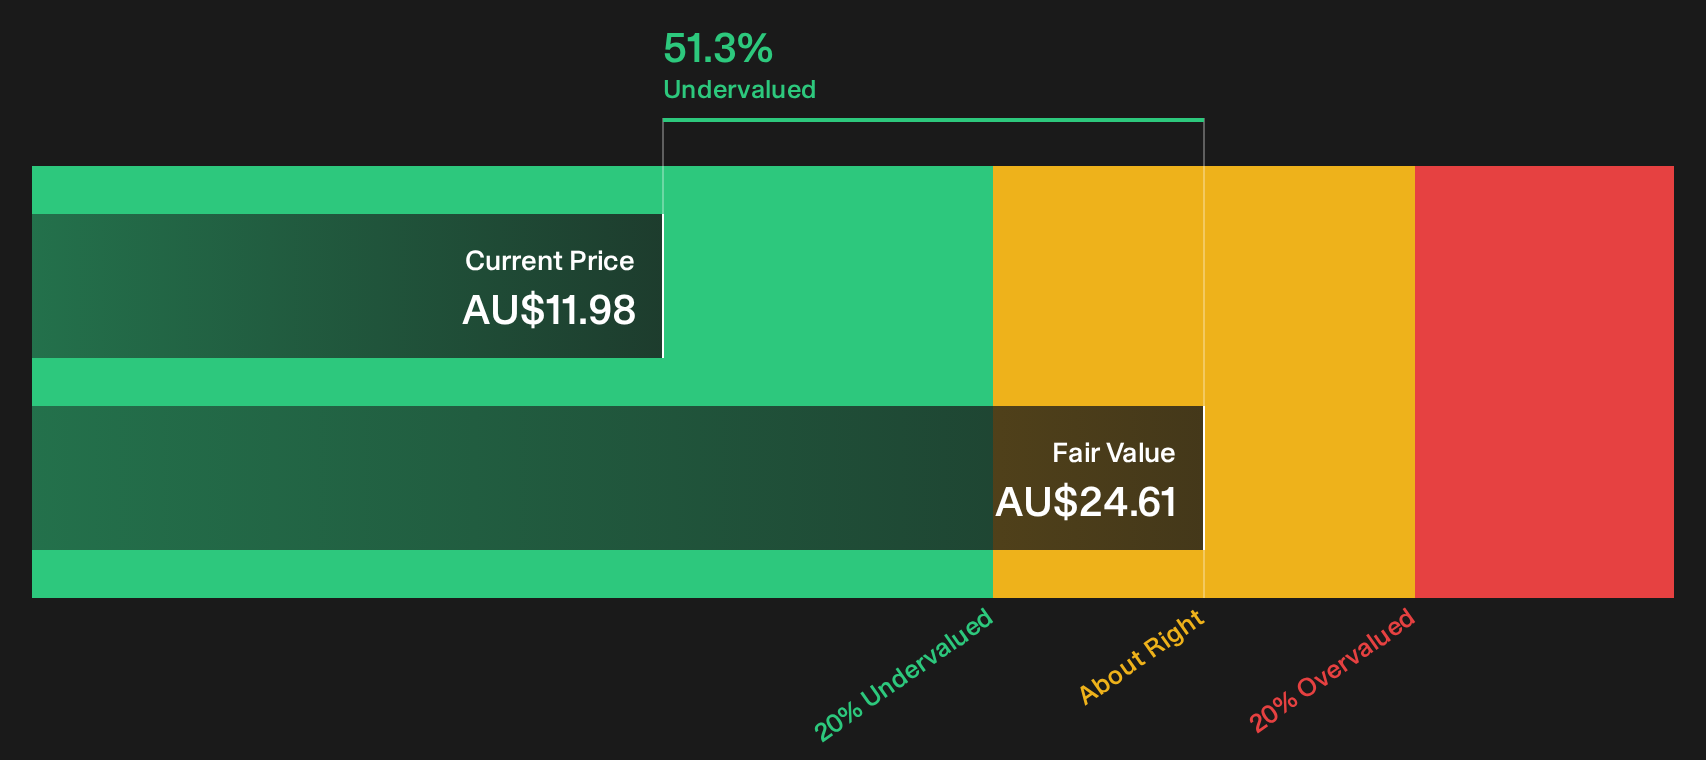
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Premier Investments for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Premier Investments can create noise, so move quickly, check the underlying data for yourself and weigh both sides in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Premier Investments?
If Premier Investments has sharpened your focus on value, do not stop here. Broader opportunities often sit just outside the stocks already on your radar.
- Target sturdier balance sheets and consistent fundamentals by scanning a list of solid balance sheet and fundamentals (12 results) that filters for financial strength and resilience.
- Hunt for quality companies that trade below their estimated worth with a 5 high quality undervalued stocks tailored to highlight stronger cash flows and cleaner accounts.
- Spot potential future standouts early by running a 15 high quality undiscovered gems that focuses on under-followed businesses with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com