


Snap-on (SNA) heads into its upcoming Q3 earnings report with investor attention on whether the tools specialist can extend its recent pattern of topping Wall Street’s EPS expectations while maintaining single digit year over year growth.
At around US$363 per share, Snap-on has seen its share price retreat 5.9% over the past month and 11.8% over the last quarter, even though the year to date share price return is still positive at 3.5% and the 5 year total shareholder return sits near 92%. This suggests recent weakness has come after a solid multi year run and leaves investors watching this Q3 report for clues on whether sentiment is cooling or simply pausing.
Compare Snap-on's recent pullback with other tool and industrial specialists by scanning our curated list of list of solid balance sheet and fundamentals (25 results) before this earnings season resets expectations.
The pullback leaves Snap-on trading below both its analyst price target and one intrinsic value estimate, creating a wide gap that needs sorting out. Is this discount justified by fundamentals or mispriced caution before earnings?
Most Popular Narrative: 10% Overvalued
Snap-on last closed at $363.35, while the most followed narrative anchors fair value at $330. This implies the recent pullback still leaves the stock above that reference point and places additional focus on how Q3 earnings shape the story.
Even as Snap-on points to strong execution in extending its tools and systems into critical industries such as aviation, data centers and natural resources, the reliance on the Commercial & Industrial Group to support consolidated sales and margin records leaves the group exposed if double digit organic growth and the 16.8% operating margin seen in Q2 2026 fade. This would have a direct effect on consolidated operating margin resilience.
See why 1 investors see Snap-on as 10% overvalued.
Result: Fair Value of $330 (OVERVALUED)
Still, record quarterly sales with Q2 2026 revenue of US$1.2351b and a 25.2% operating margin, along with ongoing buybacks and a higher dividend, could pressure a cautious Snap-on valuation view if those supports hold up through softer sentiment.
Find out about the key risks to this Snap-on narrative.
Another Angle On Snap-on’s Valuation
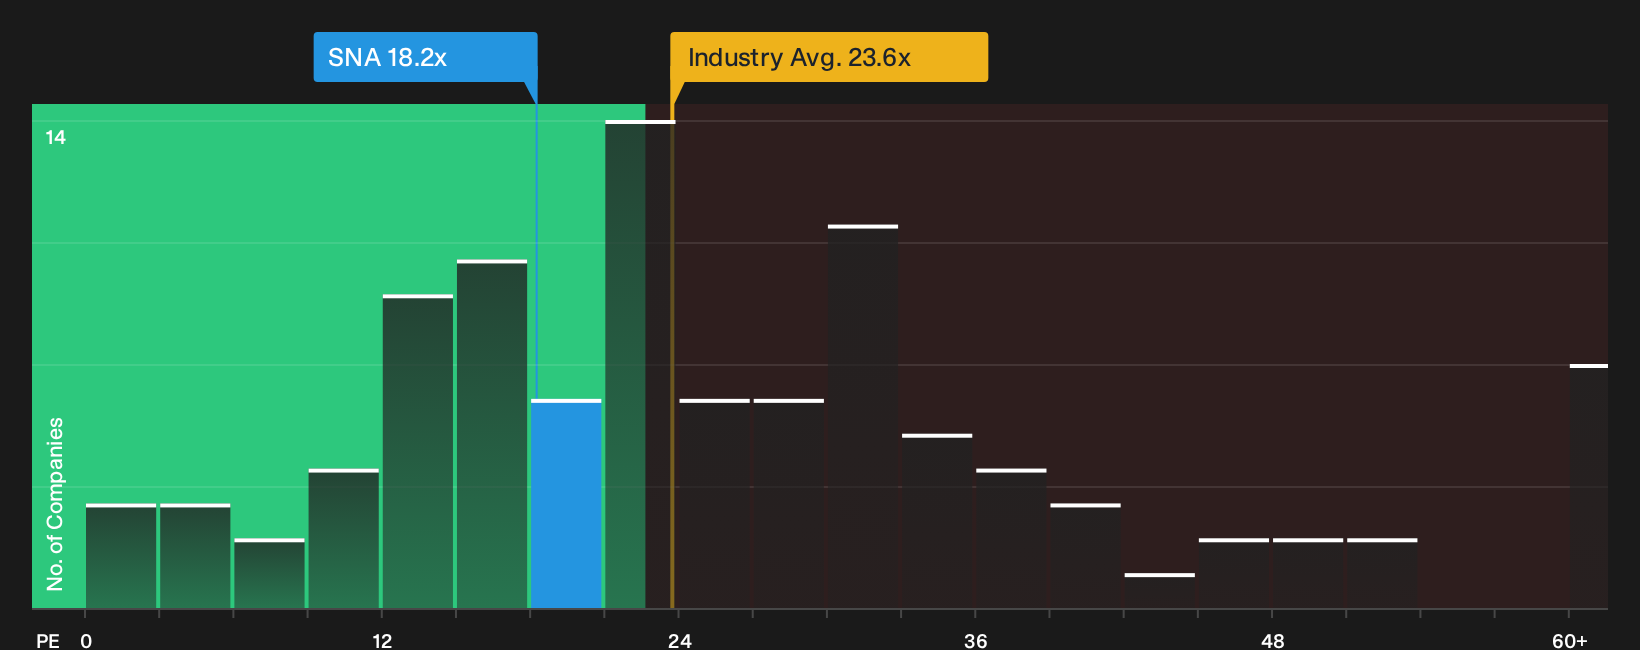
The bearish narrative places Snap-on’s fair value at $330, yet the stock trades on a P/E of 18.2x versus 31x for peers and 24.2x for the wider US Machinery group. That is also below a fair ratio of 20.4x. Is the discount signaling opportunity or lingering risk the market still needs to price in?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure whether current sentiment around Snap-on feels too cautious or not cautious enough, given the mix of valuation signals and recent pricing? Move quickly, review the data for yourself, and then weigh it against the 5 key rewards.
Looking for more ideas beyond Snap-on?
If Snap-on has you thinking harder about valuation and timing, do not stop there. Put that curiosity to work by scanning fresh opportunities with focused screeners across the market.
- Target resilient compounders with healthy cash positions and low leverage by running our 31 resilient stocks with low risk scores that filters for businesses built to handle stress.
- Zero in on higher yield opportunities by checking the 7 dividend fortresses that highlights companies pairing income potential with underlying fundamental support.
- Get ahead of the crowd by reviewing the 19 high quality undiscovered gems that surfaces underfollowed stocks with financial profiles that may warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com